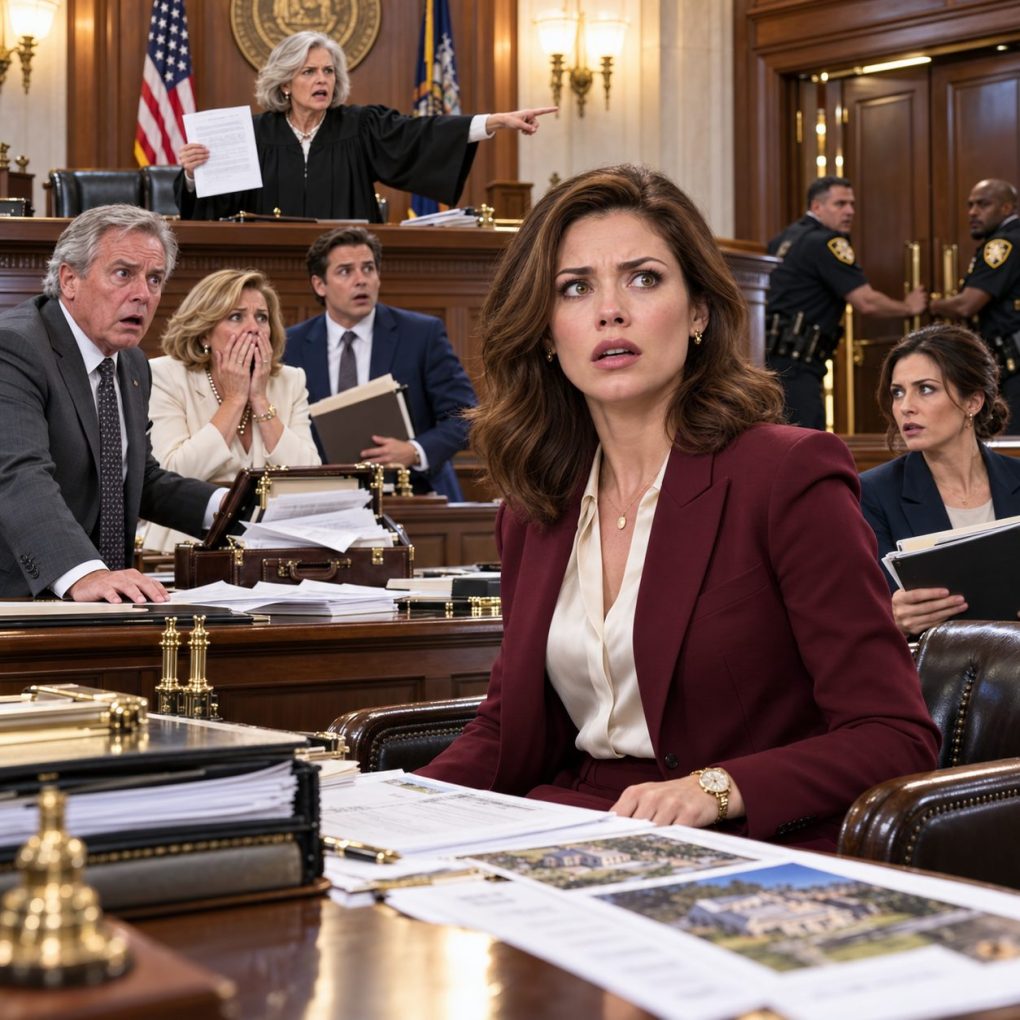
The bailiff had barely closed the courtroom doors when my mother pointed at me and said, “Your Honor, she cannot be trusted with that much money.”
I was sitting six feet away from her, staring at the woman who had taught me to balance a checkbook when I was twelve.
My father kept his eyes on the judge.
Their attorney, Martin Keene, smiled like the hearing was already over.
They were asking the probate court in Columbus, Ohio, to place my inheritance under a court-appointed conservatorship. Not just the inheritance my grandmother had left me, either. Their filing requested control over my checking account, my car, and the condo I had purchased three years earlier with my own salary.
According to them, I was reckless, emotionally unstable, and “financially vulnerable.”
I was thirty-four years old.
I worked as a senior compliance analyst for a regional bank.
And I had never missed a mortgage payment in my life.
Still, Keene stood and calmly described me as someone who made “impulsive financial decisions.”
The judge, Eleanor Whitcomb, looked over her glasses.
“What decisions?”
Keene glanced at my parents.
My mother answered first. “She moved money without telling us.”
I almost laughed.
It was my money.
But my attorney, Rachel Mendoza, touched my sleeve under the table, warning me to stay quiet.
Keene continued. “She has also refused to disclose certain accounts to her family.”
Judge Whitcomb frowned. “Why would she be required to disclose her accounts to her family?”
For the first time, Keene’s smile weakened.
My father leaned toward him and whispered something.
Then Keene recovered.
“Because the inheritance is substantial, Your Honor. Her late grandmother intended the family to protect those assets.”
That was false.
My grandmother’s will said the opposite.
She had left me her estate specifically because, in her words, I was the only person in the family who had never asked her for money.
Rachel slid a certified copy of the will toward the clerk.
Then she handed over a sealed financial disclosure the court had requested from me.
Keene actually smirked.
I knew why.
My parents believed I had inherited about $680,000.
That was the number they had seen in an old estate estimate.
They thought this hearing was about controlling that money before I could “waste” it.
Judge Whitcomb opened my disclosure.
She read the first page.
Then the second.
Her expression changed.
She looked at Rachel.
“Ms. Mendoza, these figures are verified?”
“Yes, Your Honor.”
The judge turned another page.
Keene stopped smiling.
My mother leaned forward.
My father whispered, “What is it?”
Judge Whitcomb read silently for several seconds.
Then she looked directly at me.
“Ms. Carter, did you authorize either of your parents to access any account listed here?”
“No, Your Honor.”
The courtroom went completely still.
The judge’s face drained of color.
She abruptly stood.
“Stop immediately.”
Keene froze.
Judge Whitcomb turned toward the bailiff.
“Lock those doors. Call security. No one leaves this courtroom.”
My mother gasped.
And then the judge lifted one page from my financial disclosure and asked my father a question that made him grip the table.
I had walked into court expecting to defend my inheritance. I had no idea the documents would reveal something far worse, or that the judge had just recognized a name connected to my parents. Then my father tried to reach for his briefcase.
“Mr. Carter,” Judge Whitcomb said, “why is your name listed as an authorized signer on an account your daughter says she never authorized?”
My father stopped moving.
Keene immediately stood. “Your Honor, there may be an innocent administrative explanation.”
“There may be,” the judge replied. “Which is why no one is leaving.”
The bailiff stepped behind my parents.
My stomach tightened.
Rachel whispered, “Do not say anything unless the judge asks you directly.”
Judge Whitcomb handed the page to the clerk and requested the exhibits Rachel had filed that morning. I had known Rachel was investigating unusual activity connected to my grandmother’s estate, but even I had not seen everything.
The first exhibit was a signature card from an investment account containing $1.8 million.
My supposed signature appeared beside my father’s.
It was not mine.
The second exhibit showed a home-equity line opened against my condo eight months earlier.
Again, there was my “signature.”
Again, it was fake.
My mother started crying.
She said they had only been “protecting” me.
But Judge Whitcomb kept reading.
Then came the twist none of us expected.
The inheritance was not the largest asset on the list.
Years before she died, my grandmother had quietly transferred shares of a private logistics company into a trust for me. Those shares had appreciated dramatically after a merger.
My total assets were worth just over $8.2 million.
My parents had apparently discovered the trust before I did.
And according to the documents Rachel obtained, someone had spent nearly a year trying to position my father as my legal financial controller before the merger payout became available.
The conservatorship petition was not about protecting me.
It was their final step.
Keene looked sick.
Then Judge Whitcomb turned to him.
“Mr. Keene, did you prepare these supporting declarations?”
“Yes, Your Honor, based on information provided by my clients.”
“Did your clients provide you with the medical evaluation attached to their petition?”
Keene hesitated.
That was when Rachel stood.
“We have reason to believe the evaluation is fabricated.”
My mother made a sound like she had been punched.
The document claimed a psychiatrist had diagnosed me with impaired judgment after examining me twice.
I had never met the doctor.
Judge Whitcomb ordered the clerk to contact the physician’s office immediately.
Five minutes later, the clerk returned and whispered into her ear.
The judge’s expression hardened.
“The physician whose name appears on this evaluation died fourteen months ago.”
Nobody spoke.
My father suddenly grabbed his briefcase.
The bailiff stepped forward.
But before security reached him, the case fell open.
A stack of papers spilled across the floor.
Rachel stared at the top page.
Then she looked at me.
“Emily,” she said quietly, “that’s not your grandmother’s signature either.”
And this time, the document was a deed.
The deed transferred my grandmother’s lake house to a company I had never heard of.
Judge Whitcomb ordered the bailiff to collect every paper that had fallen from my father’s briefcase.
My father insisted the documents were privileged.
Keene backed away from him.
“They are not my files,” he said.
That sentence ended whatever loyalty remained between them.
Rachel asked to inspect the deed. The judge allowed it under the clerk’s supervision.
The company named on it was Carter Family Holdings LLC.
Its members were my parents.
The deed had supposedly been signed six weeks before my grandmother died.
There was one problem.
My grandmother had been hospitalized that week after a stroke and could barely move her right hand.
Rachel already had her medical records.
The signature on the deed was smooth and confident.
The notary created an even bigger problem.
He told investigators that afternoon he had never met my grandmother and had never notarized the document.
By sunset, the hearing had turned into a criminal referral.
Judge Whitcomb denied the conservatorship petition with prejudice, froze disputed transfers connected to my parents, and ordered the evidence sent to the county prosecutor and state financial-crimes unit.
The police did not handcuff my parents in the courtroom.
But they escorted them into separate interview rooms.
Keene remained behind to explain how a dead doctor’s name had appeared on a filing carrying his signature.
Rachel and I left through a side hallway.
I should have felt triumphant.
Instead, I felt hollow.
My own parents had tried to convince a court I was incompetent so they could gain access to money they had already been stealing.
Two months later, investigators confirmed the scheme.
My father had used forged authorization forms to access one investment account.
My mother had supplied personal information and copies of my identification.
Together, they had attempted to borrow against my condo and transfer my grandmother’s lake house into their company.
The fake psychiatric evaluation came from an old template found on my father’s laptop.
Keene was not charged with participating in the theft, but the state bar investigated whether he had ignored obvious red flags.
My parents eventually pleaded guilty to multiple felony counts involving forgery, attempted theft, and identity fraud.
Under the restitution agreement, the lake house returned to my grandmother’s estate, the fraudulent credit line was canceled, and every dollar traced to the unauthorized account was restored.
I kept the condo.
I kept my car.
I kept control of every account.
Most importantly, I kept my name.
For months, that mattered more than the $8.2 million.
My grandmother had not left me wealth because she thought money would make me happy.
She left it because she trusted my judgment.
On the day the criminal case ended, Rachel gave me a sealed letter found in my grandmother’s safe-deposit box.
It contained one sentence:
“Emily, never let anyone confuse love with control.”
I read it twice in the courthouse hallway.
Then I folded it and put it in my purse.
My parents had entered court believing they could take my independence by calling me irresponsible.
Instead, they exposed themselves.
And for the first time in my life, I walked away without asking their permission.