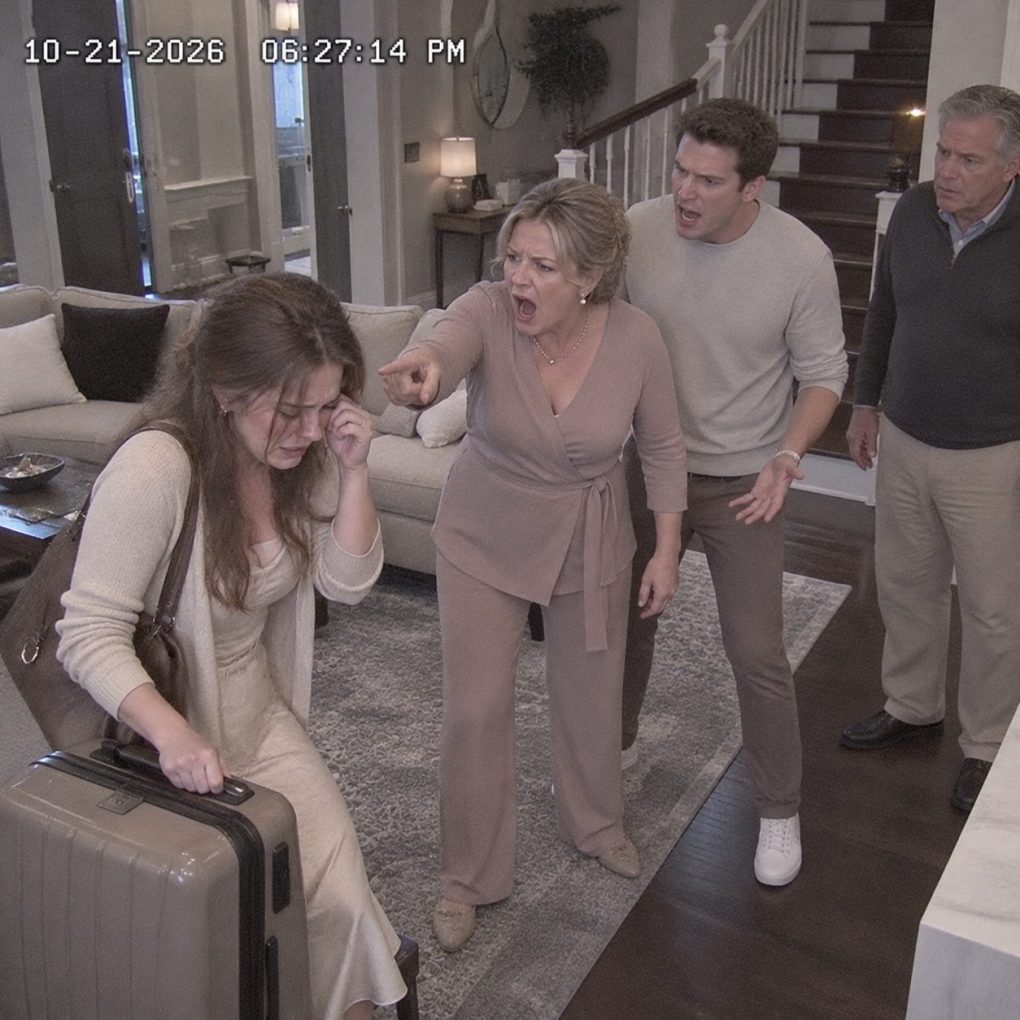
“Your brother is my only loyal child. Get out of my house!” My mother screamed those words while throwing my overnight bag onto the porch. My brother, Ryan, stood behind her, smiling. For two years, I had secretly sent her $1,500 every month to keep her from losing that house. Ryan had contributed nothing. I left in tears, but three days later, a bank employee called about a suspicious loan application. What she revealed made me realize my mother’s debts weren’t what I thought.
My name is Allison Carter. I was thirty-six and worked as an operations manager in Columbus, Ohio. After my father died, my mother, Patricia, struggled with household expenses. She told me his medical bills and the remaining mortgage had exhausted her savings.
I immediately offered financial assistance. She refused at first, insisting she didn’t want Ryan to know she needed help. Eventually, we agreed that I would transfer $1,500 monthly into her checking account. I never told my brother because Mom begged me to keep the arrangement private.
Ryan was thirty-two, charming, unemployed more often than not, and constantly launching businesses that never survived. My mother defended him relentlessly. Whenever I questioned his spending, she accused me of being jealous because he had bigger dreams than I did.
On Sunday, I visited Mom for dinner. Ryan was there, showing her photographs of a luxury pickup truck he wanted to purchase. When I asked how he planned to afford it, he laughed. “Successful people don’t think small, Allison.”
Mom immediately defended him. She said Ryan was brave enough to take risks, unlike me, who merely worked for a salary. I reminded her that steady employment had its advantages. Ryan rolled his eyes and called me a boring accountant.
Then Mom announced that Ryan was moving back into her house. She wanted me to stop questioning his decisions and apologize for disrespecting him. I refused. “Mom, he’s thirty-two. Asking how he’ll pay for an expensive truck isn’t an insult.”
She stood so suddenly that her chair scraped the floor. “Ryan is the only child who’s stayed loyal to me since your father died!” I stared at her, waiting for her to acknowledge the money I had sent. Instead, she pointed toward the door.
“Leave. And don’t come back until you learn to respect your brother.” Ryan carried my overnight bag outside and dropped it beside the steps. I drove home crying, then canceled the next automatic transfer after sending Mom written notice.
Three days later, a loan officer from my credit union called to verify an application listing me as a guarantor. I had signed nothing. The application requested $85,000 for a business owned by Ryan. Attached was a financial statement claiming my mother received $1,500 monthly in rental income from me. Suddenly, her constant financial emergencies began making terrible sense.
I asked the loan officer to suspend the application immediately. She explained that the credit union had flagged inconsistencies during verification and had not approved or funded the loan. The documents included my full name, employment information, and an electronic signature that I did not recognize.
I contacted the credit union’s fraud department and filed a formal identity theft report. Then I called an attorney, Rebecca Miller, who advised me to preserve every financial record and avoid confronting Ryan until we understood what had happened. I spent the evening downloading twenty-four months of transfers to my mother’s account.
The total was $36,000. I had sent that money believing I was preventing foreclosure. Yet the loan application described my payments as rent from a tenant. Worse, it listed my mother’s house as collateral for Ryan’s proposed business loan, even though she had previously told me the property was already heavily mortgaged.
Rebecca helped me obtain publicly available property records. My mother’s original mortgage had been paid off eighteen months earlier using proceeds from my father’s life insurance policy. There was no active mortgage threatening her home when she continued asking me for money.
I stared at the records in disbelief. Mom had repeatedly told me that my payments were barely keeping the bank satisfied. She had cried over supposed foreclosure notices and begged me not to miss a month. Now I knew that at least part of her story had been false.
The next morning, I visited her with Rebecca present. Ryan opened the door and immediately demanded to know why I had brought a lawyer. I asked my mother whether she knew about the $85,000 loan application. Her face drained of color.
Ryan interrupted before she could answer. “It’s a normal business loan. Stop acting hysterical.” Rebecca calmly explained that someone had submitted an application identifying me as a guarantor without my authorization. She asked whether Ryan had prepared the documents. He refused to answer.
Mom began crying. She admitted that she had used most of my monthly payments to cover Ryan’s credit card bills, vehicle payments, and expenses for his failed businesses. She had also allowed him to use her house as proposed collateral because he promised his next venture would make them wealthy.
I asked why she had lied about the mortgage. She whispered, “I knew you wouldn’t help Ryan if I told you the truth.” Ryan shouted that she was making him sound like a criminal. Then he claimed I owed him support because I had a better job.
I looked directly at my mother. “You watched me postpone buying my own home while I paid for his lifestyle.” She couldn’t meet my eyes. Rebecca ended the conversation when Ryan began shouting again.
That afternoon, the credit union provided confirmation that the loan application had been rejected and referred for investigation. I placed fraud alerts on my credit reports and reviewed my accounts. For the first time, I understood that my mother’s financial crisis had been manufactured to protect Ryan from the consequences of his decisions.
The investigation continued over the following weeks. The credit union’s records showed that the loan application had been submitted using Ryan’s business email address. Investigators also identified an uploaded guarantor form containing an electronic signature that did not match the authorization process I normally used.
I cooperated with the investigation and provided evidence that I had never agreed to guarantee Ryan’s debts. My attorney advised me to keep all communication with him in writing. Ryan sent several furious messages accusing me of destroying his future, but I refused to respond to his threats.
My mother called repeatedly, begging me to withdraw the complaint. She insisted that Ryan had only been trying to save his business. I explained that using someone’s identity without permission was not a harmless family misunderstanding. Whatever his intentions, he had attempted to expose me to substantial financial liability.
Eventually, Mom admitted another painful truth. Ryan had convinced her that I was financially comfortable enough to support them indefinitely. Whenever she expressed guilt, he reminded her that I owned a newer car and had a stable career. He treated my independence as proof that I didn’t need the money.
I told her that my financial stability had come from years of careful planning. The $36,000 I had sent represented savings I could have used toward a down payment on my own home. She apologized, but I explained that trust could not be restored through words alone.
With Rebecca’s help, I prepared a written request for repayment of the money obtained through my mother’s false claims about her mortgage expenses. My mother initially resisted, arguing that families shouldn’t keep financial accounts. I reminded her that she had turned our relationship into a financial arrangement when she repeatedly lied to obtain my assistance.
After reviewing her finances, she agreed to sell an unused investment property she had inherited from my grandmother. The sale provided enough money to repay the $36,000 over several installments while leaving her primary residence untouched. We documented the repayment agreement through our attorneys.
Ryan’s proposed business never received the loan. The investigation into the unauthorized application proceeded separately, and I did not interfere with it. He eventually moved out of Mom’s house after she refused to guarantee additional debts. For the first time, she began attending financial counseling and managing her expenses without relying on either child.
Six months later, Mom invited me to lunch. She arrived without Ryan and brought a folder containing proof of the latest repayment installment. She apologized for calling him her only loyal child and admitted that she had mistaken his dependence for love while taking my generosity for granted.
I accepted her apology but explained that our relationship would need time to heal. I would visit occasionally, but I would no longer provide money or conceal financial arrangements from other family members. She nodded and said she understood.
One year after she threw my bag onto the porch, I received the final repayment installment. I used the money toward the down payment on a small townhouse outside Columbus. On moving day, I stood in my new living room holding the keys and remembered how desperately I had once wanted my mother’s approval. I still loved her, but I no longer needed to purchase a place in her heart. For the first time, the home I was protecting was my own.