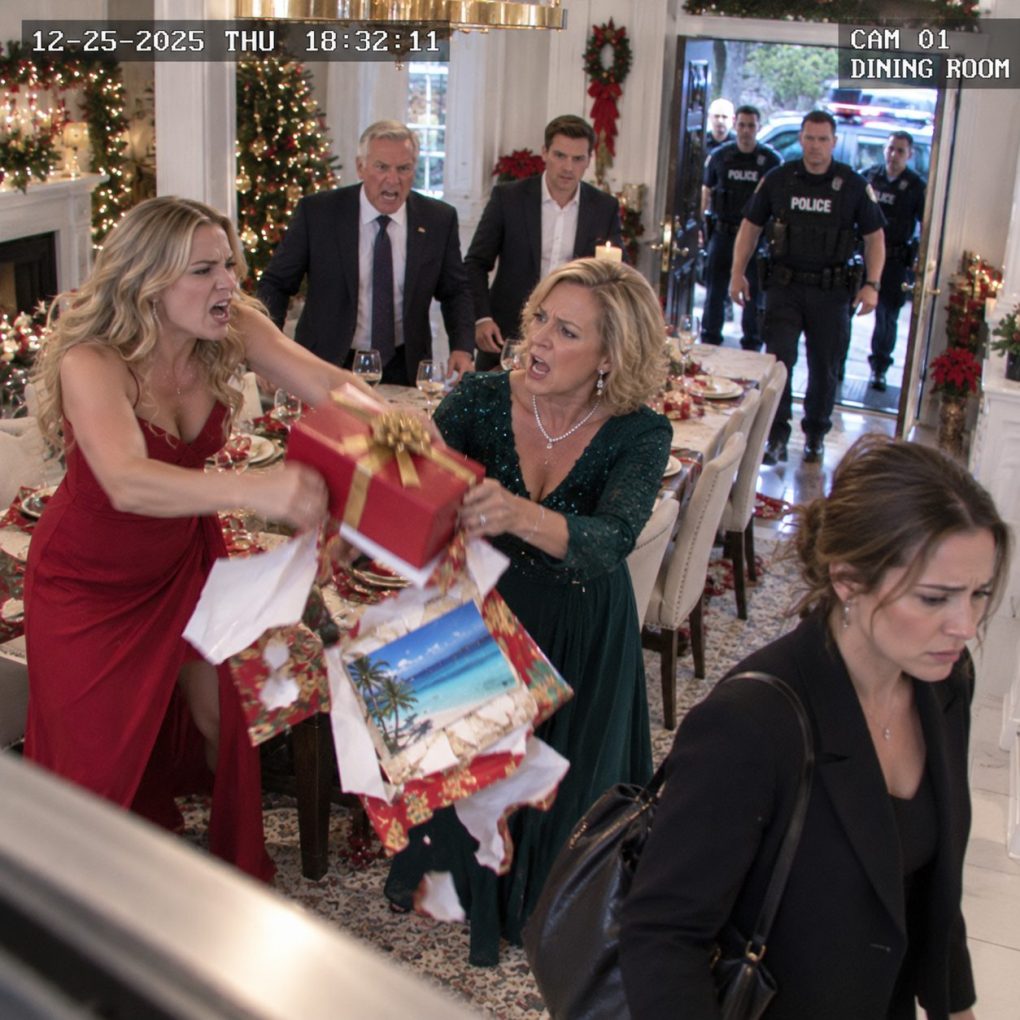
Dad waited until everyone had finished dessert before sliding a gold envelope across the table to my sister.
“Open it, Madison.”
She screamed before she had even finished reading.
Seven nights in Maui.
Oceanfront hotel.
First-class airfare for two.
A private snorkeling excursion.
Mom clapped while Madison threw her arms around Dad.
Then he looked directly at me.
“You’re probably wondering where yours is.”
I wasn’t.
That was the humiliating part.
At thirty-six, I had spent almost a decade learning exactly what role my family expected me to play. Madison received rescue. I received responsibility.
Dad raised his glass.
“She deserves some joy after everything she’s been through.”
Madison’s latest “everything” was quitting a job after four months because her manager criticized her attendance.
Dad continued.
“You’ve always been the dependable one, Claire. You don’t need presents. You need responsibilities.”
Mom smiled as though he had complimented me.
I looked around the Christmas table.
For the past eighteen months, I had paid my parents’ property taxes, replaced their furnace, covered Dad’s dental surgery, and sent $1,400 every month because they repeatedly told me retirement had become harder than expected.
I had never asked them to buy me Hawaii.
But watching them spend thousands while telling me they could barely afford groceries made something inside me become very quiet.
“How much was the trip?” I asked.
Dad’s smile disappeared.
“Don’t ruin this.”
“I asked a number.”
Mom sighed.
“Claire, money isn’t everything.”
Interesting answer from people who called me whenever they needed it.
Madison tucked the travel packet against her chest.
“Can you just be happy for me once?”
I stood.
“Yes.”
Everyone stared.
“I hope you have a wonderful trip.”
Then I picked up my coat and left.
No screaming.
No speech.
No demand for repayment.
Outside, snow had started falling across the driveway.
I reached my car when my phone buzzed.
FRAUD ALERT — $14,860 — PACIFIC LUXURY TRAVEL.
I stopped.
The card number underneath was unfamiliar.
I opened my credit-monitoring app.
A new account had appeared eleven days earlier.
Opened in my name.
Billing address: my parents’ house.
My hands went cold.
Three months earlier, after someone unsuccessfully applied for financing using my Social Security number, I had frozen my credit and filed an identity-theft report.
Someone had apparently found a way around the freeze using information from an older application.
I called the card issuer first.
Then the police department handling the earlier report.
The officer asked one question.
“Do you know where the physical card is?”
I looked through the dining-room window.
Dad was holding something blue beside the travel packet.
“I think I do.”
Thirty minutes later, two patrol cars stopped outside my parents’ house.
Madison came to the window first.
Dad opened the door furious.
Then one officer asked him to step aside.
“We’re following up on an identity-theft investigation involving Claire Bennett.”
Dad’s face changed.
Mom whispered, “Identity theft?”
The officer looked down at the report in his hand.
“Specifically, a credit account opened eleven days ago.”
Then he added:
“And that isn’t the only account opened in her name.”
The officers did not arrest my parents because of an expensive Christmas present. They were following up on an existing identity-theft report, and the new credit-card alert connected activity at my parents’ address to the earlier investigation. I stayed outside while they spoke separately with Dad and Mom.
The Hawaii charge was straightforward. The card issuer confirmed that an online application had been submitted using my identifying information, my income, and my credit history. The email address belonged to Dad. The application listed his house as my “temporary residence,” even though I had not lived there in fourteen years.
Dad initially claimed I had agreed to help finance Madison’s trip. That explanation collapsed when the issuer produced the recorded verification call. A man identifying himself as my “financial representative” had answered several questions and requested expedited delivery of the card to my parents’ address.
The second account was worse. Someone had opened a $32,000 personal line of credit in my name six weeks earlier. Nearly $21,000 had already been transferred into a joint checking account owned by my parents. Dad told investigators the money covered “family expenses.”
Those family expenses included a new roof, Madison’s car payment, $4,800 toward her credit-card balance, and the deposit for the Hawaii vacation. My monthly support had continued throughout the same period. While I believed I was keeping my parents afloat, they were quietly borrowing additional money under my identity.
Mom cried when I confronted her later with my attorney present. “Your father said you’d pay it anyway.” I stared at her. “So you thought that made it acceptable?” She answered, “You make more money than all of us combined.” That was not an answer. It was the justification they had been using for years.
Madison insisted she knew nothing about the fraudulent accounts. The records supported part of that claim. Dad had told her the Hawaii trip came from reward points and savings. She knew our parents depended financially on me, but investigators found no evidence she participated in the applications.
Dad’s story changed repeatedly. First I had authorized everything verbally. Then he claimed I had given him broad permission years earlier to “handle family finances.” Finally, through counsel, he admitted opening the accounts but argued that he intended to repay them before I discovered them.
My attorney, Rebecca Sloan, said something I needed to hear: repayment plans created after discovery do not retroactively create consent. We disputed both accounts, preserved the issuer records, and provided the investigation with copies of every legitimate transfer I had voluntarily made to my parents so there would be a clear distinction between support and unauthorized debt.
Then the bank records exposed a pattern nobody expected. The false accounts did not begin six weeks earlier. Over almost three years, Dad had opened and closed smaller credit lines using my information, paying one with another whenever statements became difficult to hide.
The total borrowed exceeded $96,000.
And buried among those transfers was a recurring payment to an account I did not recognize.
Rebecca traced it.
It belonged to Madison’s landlord.
For twenty-two months, my father had secretly been paying my sister’s rent with debt taken out in my name.
Madison cried when she learned where the rent money came from. Dad had told her he was using investment income. She admitted she should have questioned how our supposedly struggling parents could afford nearly $2,000 a month for her apartment, but wanting the explanation to be true had been easier.
Investigators reviewed each account separately. Some older records were incomplete, but the newer applications contained enough digital evidence to establish who submitted them. Dad eventually accepted responsibility for identity-theft and financial-fraud-related conduct through a negotiated plea rather than forcing the case through a lengthy trial.
Mom was not automatically charged with everything Dad had done. Investigators found that she knew about several accounts and benefited from them, but proof of her participation varied. She ultimately faced consequences tied only to the conduct investigators could establish, not simply because she was married to him.
The card issuer reversed the Hawaii transaction before the trip occurred. Madison never went. I did not cancel it to punish her; the purchase had been made through an account opened without my permission, so the transaction could not simply remain as her Christmas gift.
I stopped the $1,400 monthly transfers immediately. I did not abandon my parents without warning, however. Through Rebecca, I paid two essential bills directly for sixty days while they reorganized their legitimate finances. After that, they were responsible for their own budget.
Their house did not disappear. Their electricity stayed on. Dad’s medications remained affordable through his insurance. The catastrophe they had predicted when I stopped sending unrestricted money turned out to be mostly the loss of a lifestyle they could not actually afford.
Madison found a full-time job and moved into a smaller apartment when her lease ended. Six months later, she began sending me payments toward expenses Dad had covered for her through the fraudulent accounts. Legally, I did not require her to reimburse debts she had not created, but she said accepting every benefit without asking questions had still been part of the family pattern she wanted to break.
Dad and I did not speak directly for more than a year. His first letters were full of explanations: retirement fear, pressure to help Madison, embarrassment about money, certainty that I would eventually forgive him. I returned them unopened after the first few.
The letter I finally answered contained no defense. He wrote, “I turned your reliability into permission. Every time you rescued us, I decided it meant I was entitled to rescue someone else with your money.” That did not repair everything. It was simply the first sentence that showed he understood the damage.
Mom apologized separately. She admitted that calling me “responsible” had become a convenient way to deny me care while demanding more from me. Madison was allowed mistakes because everyone believed she needed softness. I was given burdens because everyone believed I could survive them.
Two Christmases later, I ate dinner at Madison’s apartment. The table was small. Nobody exchanged expensive gifts. Dad and Mom were not there yet; reconciliation had not progressed that far. Madison handed me a mug that cost probably twelve dollars and said, “This one was actually bought with my money.”
I laughed.
That was enough.
The night Dad toasted my “responsibility,” he meant that I should continue carrying whatever the family placed on me without complaint. Thirty minutes later, the police arrived because responsibility had finally acquired documentation—credit applications, bank transfers, verification recordings, and accounts nobody could explain away as family generosity.
I never needed a trip to Hawaii.
I needed something far simpler.
For the people who loved me to understand that being dependable did not make my identity, income, credit, or future available for everyone else to spend.