“My family cut me off completely—so I cancelled the direct deposits funding their lives.”
At 8:17 on a Tuesday morning, my family sent me a group text that ended seventeen years of financial support in a single sentence.
“We need distance from you. Please stop contacting us completely. Do not come to the house again.”
I was standing outside a conference room at my office in Columbus, Ohio, when I read it.
Before I could respond, my uncle, Richard, called.
“Claire, I need you to stay calm,” he said. “Your parents asked me to help them move some things. I’m at their house now.”
“Move what things?”
There was a long silence.
“Your belongings. They want everything of yours out before the weekend.”
I stared at the message again.
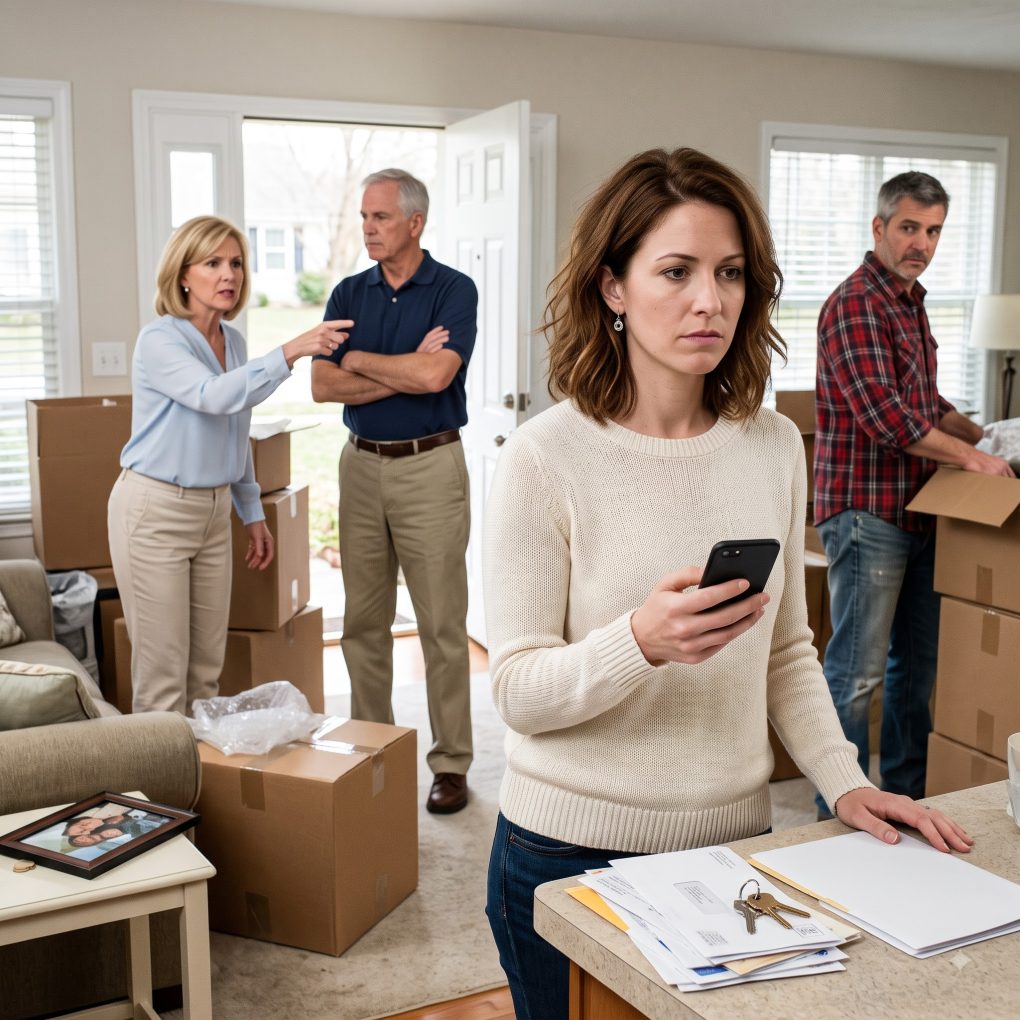
My parents had asked Uncle Richard to pack up my childhood bedroom, the room I had kept available for every visit, every holiday, every emergency that supposedly required me to come running.
My younger brother, Evan, had apparently decided that my presence in the family was the problem.
And my parents had agreed.
I could have called them. I could have demanded an explanation.
Instead, I typed one sentence into the family group chat.
“Of course. I’ll cancel my direct deposits first thing.”
Then I put my phone away and walked into my meeting.
At 9:03, my mother called.
I declined.
At 9:06, my father called.
I declined that one, too.
By 9:15, Evan had sent me six messages.
The first said I was being dramatic.
The second accused me of holding money over everyone’s heads.
The third simply read, “You wouldn’t dare.”
That was when I opened my banking app.
For eleven years, I had transferred $2,400 a month into my parents’ joint account. I paid their property taxes, covered their homeowners insurance, and handled the mortgage shortfall they claimed they couldn’t manage after my father’s business failed.
I had never missed a payment.
Not once.
I canceled the recurring transfers.
Then I called the mortgage company to remove my checking account from their automatic payment arrangement.
The representative paused while reviewing the account.
“Ms. Bennett,” she said carefully, “before I make that change, I need to clarify something about the property.”
My stomach tightened.
“What property?”
“The house your parents are living in.”
She lowered her voice.
“Your name is listed on the mortgage documents, but there’s another issue. According to our records, you’re not just a financial contributor.”
I gripped the edge of my desk.
“What are you saying?”
“I’m saying you may want to speak with an attorney before making any further decisions.”
Then she told me who actually owned my parents’ house.
And it wasn’t my father.
A little later, I discovered that the message telling me to stay away was only the beginning. My family had made a decision about my future without telling me—and the first person to realize what that decision would cost them was the one man they had trusted to pack my belongings.
“I’m sorry,” I said to the mortgage representative. “Could you repeat that?”
“According to the recorded documents, Claire Bennett is the sole owner of the property.”
For several seconds, I couldn’t speak.
The house was a four-bedroom colonial in a quiet suburb outside Columbus. My parents had lived there for twenty-two years. It was where Evan and I had grown up, where we’d celebrated birthdays, and where my mother had hosted every Thanksgiving dinner since I could remember.
And apparently, it was mine.
The representative explained that the mortgage had been refinanced six years earlier. My father had been unable to qualify after his business collapsed, and my parents had approached me with a proposal.
They said I would temporarily take ownership to secure a better interest rate.
They promised to transfer the house back once my father’s finances recovered.
I remembered signing documents at a title office after work. My father had assured me that everything was routine. My mother had cried about losing the family home.
I had agreed because I thought I was saving them.
But the recorded deed had never been transferred back.
I asked the representative to email me the documents.
Then I called Uncle Richard.
He answered immediately.
“Claire, thank goodness. Your mother says you’re threatening to cut them off.”
“Did they tell you why they’re moving my things?”
He exhaled.
“Evan and his fiancée want the house. Your parents think it’s time they had a fresh start. They asked me to help clear your room so Evan can use it as an office.”
“Did they tell you they’re planning to sell the house?”
Silence.
“Sell it?” he repeated.
“They can’t sell it without dealing with the ownership.”
Richard went quiet.
Then he said something that made my hands go cold.
“Claire, your father told me the house was already transferred to Evan. He said you’d signed the paperwork months ago.”
“I haven’t signed anything.”
Richard swore under his breath.
He sent me a photograph of a folder sitting on my parents’ dining table.
Inside was a printed real estate listing agreement.
The seller’s signature was supposed to be mine.
It wasn’t.
Someone had copied my signature from an old document.
The house was scheduled to be listed that Friday.
I immediately contacted an attorney named Melissa Grant, who reviewed the documents and advised me not to confront my parents until we understood what had happened.
That evening, Uncle Richard called again.
“I found something else,” he said. “Your father asked me to pack the filing cabinet in the study. There are copies of the documents they planned to use.”
“What documents?”
“There’s a power of attorney with your name on it. And Claire…”
His voice cracked.
“Your mother told me you had agreed to give Evan the house.”
I closed my eyes.
Then Richard read me a sentence from the document.
It stated that I had voluntarily authorized my father to sign property-related paperwork on my behalf.
The signature looked almost exactly like mine.
Almost.
Melissa examined the document the next morning. She told me that a forged signature on a power of attorney could create serious legal problems, but she needed the original documents and a complete record of the attempted transaction.
Then she discovered a detail that changed everything.
The buyer listed on the proposed sale wasn’t a stranger.
It was Evan’s fiancée’s father.
And the sale price was nearly $180,000 below the home’s estimated market value.
My parents weren’t simply trying to give my brother a house.
They were trying to transfer my property to his future in-laws at a bargain price.
But the biggest shock came when Melissa checked the financial records.
The house wasn’t the only thing my parents had used my name for.
There was a second loan.
And I had never authorized it.
Melissa arrived at my apartment on Friday morning carrying a thick folder and the expression of someone who had found exactly what she feared.
I had barely slept.
For six years, I had believed that taking ownership of my parents’ house was a temporary favor. I had paid the mortgage shortfall, property taxes, and insurance because I thought I was protecting their future.
Now I was learning that the favor had become an opportunity for them to use my name without my permission.
Melissa placed the folder on my kitchen table.
“The proposed sale is only one part of this,” she said. “We need to separate what you legally own from what your parents may have done without authorization.”
She showed me the recorded deed first.
My name appeared as the sole owner.
The mortgage was also in my name, which meant I was responsible for the loan under its terms. But the deed established my ownership of the property.
The second loan was more complicated.
A home-equity line of credit had been opened against the house fourteen months earlier. The balance was just over $86,000.
My parents had told me they were managing their expenses.
They had never mentioned borrowing against the property.
“Did you sign this?” Melissa asked.
I studied the application.
The signature was a close imitation of mine. My date of birth and Social Security number were correct. The application included my employment information, my salary, and the address of the company where I worked.
But I had not applied for the loan.
“No,” I said. “I never saw this.”
Melissa nodded.
“Then we need to notify the lender that you dispute the application. Don’t make any payments on the disputed balance until we’ve received legal advice about your obligations.”
She also recommended that I freeze my credit, obtain reports from all three credit bureaus, and preserve every message related to the property.
I followed her instructions.
By noon, the lender had opened a fraud investigation.
At 1:14 p.m., my father called.
I let it go to voicemail.
His message was short.
“Claire, whatever you’re doing, stop. You’ve made your point. Your mother is crying, Evan is furious, and we have people coming to see the house. Call me immediately.”
He didn’t ask whether I was okay.
He didn’t ask why I had stopped paying.
He didn’t ask what the lender had found.
He wanted me to stop.
At 1:27, my mother sent a message.
“You are destroying this family over money. Your father has worked his whole life for that house.”
I read it twice.
Then I replied.
“I’m not destroying anything. I’m asking why someone forged my signature.”
The typing indicator appeared.
Disappeared.
Appeared again.
Finally, she wrote:
“You know your father would never do anything to hurt you.”
That was the moment I understood that my parents were not going to tell me the truth simply because I asked.
I needed evidence.
And Uncle Richard had it.
He had spent Thursday evening going through the boxes my parents had asked him to pack. He’d found a folder labeled “House—Evan” beneath a stack of old tax returns.
He brought it to Melissa’s office that afternoon.
The folder contained a proposed purchase agreement, a draft power of attorney, copies of the disputed loan application, and a handwritten list of expenses.
The list included a new SUV for Evan, a deposit on a wedding venue, and payments toward his fiancée’s student loans.
The amounts totaled more than $70,000.
Beside them, my father had written:
“Use equity before listing.”
Richard sat across from me while Melissa reviewed the pages.
“I thought they were just helping Evan get started,” he said. “Your father told me you wanted him to have the house.”
“Why didn’t you ask me?”
Richard looked ashamed.
“Because I believed him. And because your parents always made it sound like you were the one who had everything.”
That sentence hurt more than I expected.
For years, I had worked long hours, taken promotions, and lived in a small apartment while my parents told relatives that I was fortunate and Evan was struggling.
I had helped because I could.
Somewhere along the way, my ability to help had become an expectation.
And my silence had become permission.
Melissa made copies of the documents and advised me to stop communicating with my parents about the dispute except through her office.
The next Monday, the lender confirmed that the home-equity application was under investigation. The title company handling the proposed sale was notified that ownership was disputed, and the closing was placed on hold.
Evan’s fiancée’s father withdrew from the transaction.
The house was no longer going to be sold that Friday.
But my family wasn’t finished.
On Tuesday evening, my parents arrived at my apartment.
My mother stood outside the door holding a casserole dish, as if she were visiting for an ordinary family dinner.
My father stood behind her with his hands in his coat pockets.
I opened the door but didn’t invite them in.
“Claire,” my mother began, “we need to talk.”
“Then talk.”
She looked at my father.
He stepped forward.
“We made some mistakes,” he said. “But this has gotten out of hand.”
“Which mistakes?”
He frowned.
“The paperwork. The loan. The sale. All of it.”
“Who signed my name?”
He looked away.
My mother began crying.
“Your father thought he was doing what was best for everyone.”
“Did you sign my name?”
She shook her head.
“I didn’t fill out the forms.”
“That wasn’t my question.”
My father finally spoke.
“I signed the power of attorney. I believed you would have agreed if we’d explained everything.”
“You didn’t explain anything. You told me to stay away from the family.”
He rubbed his face.
“We were under pressure. Evan needed help. His wedding is coming up, and his fiancée’s family expected him to have a house.”
“So you decided I should give him mine?”
“We thought you’d understand.”
I almost laughed.
They had told me to stop contacting them. They had ordered my uncle to pack my belongings. They had prepared to transfer my house to my brother and borrow against its value.
And now they were standing outside my apartment, asking me to understand.
My mother held out the casserole dish.
“I made your favorite.”
I looked at it.
Then I looked at her.
“I don’t want dinner. I want the truth.”
For the first time, my father stopped trying to defend himself.
He admitted that he had signed the documents. He claimed he had intended to repay the home-equity loan after Evan’s career improved. He said the proposed sale would have paid off the mortgage and left enough money for my parents to move into a smaller house.
“And where would I have lived?” I asked.
“You have a good job,” he said. “You could afford another place.”
The casualness of the answer stunned me.
My home was an asset to them. My income was a resource. My future was something they could rearrange whenever Evan needed another advantage.
I told them to leave.
My mother cried harder.
My father looked angry.
Neither apologized.
The following weeks were difficult, but the facts gradually became clear.
The lender’s investigation found inconsistencies in the home-equity application. The title company preserved the disputed sale documents, and Melissa worked with the appropriate professionals to challenge the unauthorized paperwork.
I cooperated fully with the investigation and provided copies of the messages in which my parents had told me to stop contacting them.
I also obtained independent legal advice about the mortgage and my responsibilities as the named borrower.
The process took months.
There were interviews, document requests, and difficult conversations. I learned that protecting my property did not automatically erase the mortgage obligations attached to it. I had to make careful decisions about the loan, the house, and my own financial security.
Eventually, the proposed sale was formally abandoned.
The lender resolved the disputed home-equity application through its investigation, and the unauthorized transaction did not proceed against my property. My attorney helped me establish safeguards against further attempts to use my identity or sign documents on my behalf.
I changed my banking arrangements, froze my credit, and required that any future property-related communication go through my attorney.
The house remained mine.
But I still had to decide what owning it meant.
I could have evicted my parents immediately. I could have demanded that they leave within days.
Instead, after consulting Melissa, I gave them a written, legally reviewed timeline to find another place to live.
They had relied on me for years, but I wasn’t willing to turn my anger into a decision that could create more legal problems.
My parents found a smaller rental home across town.
Evan was furious.
He called me one evening and said I had ruined his wedding plans.
“You could have helped me,” he said.
“I did help you. I paid for things you never knew about.”
“That was your choice.”
“Yes,” I replied. “And this is mine.”
He hung up.
Uncle Richard was the only family member who continued checking on me without asking for money or favors.
He apologized repeatedly for believing my father. I told him I understood why he’d trusted his brother, but I also told him that I needed time.
He respected that.
Months later, my parents sent me a letter.
It wasn’t a perfect apology.
They explained that they had convinced themselves I would eventually agree to everything. They said they had been embarrassed by their financial situation and afraid of disappointing Evan. They admitted that my willingness to help had made it easy to stop asking whether I wanted to.
The letter ended with a sentence that stayed with me:
“We thought you would always be there, no matter what we did.”
I didn’t reply immediately.
I read it once, folded it, and put it in a drawer.
Because that was the truth beneath everything.
They had mistaken my loyalty for an unlimited obligation.
They had mistaken my financial stability for an absence of feelings.
And they had mistaken my silence for consent.
I eventually sold the house.
Not because my parents demanded it, and not because Evan wanted it, but because I no longer wanted my childhood home tied to years of resentment and legal complications.
After the mortgage was paid and the remaining costs were settled, I used the proceeds to buy a modest townhouse closer to my office.
For the first time, every payment I made supported a life I had chosen for myself.
My relationship with my parents remained distant. We exchanged occasional messages, and I agreed to meet them for coffee once, with clear boundaries about money and property.
I didn’t promise that everything would return to normal.
It couldn’t.
Trust wasn’t a switch I could turn back on because they had finally admitted they were wrong.
Evan and I barely spoke.
At family gatherings, relatives sometimes asked whether I regretted canceling the transfers.
I always gave the same answer.
“I regret that it took me so long to realize I was allowed to stop.”
The last time Uncle Richard mentioned the morning he packed my belongings, he told me that my mother had stood in the doorway of my old bedroom, insisting I would come back once I calmed down.
“She really believed you’d call and apologize,” he said.
I imagined that room empty, the boxes stacked in the hallway, and my parents waiting for me to surrender.
Then I remembered the text that started everything.
We need distance from you. Please stop contacting us completely.
They had asked for distance.
I had given it to them.
I simply stopped paying for the privilege of being excluded.
And that, more than any argument or accusation, was the boundary that finally changed my life.