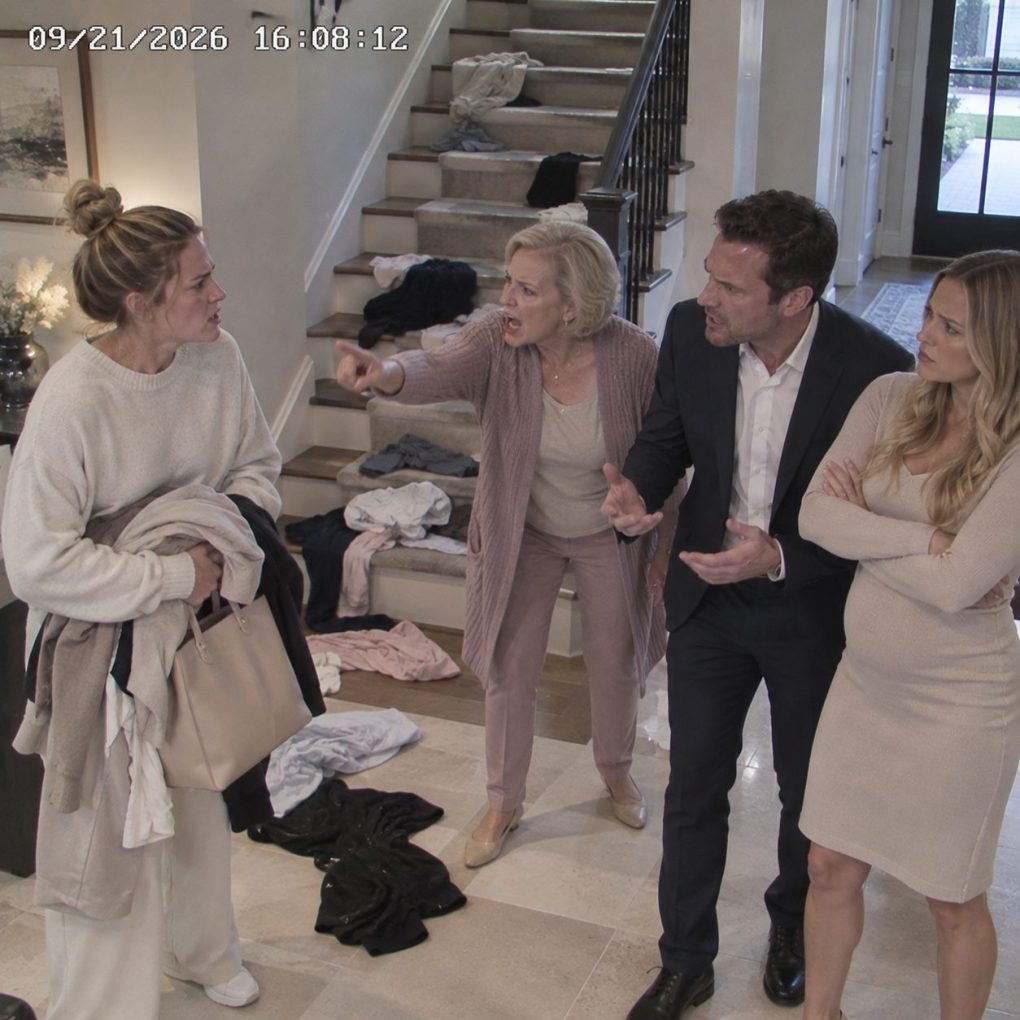
“YOUR MANICURE ISN’T MY PROBLEM!” I shouted after my sister-in-law demanded that I wash thirty dirty dishes despite the fresh burn covering my wrist. My mother-in-law slammed her hand against the dining table. “GET OUT OF MY HOUSE, YOU UNGRATEFUL WOMAN!” My husband stood silently beside her. I grabbed my purse and left. But twenty minutes later, my bank called about a $380,000 loan application secured against the house I had inherited. The application contained my signature. I had never signed anything.
My name is Jessica Miller. I’m thirty-six years old, and I work as a registered nurse in Columbus, Ohio. My husband, Brandon, and I had been married for seven years. His mother, Patricia, and younger sister, Ashley, had never particularly liked me, although I spent years trying to earn their approval.
Three years earlier, my grandmother left me a four-bedroom house worth approximately $620,000. The property was titled solely in my name. Brandon and I lived there together, but I paid the mortgage, property taxes, and most major household expenses.
Every Thanksgiving, Patricia expected me to prepare the entire family dinner. This year, twenty relatives attended. I spent two days shopping, cleaning, and cooking while Ashley sat in the living room discussing her expensive beauty treatments.
While removing a roasting pan from the oven, I accidentally burned my right wrist. The skin immediately blistered. I cooled the injury under running water, covered it with a clean dressing, and continued preparing the meal because nobody offered to help.
After dinner, Ashley pointed toward the kitchen sink. “Jessica, those dishes aren’t going to wash themselves.” I explained that my wrist was injured and asked whether she could help. Ashley held up her freshly painted nails. “Absolutely not. This manicure cost me $180.”
When I refused, Patricia exploded. She accused me of disrespecting her daughter and forgetting my place in the family. Brandon stared at the floor while his mother ordered me out.
I drove home furious and exhausted. Before I could remove my coat, a representative from my credit union called to verify a pending home-equity loan application. The caller explained that the paperwork listed my inherited property as collateral.
My stomach dropped. The representative mentioned Brandon’s name as the person coordinating the application. I immediately denied authorizing the transaction and requested that processing stop.
Then I opened my laptop and checked our shared household computer. Inside a folder labeled “Ashley’s Business,” I found scanned copies of my deed, tax statements, and identification documents.
The final file was a proposed loan agreement. It listed Ashley’s beauty salon as the intended recipient of the funds. At the bottom was a signature that looked almost exactly like mine.
I stared at the screen for several minutes, unable to believe what I was seeing. Brandon had access to our household records because we shared a computer and kept important documents in a locked cabinet. I had trusted him with the key. Now those documents appeared in a loan application I had never approved.
I immediately contacted the credit union’s fraud department. The representative confirmed that the application was under review and that no funds had been released. She instructed me to submit a written dispute, preserve the suspicious documents, and consider filing a police report.
The following morning, I met with an attorney named Rebecca Collins. She reviewed the property deed, loan paperwork, and copies of the files I had discovered. Rebecca explained that Brandon couldn’t legally mortgage property titled solely in my name without proper authorization from me.
However, she warned that the forged signature and personal information created serious risks. She advised me to preserve evidence, secure my accounts, and avoid confronting Brandon alone until we understood the full situation. I followed her instructions and changed my passwords that afternoon.
Then Rebecca noticed something unusual. The proposed loan agreement contained a business plan for Ashley’s beauty salon. The plan projected substantial revenue from a luxury spa, but the supporting financial statements showed that Ashley’s existing business had lost money for three consecutive years.
Even more troubling, the documents included a proposed transfer of $120,000 to Patricia. The payment was described as reimbursement for previous family investments. I had never heard of those investments, and Brandon had never mentioned any plan to use my inheritance to repay his mother.
That evening, Brandon called and asked why I had contacted the bank. I asked him directly whether he had submitted my property documents without permission. He hesitated before admitting that Ashley needed financing and that he had wanted to help her.
“You forged my signature?” I demanded. Brandon insisted he hadn’t personally signed anything. He claimed Ashley had arranged the paperwork through a loan broker and that Patricia believed I would eventually agree because we were family.
I asked why nobody had discussed the proposal with me. Brandon answered, “You always say no when my family needs help.” His response made everything clear. They hadn’t forgotten to ask. They had deliberately avoided asking because they expected me to refuse.
Two days later, I filed a police report and provided the relevant documents. I also placed fraud alerts on my credit files and requested additional monitoring. Rebecca contacted the credit union formally, demanding confirmation that no unauthorized lien had been recorded against my property.
Then Patricia appeared at my workplace. She confronted me near the hospital entrance, accusing me of destroying Ashley’s future. “That house belongs to the family now,” she shouted. “Brandon is your husband. What’s yours is his!” I told her that my inheritance wasn’t available to finance Ashley’s failed business.
Patricia leaned closer and whispered, “You think Brandon married you for your personality?” Before I could respond, she revealed that they had discussed the house before our wedding. According to her, Brandon had always intended to persuade me to use my inheritance to support his family.
I stood outside the hospital, staring at Patricia in disbelief. She seemed pleased that her words had hurt me. Then she demanded that I withdraw the fraud complaint before Ashley lost her financing. I told her the investigation would continue and returned to work without another word.
That evening, I called Rebecca and described the confrontation. She advised me to document Patricia’s statements while they were fresh in my memory. We also discussed separating my finances from Brandon’s and protecting the house during any potential divorce proceedings.
Three days later, Brandon arrived at our home carrying flowers. He apologized for submitting my documents but insisted his intentions had been good. He claimed Ashley had promised to repay the loan within five years and that Patricia would personally guarantee the payments.
I asked whether he understood that the house could have been lost if the loan went unpaid. Brandon looked uncomfortable. “Ashley wouldn’t let that happen,” he replied. I reminded him that her salon had been losing money for years. He had no answer.
Then I asked about Patricia’s claim that he had planned to use my inheritance before our marriage. Brandon initially denied everything. But when I mentioned the proposed $120,000 payment to his mother, he admitted that Patricia had been pressuring him for years to help Ashley expand her business.
He also confessed that he had given Ashley access to my identification documents and property records. He claimed he didn’t know she would submit a signature without my permission. Whether that explanation was true would be determined through the investigation, not by another argument in our kitchen.
I told Brandon I wanted a separation. He began crying and promised to change. For seven years, I had defended him whenever his family insulted me. Now I realized he had allowed them to treat my generosity as an obligation while secretly exposing my most valuable asset to financial risk.
Over the following weeks, investigators reviewed the loan application and interviewed the people involved. The credit union confirmed that no loan had been funded and no lien had been recorded. Ashley’s loan broker provided correspondence showing that she had submitted the disputed signature as part of the application.
Ashley eventually admitted through her attorney that she had copied my signature from an older document. She claimed she believed Brandon had permission to arrange the financing. The authorities continued evaluating the evidence, and I refused to speculate about what criminal charges might follow.
Meanwhile, Rebecca helped me begin divorce proceedings and address the legal questions surrounding my inherited property. Brandon moved into Patricia’s house. I changed the locks after he voluntarily surrendered possession and my attorney confirmed the appropriate steps.
Six months later, I hosted Thanksgiving dinner at my own house. Only eight people attended: close friends, two coworkers, and my cousin’s family. Everyone helped prepare the meal, and nobody complained about washing dishes. My wrist had healed, although a faint scar remained.
As we cleared the table together, I remembered Patricia ordering me out because Ashley refused to ruin her manicure. That humiliation had exposed a much larger betrayal. My husband and his family had mistaken my patience for weakness and my inheritance for their personal bank account. I had spent years trying to become someone they would accept. Now I understood that protecting my peace, my home, and my future mattered far more than earning the approval of people who only valued what they could take from me.