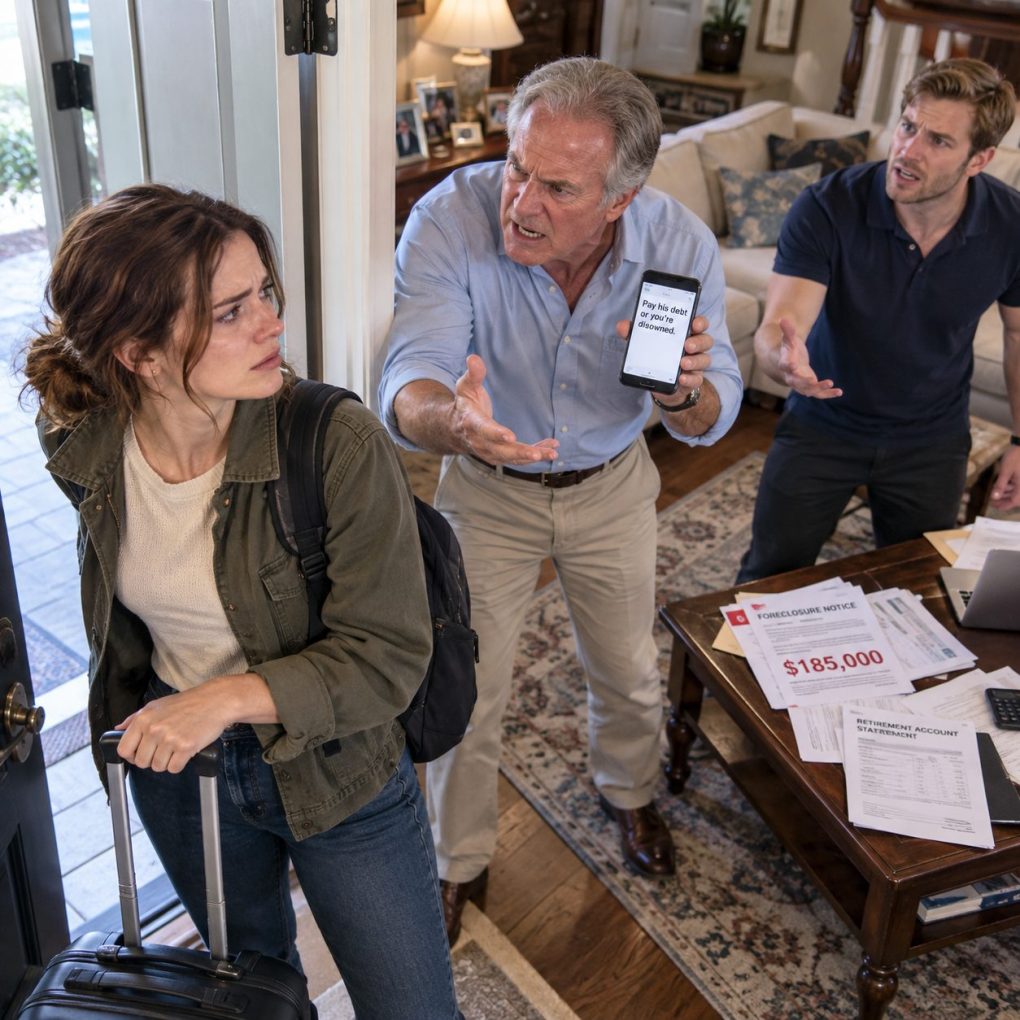
My brother demanded $185,000 from my retirement savings to save his house, and when I refused, my father gave me an ultimatum that ended our family as I knew it.
“Pay your brother’s debt, or you’re disowned,” Dad texted me that evening.
I stared at the message in my apartment in Denver, Colorado, wondering how a family could turn thirty-four years of love into a bill I was expected to pay. Then I booked a one-way flight, opened my banking app, and made a decision that would leave my parents and brother scrambling before midnight.
My name is Emily Carter, and I had spent fifteen years building a life that didn’t depend on anyone else. I worked as a hospital administrator, contributed consistently to my retirement accounts, and lived modestly because I wanted the freedom to retire comfortably instead of spending my later years worrying about money.
My older brother, Ryan, had always lived differently.
He was charming, persuasive, and convinced that every setback was temporary because someone in our family would eventually help him recover. When he bought an expensive house outside Dallas, Dad proudly called him the family’s future success story, even though Ryan had already borrowed money from our parents twice to cover business expenses.
I never judged him for struggling, but I had grown tired of watching every financial mistake become someone else’s responsibility.
The crisis began on a Tuesday afternoon when Ryan called me, barely allowing me to say hello before launching into an explanation about his mortgage, an adjustable-rate loan, and a business investment that had collapsed. He claimed he was behind on payments and facing foreclosure unless he could come up with $185,000 quickly.
“I need you to transfer the money from your retirement account,” he said. “It’s just a temporary loan, Em. I’ll pay you back when I sell the company.”
I asked him for his repayment plan, the lender’s notice, and the actual deadline, but he reacted as though my questions were a personal betrayal.
“You have more money than you need sitting around,” he snapped. “I’m your brother. What exactly are you saving it for if you won’t help your own family?”
I reminded him that retirement savings weren’t spare cash and that withdrawing money early could trigger taxes, penalties, and long-term financial damage. I also offered to help him contact his lender, consult a housing counselor, and review legitimate options for avoiding foreclosure.
He rejected every suggestion.
“I don’t need a lecture. I need the money.”
That evening, Dad called and explained that Ryan had already spoken to him about my savings. Apparently, my brother had presented the situation as though I were the only person capable of saving the family home, conveniently leaving out the years of financial assistance he had already received.
Dad didn’t ask whether I could afford to lose $185,000 or whether Ryan had exhausted every alternative.
He simply told me that family came first.
When I refused, his voice hardened.
“Your brother is about to lose everything, and you’re sitting there protecting a retirement account. Your mother and I didn’t raise you to be this selfish.”
I ended the call shaking with anger, but I still hoped my father would reconsider once he had calmed down.
Instead, his text arrived twenty minutes later.
Pay his debt or you’re disowned.
I read it repeatedly, waiting for another message that might explain he had been angry and didn’t mean it. Nothing came, and when I called my mother, she cried quietly before telling me that I should do what Dad wanted because the family couldn’t survive another argument.
That was when I understood that nobody was asking me to help Ryan make a responsible decision.
They were demanding that I sacrifice my future so he wouldn’t have to face the consequences of his past.
I booked a one-way flight to Seattle, where an old college friend had offered me a place to stay while I looked for a new beginning. Then I reviewed my finances and discovered something I hadn’t considered during the earlier calls: Ryan and Dad weren’t just expecting money from my retirement account.
They also had access to a joint savings account I had opened with my parents years earlier to help manage emergency family expenses.
The account held nearly $72,000, most of it money I had deposited over time, although some funds belonged to my parents. I had never worried about the arrangement because we’d agreed that withdrawals required everyone’s consent.
Now I wondered whether they had already decided to use that money without asking me.
At 11:43 p.m., my phone lit up with another message from Dad.
“Ryan’s lender needs confirmation by tomorrow morning. Transfer the money tonight, or don’t ever call yourself my daughter again.”
I opened the joint account, checked the ownership records, and called the bank’s emergency support line to understand my legal rights and prevent any unauthorized withdrawal.
Then I saw a pending transfer request I hadn’t approved.
The recipient was Ryan.
And the amount was $72,000.
I barely slept that night, sitting at my kitchen table with my laptop open and the bank representative’s instructions beside me. The pending transfer had not been completed, but it had been submitted through the joint account’s online access, and the bank confirmed that I needed to act quickly if I believed the transaction was unauthorized.
I explained that I had not consented to the transfer and asked the bank to review the request under its security procedures. Because the account had multiple owners, the representative couldn’t simply declare the money mine or freeze every transaction indefinitely, but the bank placed a temporary review on the disputed payment while verifying the authorization.
That gave me time to examine the account history.
I discovered that the $72,000 balance included approximately $48,000 I had contributed over several years, $14,000 deposited by my parents, and another $10,000 whose source required further review. The account agreement identified all three of us as joint owners, which meant I couldn’t honestly treat the entire balance as exclusively mine just because I had deposited the largest share.
I needed to protect myself without taking money that belonged to someone else.
I contacted an attorney before making any major financial move, explaining the ownership structure and Dad’s threat. She advised me to preserve the messages, obtain the account documents, and separate my individual funds from the joint account wherever legally permitted, while avoiding any transaction that could improperly deprive the other owners of their rights.
The next morning, I transferred my own accessible checking and savings funds into a new individual account after confirming that they were solely mine. I also changed passwords on my personal financial accounts, enabled additional security measures, and instructed my retirement provider not to process any withdrawal without my direct authorization.
I did not cash out my retirement account.
That money had taken fifteen years to build, and I wasn’t going to destroy my financial future simply because my family had decided Ryan’s mortgage mattered more.
At 7:15 a.m., Ryan called.
“You can’t just disappear when the house is about to be taken away,” he shouted. “Dad says you have the money, and I already told the lender we’d have it.”
I asked why he had submitted a transfer request from the joint account without discussing it with me.
There was a long silence.
“Dad said it was fine,” he finally replied. “It’s a family account, Emily. You don’t get to act like every dollar belongs to you.”
“Then why didn’t you ask me?”
He hung up.
An hour later, Dad called and accused me of making the situation worse. He claimed Ryan’s lender had given him until the end of the day to provide funds, but when I asked to see the notice, he refused to send it.
Instead, he repeated his ultimatum.
“If you let your brother lose that house, you’re choosing money over your family.”
I looked at the packed suitcase beside my door and realized I had spent years trying to earn approval from people who considered my boundaries an insult.
“No, Dad,” I said. “I’m choosing not to finance another decision Ryan refuses to take responsibility for.”
Then I ended the call.
By noon, I was on a plane to Seattle, leaving behind my apartment, the family gatherings I had organized for years, and the assumption that love meant always being available when someone needed money.
My friend Megan met me at the airport and let me stay in her spare room while I searched for a short-term rental. For the first time in years, I could make plans without calculating how much of my paycheck might eventually be demanded by my family.
But the conflict followed me.
Dad sent messages accusing me of abandoning my mother, while Ryan claimed that my refusal had destroyed his chance to save the house. Neither mentioned that he had ignored my offer to help negotiate with his lender or that he had attempted to move money from the joint account without my permission.
Two days later, my attorney obtained further information about the account and helped me arrange a documented division of the funds with my parents, subject to the account agreement and the bank’s review. The undisputed portion belonging to me was transferred to my individual account, while my parents’ contribution and the unresolved amount remained protected until the ownership question was settled.
I wasn’t going to drain money that wasn’t mine.
But I was no longer willing to let anyone use shared finances as a weapon against me.
Then Megan brought me a cup of coffee and asked the question I had been avoiding.
“What happens if Ryan loses the house?”
I looked out at the gray Seattle sky.
“He’ll have to deal with what happens next,” I answered. “For once, I won’t be the person who saves him from it.”
That afternoon, I received an email from Ryan’s lender, forwarded by my father, demanding payment and warning that foreclosure proceedings could continue if the delinquency wasn’t resolved.
The deadline was real.
So was the debt.
But for the first time, I understood that the existence of a crisis didn’t automatically make me responsible for solving it.
Over the following weeks, Ryan’s situation became more complicated because his business had not recovered as he had promised. His mortgage arrears, legal expenses, and other obligations had accumulated beyond what he could comfortably manage, and selling the company was no longer a reliable way to repay a $185,000 family loan.
He eventually hired a financial adviser and contacted his lender to discuss possible options, including a repayment arrangement and a sale of the property. Neither solution was painless, but they gave him a chance to address the problem without demanding that someone else surrender their retirement savings.
The house ultimately went on the market.
Ryan was furious when the sale became unavoidable, but the proceeds helped satisfy a substantial portion of the mortgage, and he moved into a smaller rental while reorganizing his finances. He still faced debts and difficult decisions, yet the outcome was far less catastrophic than the story he had used to pressure me into handing over my retirement account.
Dad refused to acknowledge any of this.
For weeks, he sent messages telling me I had humiliated the family and abandoned my brother when he needed me most. My mother occasionally called, crying that she missed me, but each conversation eventually returned to the same request: couldn’t I reconsider and help Ryan just this once?
I told her I loved her, but I would no longer discuss giving Ryan money.
Eventually, I stopped answering calls that began with accusations or ended with financial demands.
Meanwhile, the bank completed its review of the joint account. The disputed $72,000 transfer had been stopped before the funds reached Ryan, and the account was divided according to the ownership records and the agreement reached with legal assistance.
I recovered the portion confirmed as mine, while my parents retained their contribution and the unresolved amount was settled separately. I never drained money belonging to them, despite Dad later telling relatives that I had emptied the family’s accounts and left them with nothing.
The truth was less dramatic, but it was documented.
I had protected my own money, prevented an unauthorized transfer, and refused to pay a debt that wasn’t mine.
Three months after moving to Seattle, I found a small apartment near a park and accepted a new position in hospital administration. The salary was comparable to what I had earned in Denver, and the move gave me the chance to build a life that wasn’t organized around anticipating my family’s next emergency.
I began hiking on weekends, joined a local book club, and started saving toward a home of my own. Ordinary decisions felt strangely liberating when I no longer had to wonder whether someone would demand that I abandon them to rescue Ryan.
Eventually, my mother sent me a letter.
She admitted that she had supported Dad’s ultimatum because she feared what would happen if Ryan lost his house and the family appeared unsuccessful. She also confessed that she had known about his previous financial problems but had convinced herself that each rescue was temporary.
“I thought keeping everyone together meant keeping everyone happy,” she wrote. “I didn’t understand that we were asking you to pay for that happiness.”
Her apology didn’t erase the hurt, but it was the first time anyone in my family had acknowledged what had happened without immediately asking me for something.
I replied that I loved her and was willing to rebuild our relationship slowly, provided our conversations no longer revolved around Ryan’s finances. We began speaking occasionally, and although things remained strained with Dad, I left the door open for a relationship that could eventually become healthier.
Ryan contacted me nearly a year later.
He apologized for submitting the transfer request without my consent and admitted that he had expected me to rescue him because I had done so in smaller ways throughout our lives. He was working again, living within a tighter budget, and slowly paying down the obligations he could no longer ignore.
“I thought family meant you would always say yes,” he told me during our call. “I didn’t realize how much I was asking you to give up.”
I accepted his apology, but I didn’t offer him money.
Forgiveness wasn’t a financial agreement, and rebuilding trust required more than a sincere conversation.
Dad eventually sent one final message acknowledging that he had gone too far when he threatened to disown me. We began exchanging occasional updates, although I made it clear that any future relationship would depend on mutual respect rather than financial pressure.
I never regretted leaving Denver.
My retirement savings remained intact, my finances were secure, and I had learned that helping someone should be a choice made freely, not a payment demanded under threat of losing a family.
Ryan had to sell his house, but he survived the consequences of his decisions and began rebuilding his life. My parents had to confront the fact that their attempts to protect him had damaged their relationship with me, and I finally stopped believing that keeping everyone happy was my responsibility.
The money I protected was important.
The boundary I established mattered even more.
When Dad told me to pay Ryan’s debt or consider myself disowned, he expected fear to bring me back into line. Instead, his ultimatum forced me to recognize that a family relationship built on threats and financial demands wasn’t something I could preserve by sacrificing everything I had worked for.
I didn’t leave because I stopped loving my family.
I left because I finally understood that loving them didn’t require abandoning myself.