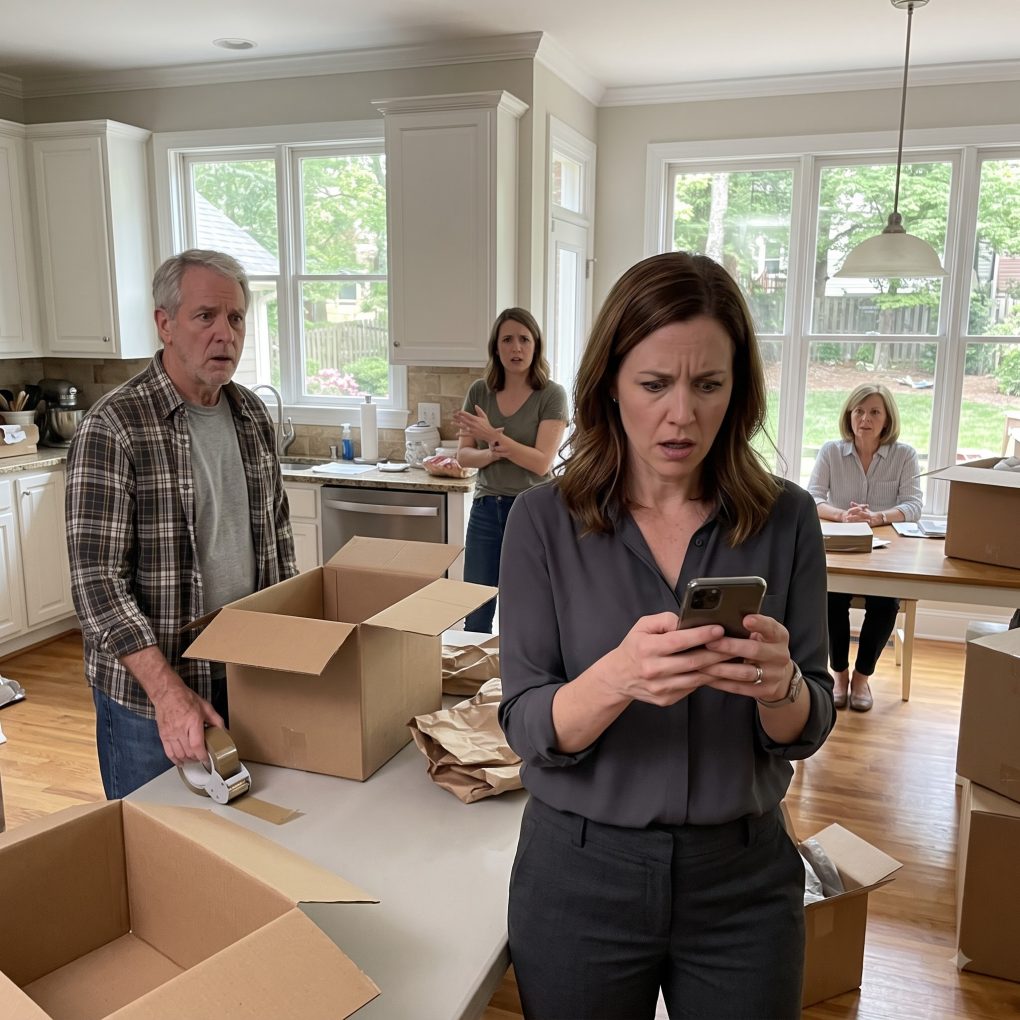
The night I lost my job, my sister didn’t ask if I was okay.
She slammed her wineglass onto our parents’ kitchen counter and shouted, “Who’s going to pay my car loan now?”
I had been unemployed for exactly forty-three minutes.
My company had eliminated my finance position during a merger, and I had driven straight to my parents’ house in Raleigh because Mom said dinner was waiting. I was thirty-seven, recently divorced, and staying in their guest room while my condo renovation finished.
I thought I was walking into comfort.
Instead, Brooke stared at me like I had personally repossessed her Subaru.
“Your payment isn’t due for two weeks,” I said.
“That’s not the point.”
Mom stepped beside her. “Emily, your sister has two kids. She needs stability.”
“So do I.”
“You have savings.”
I almost laughed.
They knew I had savings because they had been spending around them for years.
I paid Brooke’s $612 monthly car payment after her divorce. I covered Mom’s dental work. I paid the property taxes twice when Dad’s contracting income came up short. Nobody called those things loans.
Dad came in carrying two empty cardboard boxes.
“What are those for?”
“Your things.”
The room went still.
He set the boxes beside the stairs. “Brooke’s landlord is raising her rent. She and the kids need this house more than you do.”
Brooke folded her arms.
Mom added, “You can stay at a hotel for a while.”
I stared at them.
This house had four bedrooms.
Brooke did not need my guest room. They had simply decided the daughter without children was easiest to displace.
I could have argued.
I could have reminded Dad who covered the mortgage during his surgery. I could have told Brooke her car payment came from my checking account, not some invisible family fund.
I said none of it.
Then Dad made his mistake.
“Besides,” he said, “the business is finally about to turn around. Once the Wilmington deal closes, everybody will be fine.”
My stomach tightened.
“What Wilmington deal?”
His face changed.
Brooke jumped in. “Dad means the beach place.”
“The beach house?”
Mom looked annoyed. “Emily, not tonight.”
That was when I understood they had been planning something without me.
The beach house in Carolina Beach had belonged to my grandmother. When she died, she left it directly to me. Not Mom. Not Dad. Me.
And the company Dad called “the business” was Harbor Ridge Renovations LLC.
It was also mine.
Five years earlier, when Dad wanted to retire, I bought every membership interest and kept him on as operations manager because he hated the idea of quitting.
Apparently, my family had decided ownership was just paperwork.
My phone buzzed.
A Wilmington number.
I answered.
“Ms. Carter?” a man said. “This is Daniel Price with Atlantic Coast Title. I need to confirm tomorrow’s closing on your Carolina Beach property.”
I looked directly at my father.
He dropped the packing tape.
I thought losing my job was the worst thing that had happened that night. Then one phone call revealed what my family had already tried to sell without telling me.
Dad bent to pick up the tape, but his hand shook.
“Emily,” he said, “let me explain.”
I put the call on speaker.
Daniel Price continued, “We received a purchase contract listing Robert Carter as authorized representative for the owner. Our title search shows you are the sole owner, so we cannot close without your signature and identification.”
“What purchase price?” I asked.
“One million eighty thousand.”
Brooke gasped.
Mom whispered, “Robert.”
Dad snapped, “Hang up the phone.”
I didn’t.
“Mr. Price, I did not authorize a sale. Please cancel tomorrow’s closing and send every document you received to my attorney.”
There was a pause.
“Understood.”
When the call ended, Dad started talking fast.
The company had lost two major projects. A commercial client had delayed payment. Harbor Ridge owed vendors, payroll taxes, and nearly ninety thousand dollars on its credit line.
“So you tried to sell my house?” I asked.
“It was supposed to fix everything.”
“My beach house.”
“Your grandmother bought that place for the family.”
“She left it to me.”
Mom stepped forward. “Because she trusted you to do the right thing.”
The sentence almost impressed me.
“The right thing for whom?”
Brooke started crying. She said Dad had promised that once the beach house sold, he would put $40,000 toward a down payment for her and pay off her Subaru.
That explained the car loan.
It also explained why losing my salary had frightened her before it frightened me.
Dad insisted the sale was only one piece of the plan.
“What other piece?”
Nobody answered.
Then I remembered a bank email from the previous week asking me to schedule a signing for an amended Harbor Ridge credit facility. Dad had told me it was routine renewal paperwork.
I opened the email.
The proposed line had been increased from $150,000 to $600,000.
Personal guarantor: Emily Carter.
Collateral: all company assets and proceeds from the Carolina Beach property.
I felt cold all over.
“You pledged a house you don’t own to support a company you don’t own, and you expected me to sign the guarantee tomorrow?”
Dad raised his voice. “I built Harbor Ridge!”
“You sold it to me.”
“On paper!”
“No. For $310,000.”
The room went silent.
Five years earlier, Dad had been exhausted and ready to walk away. I had used savings and a small-business acquisition loan to buy the company. The attorney drafted the transfer. Taxes were filed. Dad was paid. He later changed his mind about retirement, and I let him stay.
Apparently, he had rewritten the story in his head.
My phone buzzed again.
This time it was Harbor Ridge’s outside accountant.
Emily, call me immediately. Robert tried to authorize a $74,000 owner distribution this afternoon. Bank rejected it because you are the only member.
I showed Dad the message.
Mom sat down.
Brooke said, “What does that mean?”
“It means,” I said, “Dad tried to take seventy-four thousand dollars out of my company hours before throwing me out of this house.”
Dad’s anger disappeared.
He looked frightened now.
Then the accountant called again.
I answered.
“Emily,” he said, “there’s more. You need to check the company cards. Tonight.”
The company-card statements were worse than I expected.
Dad had charged nearly $31,000 in personal expenses over eight months: repairs to my parents’ house, a family vacation, restaurant bills, and deposits connected to Brooke’s planned move. Some charges had been labeled as project costs.
My accountant, Marcus, had questioned them twice.
Dad told him I had approved everything.
I hadn’t.
At 10:17 that night, I called Harbor Ridge’s bank and removed Dad’s transaction authority pending an audit. I froze the employee cards, not the operating account, so payroll and legitimate vendor payments could continue. Then I emailed our attorney and terminated Dad as operations manager effective immediately.
I did not shut down the company.
I protected it.
By midnight, the structure my family had built around my silence collapsed.
The beach-house buyer withdrew after the title company confirmed Dad had no authority to sell. The bank suspended the expanded credit request because the proposed collateral was unavailable and I refused the personal guarantee. The $74,000 distribution never moved. Brooke’s promised down payment disappeared with it.
Then I opened my banking app.
Her Subaru payment was still scheduled from my personal account.
I canceled the recurring transfer.
Brooke stared at my screen. “You’re really going to do that?”
“You asked who would pay your car loan now.”
Her face flushed.
“The answer is you.”
Mom called me cruel.
I picked up one of the boxes Dad had brought downstairs and started packing my laptop, clothes, and toiletries.
“Where are you going?” she asked.
“To my beach house.”
Dad looked up sharply.
For years, I had barely used it because every visit became a family event. That night, for the first time, I understood why Grandma had left it directly to me.
She had wanted me to have somewhere that was mine.
The next morning, Marcus and I spent six hours reviewing Harbor Ridge’s books. The business was strained, but it was not doomed. Without the unauthorized personal spending and with two unprofitable projects closed out, it could survive.
I hired an experienced project manager, negotiated payment plans with two vendors, and reported the questionable charges to the company’s attorney and accountant for proper treatment.
Dad returned his keys.
For weeks, he barely spoke to me.
Brooke sold the Subaru three months later and bought an older Honda she could afford. Mom stopped calling me until Christmas, when she finally said, “We thought because you always helped, you always would.”
“That was the problem,” I said.
Losing my corporate job turned out not to be the disaster everyone predicted. I received severance, finished the renovation on my condo, and spent that winter working from the Carolina Beach house while managing Harbor Ridge more closely.
Six months later, I accepted another finance position.
But something more important had already changed.
My family had mistaken generosity for obligation, paperwork for permission, and silence for agreement.
The night Dad packed my things, he believed he was removing the person who needed the house least.
He had no idea he was pushing out the person holding together the car payment, the company, and the beach-house deal.
I lost my job that night.
They lost access to a life they had quietly built on my name.