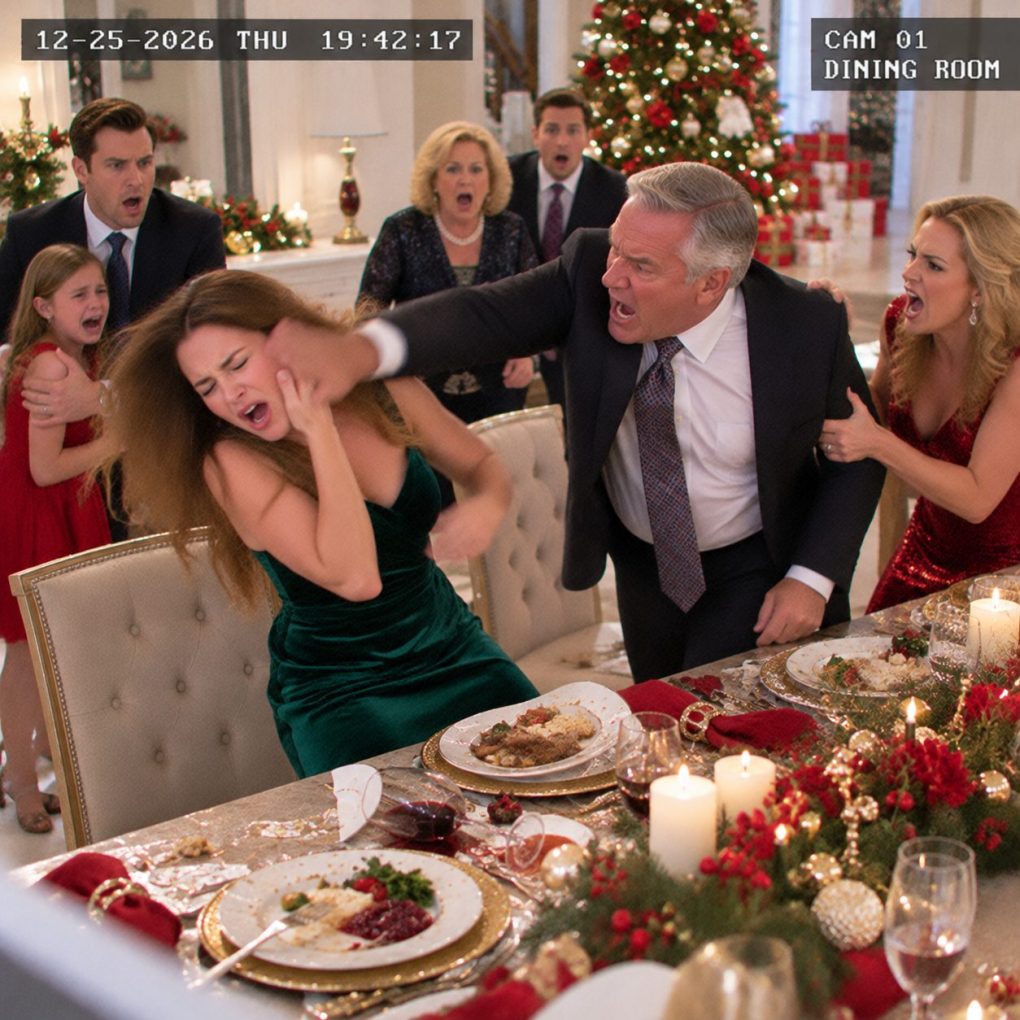
The third slap was the one that made my twelve-year-old daughter start crying.
Not because it was harder than the first two.
Because my father looked proud afterward.
We were halfway through Thanksgiving dinner at my parents’ home outside Pittsburgh when my sister, Vanessa, looked across the table at my daughter Sophie and said, “Hopefully you grow up more ambitious than your mother.”
Sophie went quiet.
I did not.
“Leave my daughter out of this.”
Vanessa smiled.
“Oh, relax. I’m trying to motivate her.”
Vanessa was the family success story—or at least the one my parents enjoyed advertising.
Corporate attorney.
Luxury SUV.
Country-club membership.
Photographs from expensive vacations.
I owned a bookkeeping and payroll company with thirty-two employees, but because I drove a seven-year-old Honda and avoided discussing money, Dad described my work as “doing taxes for people.”
That misconception had been convenient.
For everyone except me.
Vanessa looked at Sophie again.
“Your mom could have done something impressive if she hadn’t settled.”
I put down my fork.
“That’s enough.”
Dad slammed his palm against the table.
“Do not speak to your sister like that.”
“She insulted my child.”
“She told the truth.”
I stood.
“We’re leaving.”
Dad came around the table before I reached Sophie.
Then he slapped me.
Once.
My ears rang.
“Dad—”
Twice.
Mom gasped but remained seated.
The third landed across my cheek while Sophie screamed, “Stop!”
Dad pointed toward me.
“You’re trash! Your sister is successful. You’re just a parasite!”
The entire room went silent.
A parasite.
I looked around the dining room.
The new chandelier.
The refinished floors.
The kitchen renovation completed the previous spring.
Then I looked at my father.
For seven years, he had believed the house remained affordable because his retirement planning was excellent.
It wasn’t.
After Dad’s manufacturing job disappeared and Mom’s medical expenses increased, they nearly lost the property.
I quietly stepped in.
The mortgage was refinanced through a bank where my company kept its business accounts. I guaranteed the restructuring, then began making the monthly payments myself.
$3,460 every month.
I also paid the property taxes twice a year.
Homeowners insurance.
Utilities when Dad fell behind.
Even the renovation he proudly told everyone Vanessa had “helped arrange.”
She arranged the contractor.
I paid the invoice.
Nobody at that table knew the full amount except me.
Dad smiled as though striking me had finally put me back in my place.
So I took out my phone.
Mom frowned.
“What are you doing?”
I called my banker.
“David? It’s Claire Morgan.”
Dad laughed.
“Calling somebody to complain?”
I ignored him.
“Stop every automatic payment originating from my personal support account.”
The room changed.
Dad’s smile weakened.
“What payments?”
“All of them,” I said.
David asked me to confirm whether that included recurring housing expenses.
“Yes.”
Dad stared at me now.
I looked directly into his eyes.
“Start with this house.”
Mom dropped her fork.
Vanessa whispered, “What does she mean?”
But David had one more question.
“Claire, should I also cancel the scheduled transfer covering the mortgage balloon due next month?”
Dad’s face went white.
I had forgotten the balloon payment was already scheduled.
$186,400.
And without it, the bank—not me—would soon be asking my parents what they intended to do about the house.
I did not cancel the balloon payment while standing at the table. I told David to pause it pending review, because anger was a terrible reason to make a six-figure financial decision. Then I took Sophie’s coat, photographed the swelling on my face, and left before Dad could turn another argument into another assault.
At urgent care, a physician documented the redness, swelling, and tenderness along my cheek. Those records established that I had been injured; Sophie and several dinner guests had witnessed how. I gave a statement to police that evening and let them decide what followed instead of using money as my substitute for accountability.
The next morning, attorney Rebecca Sloan reviewed the mortgage documents with me. My parents still owned the house. I did not. Seven years earlier, after their financial problems, I had guaranteed a refinance and voluntarily paid the installments from an account in my name. Stopping future payments did not magically evict them, transfer title to me, or erase their obligations to the lender.
The $186,400 balloon was due because the refinance had been structured with lower monthly payments and a final lump sum. I had planned to pay it as an early Christmas surprise, then release myself from the guarantee after the lender completed its paperwork. Dad apparently believed the mortgage was simply “almost paid off” through his own retirement income.
When Rebecca reconstructed seven years of support, even I was shocked. Mortgage payments, taxes, insurance, repairs, utilities, Mom’s medical expenses, and several household projects totaled more than $430,000. None of those payments gave me ownership rights unless the documents said so. They did, however, destroy Dad’s claim that I had spent adulthood living off the family.
Vanessa called before noon. “You cannot take Mom and Dad’s house away because Dad lost his temper.” I answered, “I’m not taking anything. I’m stopping voluntary payments from my account.” She said they could not afford the balloon. I asked whether the successful daughter planned to help. Silence followed.
That silence had a history. Vanessa gave expensive visible gifts—weekend trips, restaurant dinners, designer handbags for Mom. I handled invisible expenses. Property taxes do not photograph well. Insurance premiums rarely produce applause. Because I never announced what I paid, my family gradually decided I contributed almost nothing.
Dad called two days later. He did not apologize. He said, “You created this situation by keeping the finances secret.” I reminded him that he had received every mortgage statement at his address and knew I had stepped in years earlier. He knew enough to accept help. He had simply stopped asking where the money came from.
The lender offered several legitimate options: Dad and Mom could refinance the balloon if they qualified, sell the property, use retirement assets, or obtain help from someone else. Rebecca made certain everyone understood I would honor any legal obligation I personally had under the guarantee, but I would no longer volunteer additional funds without written agreements.
Then Vanessa proposed a solution. She wanted me to pay the $186,400 anyway and have our parents deed half the house to her because she would supposedly “take responsibility going forward.” I laughed for the first time in days. “With whose money?” She answered, “You can afford the payment. I’ll manage the property.”
There it was again: my money, her authority.
Then Rebecca found something that made even Vanessa stop arguing. Six months earlier, Dad had signed a home-equity application claiming the mortgage balloon would be satisfied by “daughter Vanessa Morgan.” Attached was a financial statement showing an annual income far higher than Vanessa actually earned.
When Rebecca asked where those numbers came from, I recognized them immediately.
They were mine.
The home-equity loan had never closed, which mattered. The lender had requested additional proof of Vanessa’s income and the application stalled. Still, someone had taken figures from my business tax information and placed them beside my sister’s name as though her finances could support the house after the balloon payment.
Rebecca advised me not to accuse Vanessa of creating the application without evidence. The lender preserved the file, submission logs, emails, and identification records. Dad had signed the application as property owner. Vanessa’s name appeared as the proposed supporting borrower, but investigators still needed to determine what she personally knew.
Vanessa eventually admitted Dad asked for copies of her identification and told her he was “restructuring the house.” She denied providing the income figures and produced messages showing she had questioned why the lender wanted documents from her. Dad replied, Don’t worry about the details. Claire’s money keeps everything safe anyway.
That sentence ended the illusion more effectively than anything I could have said. Dad had publicly called me a parasite while privately treating my income as the invisible foundation beneath his house. He resented my success precisely because he had become dependent on it and did not want anyone—including himself—to admit that.
The assault case resolved separately. Dad accepted responsibility for striking me and received court-ordered conditions including counseling and restrictions on contact while the case was active. I did not ask for some theatrical punishment. I wanted what happened at Thanksgiving recorded accurately instead of reduced to “a family argument that got heated.”
My parents ultimately sold the house. Not because I seized it, but because refinancing the balloon on their income was impractical and they chose not to drain retirement savings. The sale produced enough equity for them to purchase a smaller condominium with a manageable monthly cost. For the first time in years, their housing did not depend on me.
Vanessa helped them move. So did I—but only after Dad was no longer present because our contact remained limited. I paid nothing toward the new condominium. Mom initially found that frightening. Six months later, she admitted it was healthier to know exactly what they could afford without waiting for one daughter to quietly cover the difference.
Vanessa apologized to Sophie before she apologized to me. She told her, “What I said at dinner was cruel, and being successful doesn’t mean having an impressive job or expensive things.” Sophie answered, “I already knew that.” I had to turn away so nobody saw me smile.
My relationship with Dad took much longer. His first apologies blamed stress, alcohol, fear about retirement, and my tone during the argument. I rejected every version. Nearly a year later he finally said, “I hit you because I expected you to take it the same way I expected you to pay for everything—quietly.” That was the first apology that contained the truth.
I never restarted the old automatic payments. Instead, when Mom genuinely needed help with one medical expense later, she asked. I chose to contribute. The difference between those two arrangements was enormous: generosity returned to being a decision rather than a family tax placed on the person everyone considered strongest.
That Thanksgiving, Dad called me trash while sitting inside a house my money had helped preserve for seven years. He believed wealth looked like Vanessa’s car, title, clothes, and vacations, so he never noticed the daughter financing the things nobody applauded. When I stopped the automatic payments, I did not destroy my family. I simply removed the financial machinery that had allowed them to mistake my silence for dependence. And once the payments stopped, everyone finally saw who had been carrying whom.