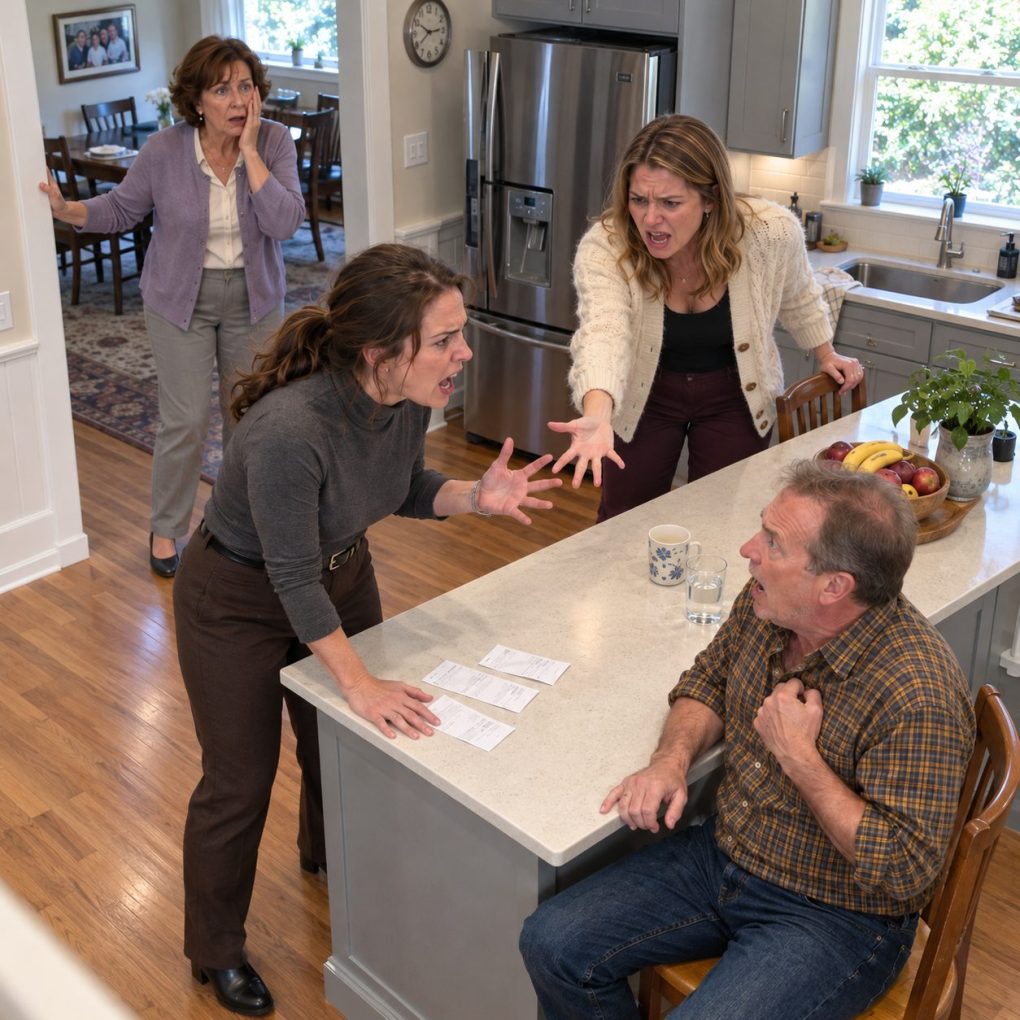
“Return the fifty thousand dollars or don’t come back!” Dad shouted, pointing toward the front door. My younger sister, Melissa, folded her arms and sneered. “You stole Mom’s money, Rachel. We all know it.” I slowly placed three bank teller receipts on the kitchen counter, and their expressions changed instantly.
My name is Rachel Morgan. I’m thirty-nine, and I live in Columbus, Ohio. Three weeks earlier, my mother had undergone emergency heart surgery, leaving my father and sister responsible for managing the household while she recovered. Somehow, fifty thousand dollars had disappeared from her savings account.
Dad claimed the bank had told him I was responsible. Melissa insisted she’d seen me withdrawing money while Mom was hospitalized. Neither would explain why they hadn’t contacted me before accusing me of theft in front of several relatives gathered for Sunday dinner.
I asked Dad whether he’d actually examined the transaction records. He slammed his palm against the counter and demanded a confession. Melissa smiled triumphantly, apparently convinced that my silence meant guilt. Instead, I unfolded the receipts I’d obtained from Mom’s banking records with her written authorization.
The first receipt showed a $20,000 cashier’s check purchased by my father. The second documented a $15,000 withdrawal made in person by Melissa. The third showed another $15,000 cashier’s check issued to a home-renovation contractor connected to Melissa’s property.
Dad grabbed the receipts and went pale. Melissa immediately claimed the transactions were ordinary family expenses. I asked why Mom’s savings had paid for renovations at Melissa’s house while Mom was struggling with medical bills. Nobody answered. Even the relatives stopped whispering.
The records didn’t prove every detail of what had happened, but they destroyed the accusation against me. My name appeared nowhere as the withdrawing customer or check purchaser. Mom had specifically asked me to investigate after discovering that her account balance was dramatically lower than expected.
Dad finally admitted he’d purchased the first cashier’s check. He said Melissa needed help covering an overdue business loan. Melissa interrupted, insisting Mom had verbally approved everything. I asked whether they had any written authorization. Dad looked toward the floor, and Melissa’s confident expression disappeared.
Then I revealed the most troubling detail. Mom had been under anesthesia when the final $15,000 cashier’s check was purchased. The bank’s transaction record identified Dad as the purchaser, and the contractor confirmed he’d received the payment for Melissa’s kitchen renovation.
Melissa lunged toward the receipts, but I pulled them away. “You accused me of stealing money you spent yourselves,” I said. Dad demanded that we keep the matter private until Mom recovered. I shook my head. “She’s already asking questions,” I replied. “And tomorrow, we’re meeting her attorney.”
The following morning, I drove Mom to an appointment with attorney Helen Brooks. Her surgeon had cleared her for short outings, although she still tired easily. Mom carried a notebook containing every question she wanted answered. She hadn’t slept much since discovering the missing money.
Helen reviewed the bank records, account agreement, and copies of the cashier’s checks. Dad was a joint owner of the savings account, which meant the bank could generally honor his withdrawals. That didn’t establish whether he’d respected Mom’s wishes or whether Melissa had obtained money through deception.
Melissa’s $15,000 withdrawal was particularly troubling. She’d been an authorized signer on a separate household account, but not on Mom’s savings account. The bank’s identification records showed that she had accompanied Dad during the transaction. Dad had signed the withdrawal slip, and Melissa had received the cash.
That distinction mattered because Melissa had repeatedly claimed she’d withdrawn the money herself. Helen explained that the paperwork showed Dad authorized the transaction, not that Melissa had independent access. Mom listened carefully before asking the question everyone else had avoided: “Why did they need my money without telling me?”
I showed Mom messages Melissa had sent Dad during her hospitalization. They discussed a business loan payment, renovation costs, and the need to complete everything before Mom returned home. Dad had forwarded the messages to our family group accidentally, then deleted them. I’d preserved screenshots before they disappeared.
Mom’s hands trembled as she read the conversation. She had worked thirty years as a public-school administrator and considered those savings her emergency fund. Dad had his own retirement account and regular pension income. She’d never agreed to finance Melissa’s struggling business or expensive kitchen renovation.
Helen recommended obtaining a complete accounting and sending formal preservation requests for relevant records. She also advised Mom to discuss account protections with the bank. Because Dad remained a joint owner, Mom needed professional guidance before changing arrangements or transferring funds. She wanted every decision documented.
That afternoon, Mom called Dad with Helen present. She asked him directly whether he’d authorized the three transactions. After several uncomfortable seconds, he admitted that he had. He claimed he’d intended to replace the money once Melissa sold an investment property. Mom asked why he’d accused me instead.
Dad said Melissa had suggested that blaming me would prevent Mom from becoming upset during recovery. I heard Mom take a sharp breath. She’d spent years defending Melissa’s poor financial decisions, but this time her disappointment sounded different. She told Dad not to contact her until he was prepared to explain everything honestly.
Two days later, Melissa arrived at my apartment without warning. She demanded that I convince Mom to drop the matter, claiming a legal dispute would destroy the family. When I refused, she threatened to tell everyone I’d manipulated Mom while she was vulnerable. I closed the door and immediately called Helen.
Helen sent Dad and Melissa a formal demand for an accounting and repayment proposal. The letter described the documented transactions without making unsupported criminal accusations. It also warned them not to destroy relevant records. Mom wanted her savings restored, but she wanted the facts established before deciding what else to pursue.
Dad responded through his own attorney within a week. He acknowledged authorizing all three transactions and admitted he’d falsely accused me to conceal the withdrawals. His explanation was that Melissa had promised to repay him quickly. He’d believed the money would be returned before Mom noticed.
Melissa initially denied responsibility for the renovation payment. Then the contractor provided an invoice identifying her home and the work completed. Bank records confirmed the cashier’s check had funded that invoice. Faced with the documentation, she admitted that she’d asked Dad to pay the contractor directly.
The family reached a written repayment agreement after several difficult negotiations. Dad agreed to restore $20,000 from his separate investment account immediately. Melissa agreed to repay the remaining $30,000 through proceeds from selling a rental property she owned. Both obligations were documented with deadlines and enforceable terms.
Mom insisted that the agreement include a written acknowledgment that I had not taken her money. Dad signed it, admitting that his accusations were false. Melissa reluctantly signed a separate statement correcting what she’d told relatives. Neither apology could erase what happened, but the public correction mattered.
Within six weeks, Dad transferred his portion into Mom’s new individually owned savings account. Melissa’s property sale took longer than expected, and she missed her first repayment deadline. Helen enforced the agreement through the procedures it provided. Eventually, the remaining balance was paid in full.
Mom also changed how she managed her finances. After receiving legal and banking advice, she separated future savings from accounts Dad could access without consultation. They began marriage counseling, although Mom made no promises about reconciliation. She said trust couldn’t be restored simply because missing money had been returned.
Melissa stopped speaking to me for several months. When she finally called, she admitted she’d been terrified of losing her business and had convinced herself that borrowing Mom’s savings was harmless. I told her fear didn’t excuse deception. She cried, but I didn’t offer the forgiveness she expected.
Dad apologized during a quiet lunch at a restaurant near Mom’s rehabilitation clinic. He admitted he’d sacrificed my reputation to protect Melissa from consequences. I told him that being his daughter shouldn’t mean becoming the family’s convenient scapegoat. He nodded without defending himself, which was more than he’d managed before.
Mom recovered steadily and eventually returned to her gardening club. One afternoon, she handed me copies of the final repayment records and thanked me for refusing to accept a lie. I remembered Dad pointing toward the door and demanding fifty thousand dollars I had never touched. Those three teller slips hadn’t merely cleared my name. They’d finally forced my family to confront the truth.