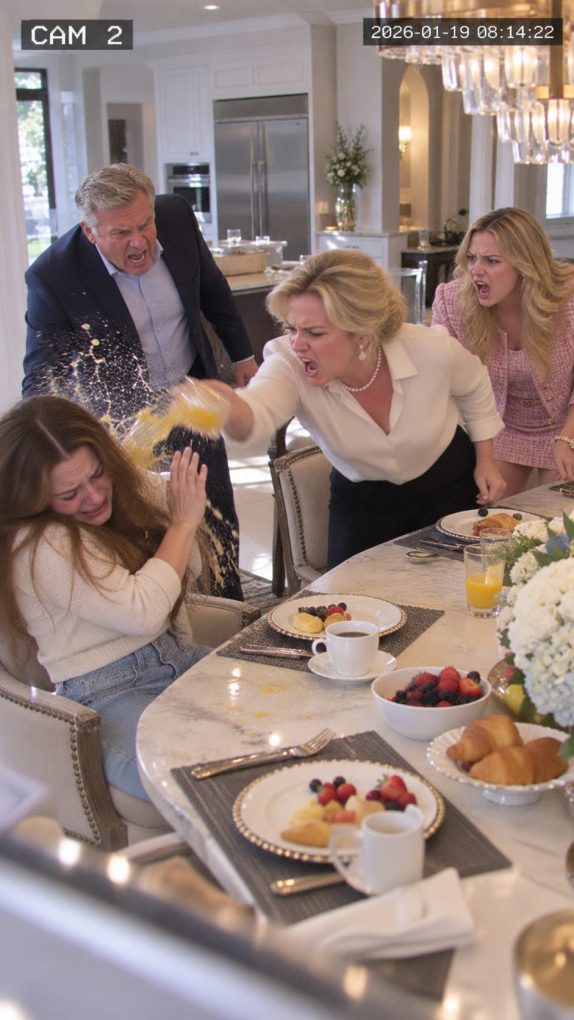
At 9:06 the morning after my eighteenth birthday, my father pushed a folder across the breakfast table and said, “Sign these before school.”
My mother smiled.
My fifteen-year-old sister, Hailey, was already scrolling through photographs of a white Range Rover on her phone.
I had been eighteen for less than twelve hours.
The night before, my grandparents’ inheritance had legally become available to me.
$4.8 million.
Grandpa and Grandma Collins had spent forty years building three hardware stores in Pennsylvania. When they died, their estate plan left my mother a separate inheritance and placed mine under custodial management until my eighteenth birthday.
For years, Dad called the money “our family safety net.”
That phrase bothered me.
Especially when Mom began saying things like, “Once Emma turns eighteen, we can finally breathe.”
So three months before my birthday, I met privately with Grandma’s longtime estate attorney, Margaret Sloan.
She explained something simple.
Once the money became mine, I was not required to leave millions sitting in accounts that could be pressured, manipulated, or casually accessed by relatives.
At 12:01 a.m. on my birthday, the custodial restrictions ended.
At 10:30 that morning, after my birthday brunch, I signed documents transferring the inherited assets into a newly established irrevocable trust administered by an independent corporate trustee.
I could receive distributions for education, housing, health, and other approved purposes.
But I could not empty the trust on impulse.
Neither could anyone else.
Especially my parents.
Now, sitting at breakfast the next morning, I opened Dad’s folder.
The first page was a contract for a $1.35 million vacation home in Naples, Florida.
The second was financing paperwork for Hailey’s future private-school tuition.
The third authorized a $600,000 “family investment” into Dad’s struggling automotive dealership.
I looked up.
“What is this?”
Mom laughed.
“Your contribution.”
“To what?”
“To us.”
Dad frowned as though I were being deliberately stupid.
“We raised you for eighteen years.”
Hailey turned her phone toward me.
“And Mom said we’re ordering this today.”
The Range Rover.
Nearly $110,000.
I slowly closed the folder.
“No.”
Nobody moved.
Dad’s voice hardened.
“Excuse me?”
“The money isn’t available.”
Mom stopped smiling.
“What do you mean?”
“I moved it yesterday.”
“Where?”
“Into a trust.”
The silence was immediate.
Dad stood so quickly his chair scraped the floor.
“You did WHAT?”
“A protected trust. Independent trustee.”
Mom’s face drained of color.
“You had no right!”
I almost laughed.
“It was my inheritance.”
Dad grabbed the folder.
“Undo it.”
“I can’t simply undo it because you want a house.”
Hailey burst into tears.
“You promised me the car!”
“I promised you nothing.”
Dad disappeared into his office.
Thirty seconds later, I heard him shouting into the phone.
Then he came back holding a printed email.
“You think you’re clever?”
He placed it in front of me.
It was from a private bank.
Subject:
CONFIRMATION OF $1,900,000 LIQUIDITY COMMITMENT
My name appeared as guarantor.
My old custodial account number appeared beneath it.
And at the bottom was an electronic signature that looked exactly like mine.
Dad leaned toward me.
“We already committed the money.”
I stared at the signature.
Then smiled.
“No, Dad.”
I pulled out my phone and called Margaret.
“You committed money that no longer exists in that account.”
Five minutes later, she asked me to photograph every page.
Ten minutes after that, the bank froze the application.
And before lunch, my father discovered the trust had not merely stopped him from spending my inheritance.
It had exposed what he had already tried to do with it.
Margaret told me not to accuse Dad of forgery at the kitchen table. The private bank preserved the application, login records, uploaded documents, and correspondence before anyone could alter them. My trust transfer had been completed the previous afternoon, so the old custodial account no longer held the assets Dad described as available collateral.
The $1.9 million commitment supported two separate transactions: the Florida property and financing for Dad’s dealership expansion. Both applications described me as a willing family investor. Neither contained a recorded conversation, witnessed signature, or direct confirmation from me because Dad had told the bank I was “traveling after graduation” and preferred him to coordinate everything.
The electronic signature came from a document I had genuinely signed two years earlier for a school investment account. Margaret compared the files and immediately noticed the signature image was identical down to a small break in the final letter. She arranged for a forensic examiner to review the originals rather than relying on visual comparison alone.
Mom claimed she thought I had already agreed. Her text messages suggested otherwise. Three weeks before my birthday, Dad wrote, Emma might resist if Margaret gets involved. Mom replied, Then do everything before she realizes eighteen means she can say no. Reading that message hurt more than the Florida house.
Hailey knew almost nothing. Mom had promised her the Range Rover and told her my grandparents had “left enough for everybody.” When I explained that Grandma had also left money directly to Mom years earlier, Hailey looked confused. Mom had already spent most of that inheritance helping Dad refinance his dealership and maintain a lifestyle their income no longer supported.
The private bank suspended both transactions. Nobody lost a Florida house because my parents had never closed on it. Dad’s dealership also continued operating, though the expansion could not proceed on the terms he expected. The bank’s concern was narrower: why had a newly eighteen-year-old beneficiary supposedly guaranteed nearly two million dollars without ever speaking to the lender?
Dad’s answer was that our family had always treated the inheritance collectively. Legally, that did not matter. My grandparents’ estate documents named me personally. Once the assets transferred from custodial control, my parents had no authority to pledge them merely because they had managed portions of my finances while I was a minor.
The trust itself was deliberately restrictive. I had chosen a corporate trustee because Margaret warned me that family pressure would be strongest during the first years of adulthood. I could request distributions for university expenses, reasonable housing, medical costs, and long-term investments, but major withdrawals required independent review. I had protected myself from my own impulsiveness too.
That fact infuriated Dad. “So some banker controls your money now?” I answered, “No. A trustee administers it under rules I chose before anyone could pressure me.” He said Grandma would have hated outsiders controlling family wealth. Margaret later showed me a letter Grandma had written saying almost the opposite.
The letter had never been necessary for the trust’s validity, but it explained her thinking: Emma is generous. Please teach her that generosity without boundaries becomes an invitation for stronger personalities to make decisions for her. Grandma had apparently understood my family better than I did.
Then the bank sent Margaret another document from Dad’s application. It was labeled Parental Consent and Beneficiary Authorization and dated two days before my eighteenth birthday. Dad had signed it as my parent, asserting he retained authority over my inherited assets until the completion of pending “family financial commitments.”
Margaret stared at the page.
“He knew his authority was ending.”
And for the first time, the timing of everything became impossible to dismiss as misunderstanding.
The bank’s investigation confirmed that Dad had submitted the disputed documents before my birthday, hoping the transactions would be approved while he still appeared to have administrative involvement in my accounts. But custodial authority did not allow him to permanently pledge my future assets for his own transactions, and the bank had not completed its verification before control transferred to me.
The forensic review concluded that my electronic signature had been copied from the older school investment document. Dad eventually admitted instructing his office manager to place the image into the application package, though he insisted he expected me to sign formally afterward. The bank treated the submission as unauthorized and closed the financing request.
No $1.9 million disappeared. That distinction mattered. The attempted commitments failed before money moved, and the Florida purchase never closed. Dad’s dealership lost the opportunity for expansion, but the existing business remained intact. He eventually sold one underperforming location and refinanced equipment through a conventional commercial lender.
Mom’s finances became clearer too. She had received approximately $780,000 from Grandma’s estate years earlier and spent nearly all of it over seven years—some on legitimate family expenses, much of it supporting Dad’s business and expensive renovations. Her fear was not that I would become poor. She feared my money would stop protecting the lifestyle she had become accustomed to.
Hailey apologized before either parent did. She returned the Range Rover brochure to Mom and told me, “I thought Grandma left the money to all of us and put your name on it because you were older.” She had been fifteen. I believed her. I told her none of this was her responsibility.
My relationship with my parents changed more dramatically. I moved into university housing earlier than planned and limited financial conversations to writing. Margaret helped me designate an independent professional as trust adviser so neither parent could step into that role later through family pressure.
Dad spent months calling the trust a betrayal. Eventually, after his bank application became part of a formal financial review, he stopped saying I had stolen money from the family. What he had really lost was not an inheritance. It was access he had assumed would automatically continue when I became an adult.
Mom’s apology came nearly a year later. “We spent so long thinking about what your inheritance could fix that we stopped thinking of it as yours,” she said. I answered, “Grandma gave you your share. You were trying to spend mine too.” She did not argue.
I used the trust exactly as intended. It paid my university tuition, helped me purchase a modest condominium after graduation, and invested the rest across diversified assets under professional management. I did not suddenly live like a multimillionaire because turning eighteen did not make me immune to bad decisions.
Years later, Dad’s dealership stabilized at a smaller size. Hailey attended a state university with scholarships and help from our parents—not from my trust. She bought her first used car herself and sent me a photograph captioned, Not a Range Rover, but the title says Hailey.
That made me laugh harder than the original birthday argument ever had.
My family once believed turning eighteen meant the vault door would finally open and all the plans they had made around my grandparents’ money could begin. In one sense, they were right. The money did become legally mine.
They simply never imagined that the first adult decision I would make was refusing to let everyone else decide what adulthood meant for me.
The trust did not make me rich.
The inheritance had already done that.
What the trust gave me was something my family had never expected me to protect:
the right to say no before their plans became my obligations.