At 8:03 the morning after my eighteenth birthday, Mom placed two cups of coffee on the kitchen table and smiled at me like she was about to discuss college applications.
“We need to talk about that money.”
My blood ran cold.
Not because I didn’t know which money she meant.
Because twelve hours earlier, every dollar of it had become much harder for anyone—including me—to touch.
My grandparents had left me approximately $3.6 million after selling the manufacturing company they spent forty years building. Until I turned eighteen, the assets remained under custodial management.
For most of my childhood, nobody discussed the inheritance.
Then my seventeenth birthday passed.
Suddenly Dad started saying things like, “When your account opens up, this family can finally make some moves.”
Mom began showing me houses.
My younger sister, Chloe, started sending photographs of private universities and new cars.
Every conversation contained the phrase our money.
Grandpa had anticipated that.
Before he died, he introduced me to his estate attorney, Eleanor Pierce. She never told me what decisions to make. She explained what ownership meant, what pressure could look like, and why receiving millions at eighteen could become dangerous when everyone around you already had plans for it.
So on my birthday, once the custodial restriction expired, I signed documents placing the inheritance into an irrevocable discretionary trust administered by an independent corporate trustee.
The money remained for my benefit.
Education.
Housing.
Medical needs.
Long-term investments.
But no enormous impulsive withdrawal could happen because somebody cried across a dinner table.
Now Mom slid a folder toward me.
“We need $900,000.”
I stared at her.
“For what?”
Dad entered carrying his laptop.
“We found an investment property.”
“Who is we?”
“The family.”
It was a forty-unit apartment building outside Philadelphia.
Dad wanted $600,000 for the equity contribution.
Mom wanted another $180,000 to clear their home-equity loan.
And $120,000 was supposedly for Chloe’s college fund.
I closed the folder.
“No.”
Mom laughed.
“You haven’t even looked at the projections.”
“The answer is still no.”
Dad’s expression hardened.
“It’s not like you earned that money.”
Neither had he.
Mom leaned closer.
“Your grandparents meant for this inheritance to help the family.”
“No. They meant it for me.”
Her smile disappeared.
Then Dad said something strange.
“Well, it may already be too late to change your mind.”
I looked at him.
“What does that mean?”
He turned the laptop toward me.
An email from a commercial lender filled the screen.
FINANCING APPROVED SUBJECT TO CONFIRMED CAPITAL CONTRIBUTION: $900,000
Below it was the name of Dad’s newly formed company.
HARRISON FAMILY HOLDINGS LLC.
And beneath Source of Equity, the application listed:
Inheritance proceeds of Emma Harrison — committed upon beneficiary’s eighteenth birthday.
My heart started pounding.
“You promised them my money?”
Dad shrugged.
“We knew you’d understand.”
I stood.
“You knew nothing.”
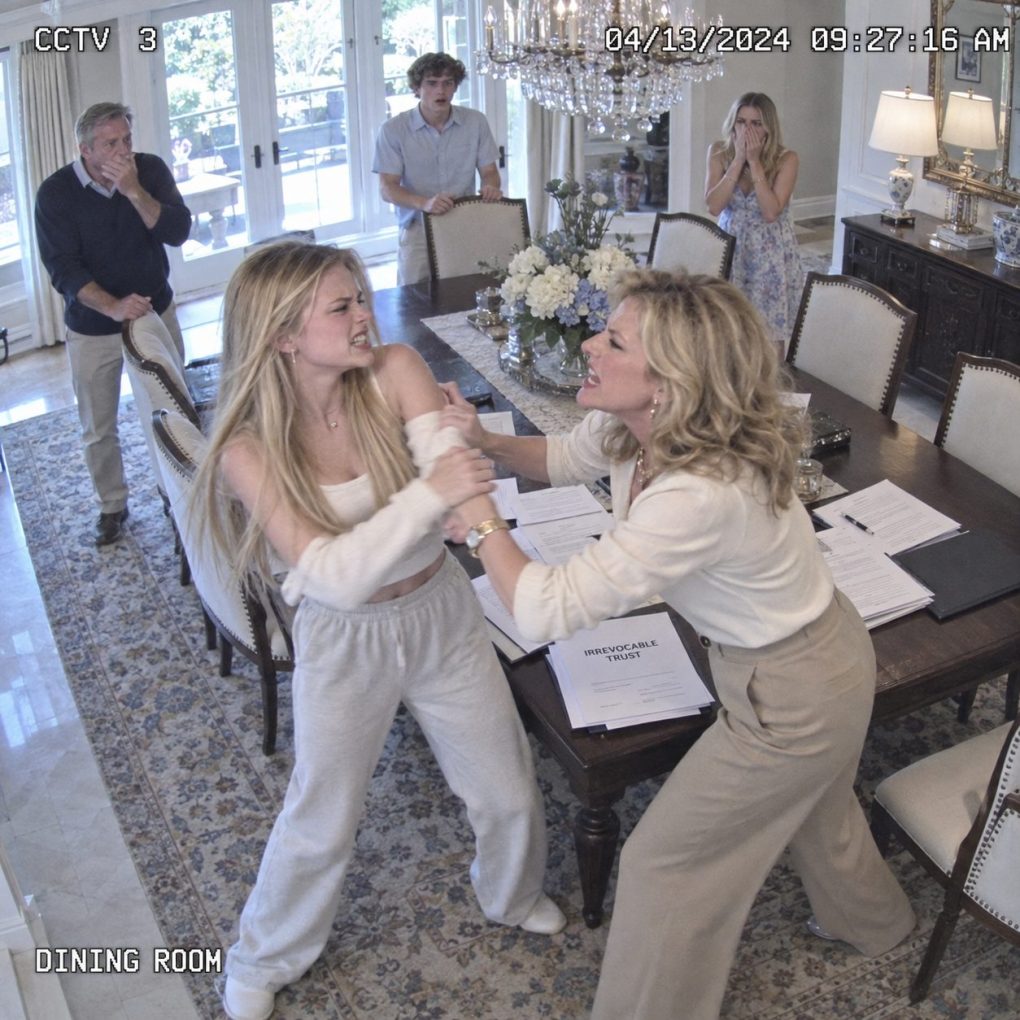
Mom reached for my wrist.
“Emma, don’t be dramatic. The closing is Friday.”
I pulled away.
Then my phone rang.
Eleanor.
I answered immediately.
Her first sentence made Dad stop breathing.
“Emma, your trustee received an attempted wire instruction this morning.”
I looked at him.
“How much?”
“Exactly $900,000.”
Then Eleanor added:
“The request included what appears to be your signature.”
I had never signed it.
Eleanor told me not to accuse anyone before the trustee preserved the original wire request, email headers, banking instructions, and every document attached to the transaction. Because the trust had become effective the previous day, neither parent had authority over the assets. The attempted transfer was stopped automatically when the trustee could not verify my approval.
The document looked convincing. It stated that I authorized a $900,000 distribution for the purchase of an income-producing property that would supposedly benefit my long-term financial interests. My electronic signature appeared at the bottom beside a date from two days earlier—when I was still seventeen.
That date created another problem. I could not have personally authorized a trust distribution before the trust even held the assets. Dad claimed the form had merely been “prepared in advance” and said he expected me to sign it after my birthday. Eleanor asked why the version submitted to the trustee was marked EXECUTED instead of DRAFT. Dad stopped answering.
Mom’s explanation was different. She said she believed my grandparents wanted the inheritance distributed fairly among both daughters. Chloe had received no direct inheritance because she was born after Grandpa’s original estate plan was drafted. Mom had apparently decided that made me responsible for correcting what she considered an unfair outcome.
I loved Chloe. None of this was her fault. When she learned what happened, she cried and told me she had never asked for $120,000. Mom had shown her college brochures and promised tuition was “already handled.” Chloe had assumed our parents had savings. She did not know their plan relied on my inheritance.
The apartment-building investment was also much riskier than Dad admitted. His lender required substantial equity because the property had high vacancy, deferred maintenance, and several commercial tenants behind on rent. Dad expected the project to recover within three years. Maybe it would have. But he had committed capital he did not own before allowing me to evaluate the risk myself.
Then the lender provided Eleanor with Dad’s investor packet. It described Harrison Family Holdings as having access to “family trust assets exceeding $3 million.” My trust was not an investor. It had never authorized the LLC, guaranteed its debts, or promised future funding. Dad had turned my inheritance into a financial credential for his company before I became legally old enough to object.
The signature image was traced to a college financial-aid form I had signed six months earlier. Metadata showed the distribution authorization had been created on Dad’s computer and edited the night before my birthday. Whether Dad personally inserted the signature still required verification, but the records made his “future draft” explanation harder to sustain.
Mom became furious at Eleanor instead of Dad. She accused her of teaching me to distrust my parents. Eleanor answered, “The trust does not prevent Emma from helping you. It prevents anybody from converting pressure into an immediate transfer.” That was exactly why I had created it.
The commercial lender suspended Dad’s financing while reviewing the inaccurate source-of-funds statements. The apartment purchase did not close that Friday. Dad blamed me for losing the opportunity. I reminded him that a transaction depending on money I had never agreed to invest was never secure enough to call his opportunity in the first place.
Then Eleanor discovered why Mom had been so desperate about the $180,000 home-equity balance. My parents had not borrowed that money for home repairs as they claimed. More than $140,000 had been transferred over three years into Dad’s previous investments, all of which had failed.
They were not asking my inheritance to create a new family future.
They were asking it to erase the financial past they had hidden from both daughters.
The attempted distribution never reached Dad’s company. The trustee documented the unauthorized request, strengthened verification requirements on my account, and required future large distributions to include direct confirmation through independent channels. The trust had done exactly what it was designed to do before twenty-four hours had even passed.
The lender handled Dad’s representations separately. Because the apartment purchase had not closed, there was no completed $900,000 loss. But Dad had still presented uncommitted assets as available equity, and the lender withdrew its approval after reviewing the source-of-funds information. Another buyer eventually purchased the building.
My parents’ debts did not magically disappear. They refinanced what they legitimately could, sold a recreational property they rarely used, and reduced household expenses. Dad took consulting work after his latest investment business failed. None of those things were pleasant, but they were solutions built around assets they actually owned.
Chloe chose a public university offering her a strong scholarship package. I offered to help with books and certain expenses from my personal income once I began working part-time during college, not from a six-figure trust distribution. She surprised me by saying, “I want Mom and Dad to stop using me as the reason you should give them money.”
That sentence changed our relationship. For years, I had worried Mom’s favoritism would turn Chloe and me against each other. Instead, the inheritance crisis showed both of us how often our parents used one daughter’s needs to pressure the other. We decided not to continue that pattern.
The disputed signature was reviewed through the appropriate legal and financial channels. Dad eventually admitted instructing an employee to prepare the authorization using documents already on his computer. He insisted he believed I would approve it after seeing the investment projections. The problem was simple: expecting consent is not the same as receiving it.
Mom took much longer to understand. She kept saying families share. I finally told her, “Sharing begins after someone asks and I say yes. What you planned was spending first and explaining later.” She had no answer that changed the meaning of those words.
I stayed in the family home until I left for college that fall. There was no dramatic midnight escape. I paid attention instead. I moved important documents into secure storage, changed passwords, and made sure every financial institution understood exactly who could communicate on my behalf.
The trust remained invested. I used distributions for tuition and, years later, part of the down payment on my first home. Most of the inheritance stayed untouched, growing rather than being consumed by one desperate family transaction after another. Grandpa’s gift became a foundation for my adulthood instead of a repair fund for decisions I had never made.
Dad eventually apologized without asking me to dismantle the trust. That mattered. “I looked at your eighteenth birthday like a deadline,” he admitted. “I thought once the money became accessible, all our problems had an expiration date.” I told him the money had become accessible to me—not to everyone standing near me.
The morning after my eighteenth birthday, Mom smiled and said, “We need to talk about that money.” She thought the conversation would be about dividing it, investing it, or deciding which family problem deserved the first check. Instead, the most important decision had already happened quietly the day before. I had not locked my family out of my future. I had simply made sure nobody could enter it carrying a plan I had never agreed to.