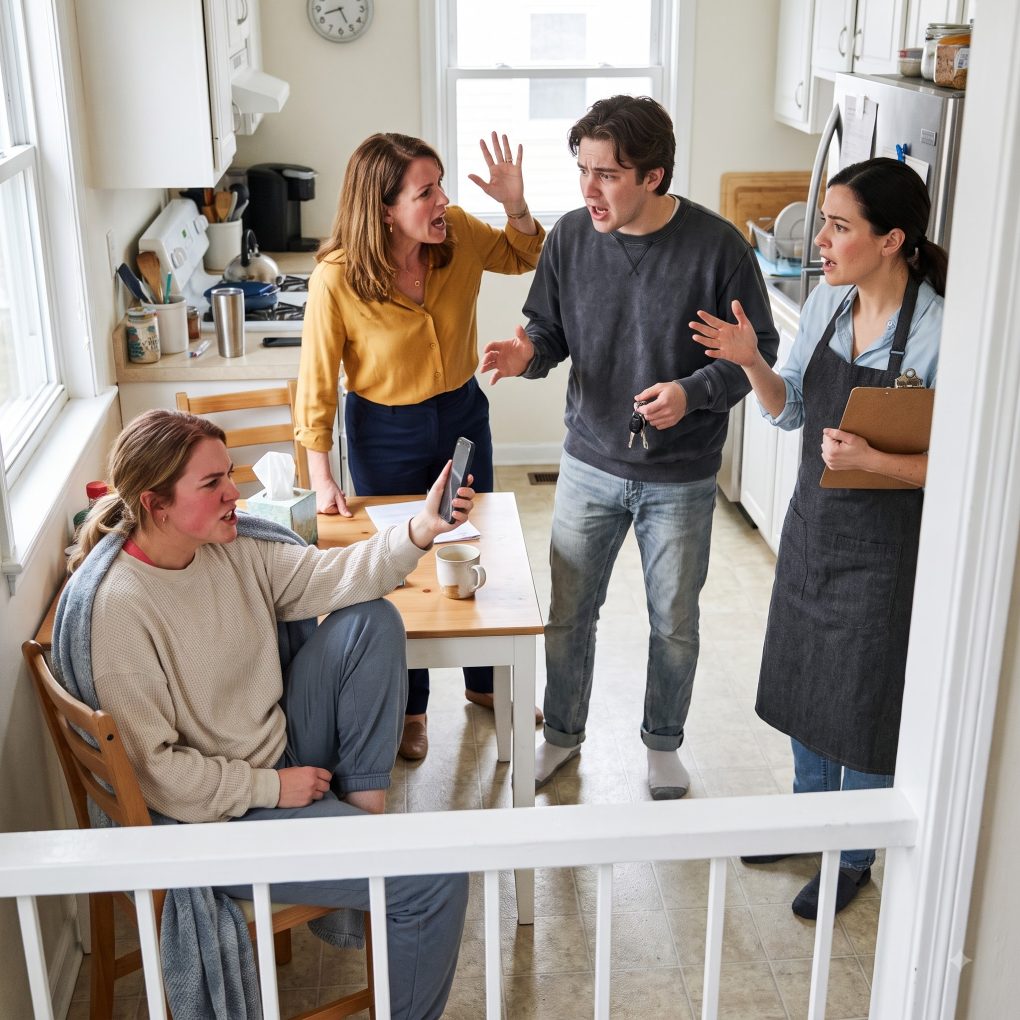
My brother stole my debit card at two in the morning while I had the flu. By breakfast, the linked account had lost $12,480. When I confronted him, Mom snapped, “He’s just a kid! You’re overreacting!” I said, “You’re right. But the account he drained wasn’t mine.”
Mom stopped wiping the counter. My twenty-year-old brother, Tyler, stared at the floor, wearing expensive sneakers he’d bought weeks earlier. I’m thirty-four and manage purchasing for Mom’s Pittsburgh bakery. The business debit card bears my name, but Mom owns the company and its account.
The card had been on my nightstand when I fell asleep. At 2:17 a.m., a banking alert lit up my phone, but my fever kept me asleep. At seven, I discovered several pending purchases and the bakery’s available balance had plunged.
“Those are just holds,” Tyler muttered. “They’ll disappear.” I turned my laptop toward Mom. The charges included a sneaker marketplace, an electronics retailer, and a luxury watch reseller. None concerned the eight employees whose paychecks were due Friday.
Mom insisted Tyler had probably borrowed the card without understanding it was for work. I reminded her that his name wasn’t on it and he’d hidden it beneath a couch cushion. Tyler demanded that I stop treating him like a criminal.
Then my phone rang. The bank’s fraud department wanted to verify the purchases, and I said I hadn’t made or authorized them. At the representative’s direction, I froze the card and requested records. She warned that disputes could take time.
Mom grabbed the phone afterward. She said I should call it a family misunderstanding. I refused to make a false statement when the missing funds were meant for payroll and refrigerated supplies.
Tyler admitted he’d used the card but claimed he’d resell everything and replace the money before anyone noticed. He’d been trying to pay debts from a failed sneaker-flipping venture. Mom whispered that she hadn’t known he was in trouble again.
I showed her the payroll spreadsheet. Eight workers depended on that bakery, and their wages were at risk. The money wasn’t an allowance or even my personal savings. It belonged to the company Mom had spent twenty-six years building.
Tyler tried to leave through the back door. Mom begged him to stay while I saved the alerts and opened an incident log. Then the head baker called about Friday’s payroll. I handed Mom the phone and watched her realize who would suffer for her excuses.
By noon, the bank confirmed that some transactions remained pending and others had already settled. The fraud specialist explained that recovery depended on the merchants, the account agreement, and the investigation. Nobody promised a refund. For the first time, Mom listened without interrupting.
I called our payroll provider to calculate exactly what we needed by Friday. Next, I contacted the vendors through their legitimate customer-service channels and asked them to stop fulfillment where possible. Two merchants agreed to cancel orders before shipment. A third said its package had already been dispatched.
Tyler returned that afternoon, expecting Mom to defend him again. Instead, she demanded the purchase confirmations and the address where he’d arranged delivery. He handed over his email receipts reluctantly. The watch had been ordered to a parcel pickup location, while the sneakers were headed to his friend’s apartment.
When I asked why he had done it, Tyler admitted he owed nearly $9,000 to people who’d financed his failed resale venture. He thought an expensive batch of merchandise would turn a quick profit. He’d gambled payroll money on the same idea that had already buried him in debt.
Mom began crying at the kitchen table. She said she’d repeatedly covered his late rent and credit card bills because she was afraid he’d lose his apartment. She’d never told me how serious his debts had become. I told her secrecy had turned a personal problem into a business emergency.
Our accountant, Mrs. Kaplan, reviewed the outstanding payroll and tax obligations that evening. We applied for short-term financing to protect employees if refunds arrived late. Mom also contributed money from her personal emergency fund. No worker would be asked to finance Tyler’s mistake.
The next morning, Mom and I met with a local attorney. She advised preserving the records and reporting the unauthorized use truthfully, without speculating about what charges authorities might pursue. Mom asked whether she could simply forgive Tyler and close the matter. The attorney reminded her that employees and business creditors had interests too.
We filed a police report and supplied the banking alerts, merchant receipts, and Tyler’s written admission. He wasn’t arrested in our kitchen, and nobody promised a particular outcome. The detective said the facts would be evaluated through the normal process. Tyler accused me of choosing strangers over my own brother.
“Those strangers baked bread beside me for six years,” I answered. “They earned their pay.” Mom stood between us, shaking, but this time she didn’t tell me to apologize. She asked Tyler to give back his house key and stay away from the bakery until further notice.
By Friday, the canceled purchases had released some of the holds, and the backup funds covered the remaining payroll shortage. Every employee was paid on schedule. Mom sat alone in her office after the last direct deposit cleared. She finally admitted that defending Tyler without consequences had almost cost other families their income.
The next month was less dramatic but far more exhausting. I worked with the bank to document each unauthorized transaction while Mom handled payroll, suppliers, and the attorney’s requests. The merchants recovered several unopened items, and credits arrived gradually. Some losses remained unresolved while the investigation continued.
Tyler moved in with an uncle after Mom refused to pay another one of his bills. He sold belongings he actually owned and used the money to begin reimbursing the bakery. A lawyer helped him understand his obligations and options. He stopped insisting that borrowing a card without permission was harmless.
Mom asked me whether I could forgive him. I said forgiveness and unrestricted access were two different things. He might someday rebuild trust with us, but he would never again have access to company cards or accounts. She didn’t argue, which was a change I hadn’t expected.
Our accountant helped us replace the old card arrangement with stricter purchasing controls. We separated purchasing approvals, enabled transaction alerts on more than one phone, and arranged for two people to review large expenditures. These were ordinary safeguards, but we should have put them in place years earlier.
A detective later told us the case was still being reviewed. We received no dramatic announcement and no guarantee about criminal charges. The financial side proceeded separately, with documented reimbursements and bank credits. Mom learned to stop describing the missing money as a misunderstanding when it had been taken without permission.
One evening, Tyler asked to meet at a coffee shop. He arrived without excuses or expensive shoes. He admitted he’d watched me sleeping and taken the card because he knew I would say no. Hearing that hurt more than the numbers on the statement.
He said he was ashamed and wanted another chance. I told him he could earn one through steady work, honesty, and repayment, not through another promise of a quick profit. He nodded and showed me confirmation that he’d started a regular warehouse job. I hoped he would keep it.
Mom eventually called a staff meeting, without disclosing Tyler’s private details. She explained that a financial disruption had been resolved, payroll had remained intact, and stronger controls were in place. Then she thanked our employees for their work. I could see how much responsibility had finally settled on her shoulders.
Weeks later, the bank and merchants completed their reviews, and the remaining amount was handled under our repayment agreement with Tyler. The company absorbed some fees, but the bakery stayed open and nobody missed a paycheck. I didn’t get a magical ending or a perfectly repaired family.
I still remember Mom calling Tyler “just a kid” while I sat shivering beneath a blanket. He was old enough to know exactly what he had taken, and she was responsible for the account he’d emptied. That morning, she thought I was defending my own money. I was defending eight paychecks and the business she’d built.