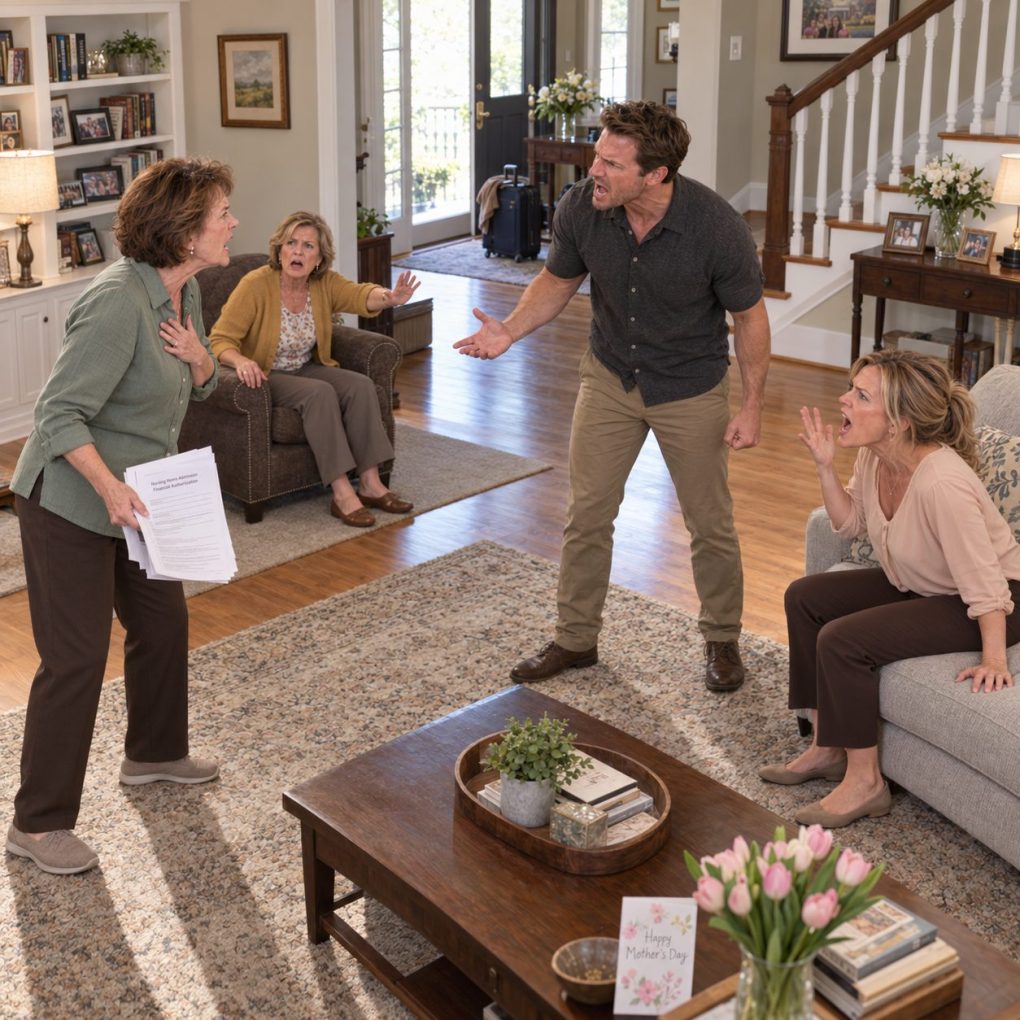
“Sign these nursing home papers, Mom, or you’ll be homeless by tonight.” My son, Daniel, pushed a folder across the kitchen table on Mother’s Day morning. His wife, Brittany, stood behind him, smiling coldly. I signed the acknowledgment page without arguing and walked out. Three hours later, Daniel rushed to my bank, demanding access to my $840,000 retirement account. The manager looked him in the eyes and said five words: “Your mother revoked your authority.”
My name is Margaret Wilson. I’m sixty-eight, a retired registered nurse from Charlotte, North Carolina. For forty years, I worked exhausting hospital shifts while raising Daniel after his father died. I never imagined the boy I’d sacrificed everything for would threaten to throw me onto the street.
Two years earlier, I’d moved into Daniel and Brittany’s house after knee surgery. I paid them $1,200 monthly for my room and contributed toward groceries. My recovery was complete, but Brittany kept insisting I couldn’t manage alone. Daniel gradually stopped defending me whenever she called me a burden.
That morning, Brittany placed a brochure for a residential care facility beside the folder. “We’ve already reserved your room,” she announced. Daniel said I needed to sign immediately because they wanted their guest bedroom back. Neither asked whether I wanted to move or could afford the facility.
I studied the documents carefully. One page merely acknowledged receiving information about the facility. Another requested permission to share medical records. I signed only the acknowledgment, leaving every consent and financial authorization blank. Brittany snatched the folder before noticing the difference.
What they didn’t know was that I’d met attorney Helen Brooks the previous Thursday. After Daniel repeatedly demanded access to my savings, I’d revoked the limited financial power of attorney I’d once given him during surgery. My bank had received the revocation and updated its records before Mother’s Day.
I’d also arranged temporary accommodation with my longtime friend, Susan. My belongings were already packed, and my important documents were safely stored elsewhere. I wasn’t leaving because I’d accepted their threats. I was leaving because I refused to spend another night being treated like unwanted furniture.
At the bank, Daniel presented his old power-of-attorney document and requested a large withdrawal. The manager, Patricia Reed, checked the account restrictions and informed him that his authority had ended. He demanded an explanation, insisting I was mentally incapable of managing my money.
Patricia refused to discuss my confidential finances beyond his lack of authority. She told him he could not withdraw funds or obtain account details. Daniel called Brittany from the lobby, furious and frightened. He’d apparently promised her that my retirement money would solve their mounting financial problems.
That evening, Daniel appeared outside Susan’s house, shouting that I’d destroyed his future. Then he revealed why he’d been so desperate. He and Brittany had already signed a contract for a luxury property, expecting to use my retirement savings for the down payment. And their deadline was Monday.
I stood behind Susan’s locked screen door while Daniel shouted from the porch. He claimed the bank had humiliated him and demanded I restore his financial authority. I asked whether he’d intended to take my savings without discussing it with me. His silence answered more clearly than any confession.
When I mentioned the luxury property, Daniel admitted he and Brittany had placed a $35,000 earnest-money deposit on a house outside Charlotte. They’d borrowed the deposit from Brittany’s parents. The purchase contract required additional funds within days, and they had expected my retirement account to cover the balance.
I asked why they believed my money belonged to them. Daniel said Brittany considered it an early inheritance. He added that they’d supported me through my surgery and deserved compensation. I reminded him that I’d paid rent, bought groceries, and covered my medical expenses myself.
The next morning, Brittany called me repeatedly. When I answered, she accused me of ruining their chance to own their dream home. She claimed the nursing facility would have been better for everyone. I asked whether she’d actually discussed my care needs with a medical professional. She hadn’t.
My attorney, Helen, reviewed the nursing home documents that I’d photographed before leaving. The acknowledgment I’d signed did not authorize admission, medical disclosure, or transfer of my funds. Helen advised me to keep copies of every threatening message. She also confirmed that Daniel had no current authority to act on my behalf.
I contacted my bank directly and reviewed the account’s security settings. The bank confirmed that no unauthorized withdrawal had occurred. I changed passwords, replaced compromised access credentials, and established additional verification procedures. I also updated my emergency contacts and reviewed my estate-planning documents with Helen.
Three days later, Brittany’s mother, Elaine, called. She had learned that Daniel and Brittany couldn’t complete the purchase without money they didn’t possess. Elaine said they’d told her I had already agreed to provide $250,000. I explained that no such promise existed and that I’d never even seen the property.
Elaine was furious, but not with me. She said she’d lent them the deposit because they presented my contribution as guaranteed. I suggested she speak with her own attorney about the loan agreement. Their financial dispute was not mine to resolve.
Meanwhile, I toured several apartments with Susan. I chose a bright, accessible one-bedroom unit near my former hospital. My pension and savings comfortably covered the rent. For the first time in two years, I could decide when to eat dinner, invite friends over, and close my bedroom door without being criticized.
Then Daniel sent a message that stopped me cold. “Brittany says we should tell everyone you’re losing your memory,” he wrote. “Maybe then they’ll understand why we tried to help.” I forwarded it to Helen immediately. My son wasn’t simply angry about losing access to my money. He was threatening my reputation to regain control.
Helen advised me not to respond emotionally to Daniel’s message. Instead, we preserved it along with the bank records, nursing home paperwork, and earlier threats. She explained that relatives couldn’t simply declare an adult incompetent. Any attempt to obtain legal control over my affairs would require an appropriate court process and supporting evidence.
I scheduled a routine appointment with my physician and discussed my living situation honestly. My doctor found no reason to question my ability to make financial or personal decisions. I requested copies of the relevant medical records for my own files. I wasn’t trying to prove my worth to Daniel, but I wanted accurate documentation.
A week later, Daniel and Brittany’s property purchase collapsed. They couldn’t provide the required funds, and their contract consequences depended on its financing and contingency terms. Brittany’s parents consulted an attorney about recovering their loan. I didn’t celebrate their disappointment. I simply refused to rescue them from a commitment they’d made using imaginary money.
Daniel began calling relatives, claiming I’d abandoned him after he’d cared for me during surgery. My sister, Caroline, contacted me after hearing his version. I showed her the messages and explained the revoked power of attorney. She was shocked. “He made it sound like you couldn’t remember your own name,” she said.
Caroline confronted Daniel privately and told him to stop spreading unsupported claims about my health. Other relatives gradually learned that I’d paid rent while living with him. Several apologized for assuming I had depended entirely on his generosity. Their support helped, although it couldn’t erase the betrayal.
Brittany eventually sent a lengthy email defending the nursing home plan. She insisted they’d been overwhelmed by having me in their house. I acknowledged that multigenerational living arrangements could become difficult. But difficulty didn’t justify threats, financial pressure, or attempting to control another adult’s retirement savings.
Two months after Mother’s Day, I moved into my apartment. Susan helped arrange the furniture, and Caroline brought flowers for the kitchen windowsill. I placed my late husband’s photograph beside the sofa. That evening, I made tea, opened the balcony door, and enjoyed the quiet without feeling like an inconvenience.
Daniel finally asked to meet at a public café. He arrived looking exhausted and admitted he’d been frightened of losing the house purchase. He apologized for demanding my money, but I told him fear didn’t excuse deception. He listened without interrupting. It was the first honest conversation we’d had in months.
I explained that reconciliation would require time, respect, and consistent behavior. Daniel would never again receive financial authority merely because he was my son. My retirement savings were meant to support my life, not finance someone else’s ambitions. He nodded and accepted that I wasn’t promising immediate forgiveness.
The following Mother’s Day, I spent the morning with Susan and Caroline at a small garden restaurant. Daniel sent flowers and a card that simply said, “I’m sorry I made you feel unwanted.” I appreciated the gesture, but I didn’t invite him to join us. At sixty-nine, I’d learned that love doesn’t require surrendering your dignity. My son had threatened me with homelessness to obtain my money. Instead, I found a home where nobody could make that threat again.