The cashier tried my card again. “Declined,” she said, softly enough to make it worse. I stood at a Target register in Columbus with a $34.99 box of diapers, a seven-month-old crying against my shoulder, and six people behind me pretending not to listen.
“Maybe run it as debit?” I asked. She did. Same red message. An hour earlier, my husband Ryan had texted, We need to talk about your spending. I had thought he meant the grocery bill.
I stepped aside and called him. He answered on the third ring, with voices and music behind him.
“Ryan, the card isn’t working. Nora needs diapers.”
“Then buy them with your own money.”
“It’s the card you told me to use for household expenses.”
“Not my problem. Figure it out yourself.”
He hung up before I could tell him I’d spent the morning at Nora’s pediatric appointment, not shopping for myself. My phone lit up again. This time it was his mother, Diane.
“Ryan said you embarrassed him over thirty dollars,” she snapped. “You sit home all day and spend his paycheck. You’re a useless leech.”
I looked at Nora’s red cheeks. She had a rash; the doctor had told me not to switch brands again.
“You don’t get to speak about me like that,” I said.
“Then contribute something. My son carries this family.”
I ended the call. The cashier had set my diapers behind her register. I found eleven dollars in a zipper pocket, enough for a travel pack of the same brand. She scanned it without asking questions.
In the parking lot, I buckled Nora into her car seat and stared at the canceled-card notification now sitting in my email. Ryan had removed me as an authorized user at 9:14 a.m. He hadn’t forgotten to pay the bill. He’d decided to teach me a lesson.
What Ryan and Diane never seemed to remember was that I owned Riverside Supply, the medical-distribution company where Ryan worked as operations director. Since Nora’s difficult birth, I had let him manage daily invoices. Ownership and bank authority had never changed.
I called Nina Brooks, the banker who had worked with me since I took over the company. “Nina, I need you to suspend Ryan’s business banking access and review any transfers awaiting my approval.”
She didn’t answer immediately. I heard a door close.
“Claire,” she said, her voice suddenly low, “your mother-in-law is in my office right now. She’s holding a notarized power of attorney that says you gave her control of the company.”
“A power of attorney?” I repeated. “I never signed one.”
“Then I won’t accept it without verification,” Nina said. “I’ll suspend Ryan’s online permissions under your authority as owner and flag the pending transactions. But please come in. Our fraud department needs a statement.”
I called Rebecca Sloan, my business attorney, from the parking lot. She told me to preserve Ryan’s messages and not confront him alone. My friend Hannah took Nora for the afternoon, and Rebecca met me at the downtown branch.
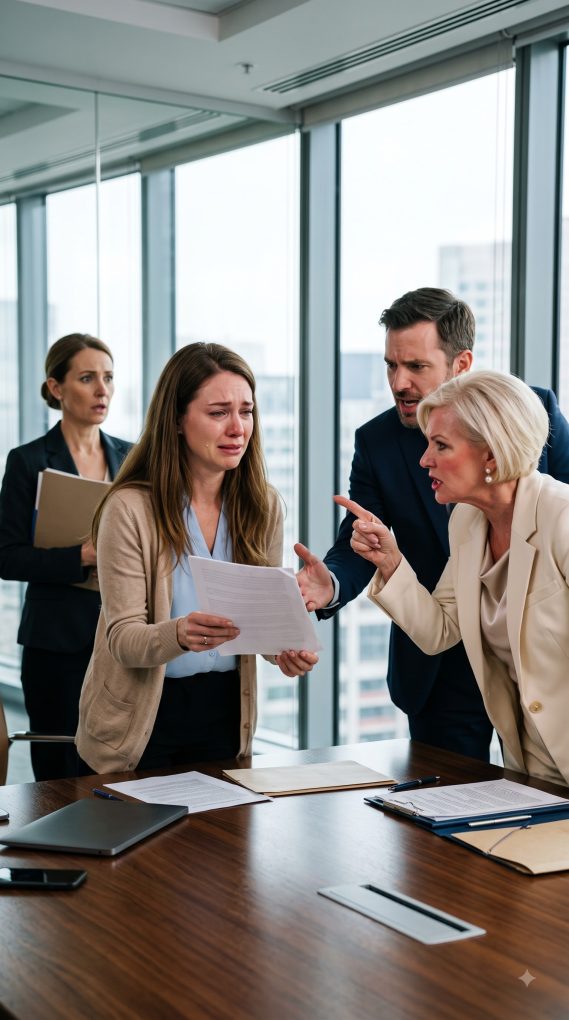
Diane sat in a glass conference room wearing a cream blazer and the expression of a woman waiting to collect a prize. Ryan was beside her. He looked at my empty arms.
“Where’s Nora?”
“Somewhere nobody is calling her mother a leech.”
His smile disappeared. “You’re making a scene because I cut off a credit card?”
“You cut off the card we used to buy your daughter’s diapers,” I said.
“You have money. I wanted you to stop acting helpless.”
Rebecca opened her notebook. “Then let’s discuss why your mother came here claiming authority over Claire’s company.”
Diane lifted her chin. “Claire asked me to take care of things when she was sick. We had everything notarized.”
Nina laid a copy of the document between us. It gave Diane permission to transfer company money, sign financing agreements, and pledge business assets. My signature looked close enough to fool a stranger, but the C was wrong. So was the date.
“March sixth,” I said. “Five days after Nora was born. I spent that entire day at the hospital because she was in intensive care. I never appeared before this notary.”
“You were exhausted,” Diane said quickly. “Maybe you don’t remember.”
“I remember watching my daughter struggle to breathe.”
Ryan looked away.
Rebecca asked Nina to preserve the original submission, security footage, and transaction records. Nina confirmed the large transfer had not gone out: the bank’s existing approval rules required direct confirmation from me.
Then she showed us what they had tried to send.
Two hundred fourteen thousand dollars from Riverside’s reserve account to Brookstone Title and Escrow. The supporting contract was for a townhouse in North Carolina. The named buyers were Ryan Bennett and Diane Bennett.
“Our company’s money was buying you a house?” I asked.
“An investment property,” Ryan muttered. “You would have benefited eventually.”
Rebecca turned another page. Eight months of payments had already gone to a supposed maintenance contractor called Harbor Facility Services. The total was $92,400. I had never approved that vendor, and its registration listed Diane’s home address.
“Those were legitimate expenses,” Diane insisted.
“Then show us the work orders,” Rebecca said.
Neither of them spoke.
I thought the house and the missing money were the worst of it. Then Rebecca examined the escrow packet more closely and pointed to a financing attachment.
“Claire, this lists your company’s warehouse as collateral for a separate $380,000 loan.”
Nina checked the date. “The lender expects to release those funds tomorrow morning.”
Ryan reached for the page. Rebecca covered it with her hand.
Tomorrow morning. By then, they could have put a mortgage against the building my employees depended on.
“Call the lender,” I told Rebecca. My voice sounded steadier than I felt. “Before anyone signs another piece of paper in my name.”
She asked Nina for the contact information in the financing packet. Then she called the lender’s fraud department, identified herself as my attorney, and sent a written dispute with Riverside’s ownership records. Nina forwarded confirmation that our bank had rejected the supposed power of attorney pending investigation. The lender agreed to halt the scheduled funding while its legal team checked the documents.
Only then did I turn to Ryan.
“Tell me why you did this.”
“Because you stopped listening to me,” he said. “You had a baby and left me to run everything.”
“I took maternity leave after an emergency delivery. I didn’t give you my company.”
“I made that place profitable.”
“Riverside was profitable before I married you. You were paid a six-figure salary to manage operations, and I trusted you with my staff. That’s what you used against me.”
Diane pushed her chair back. “Ryan deserves something for all he’s sacrificed.”
“He has a salary and retirement benefits. Neither one includes forging my signature.”
Rebecca asked about Harbor Facility Services. Diane claimed it had provided warehouse consulting. But she couldn’t name a single project, and Ryan couldn’t produce a contract. Finally he snapped, “Mom lost most of her retirement money when my logistics venture failed. I was paying her back.”
There it was. The venture he had once described as a harmless side investment had collapsed the previous year. Instead of telling me, he had approved fake vendor invoices to move Riverside’s money into his mother’s account. Then they’d arranged to buy a North Carolina townhouse in both their names, using our business reserve for the down payment and a loan secured against our warehouse for the rest.
They called it helping family. I called it taking money that belonged to a company with twenty-six employees.
“And the power of attorney?” I asked.
Diane looked toward the door. Ryan rubbed his forehead.
“You signed so many things at the hospital,” he said. “I had a copy of your signature. Mom knew a notary who could help.”
My hands went cold. While I had sat beside Nora’s incubator, Ryan had been saving images of documents with my name on them. Now one of those signatures had been placed on paperwork I had never seen, and a notary had certified an appearance I had never made.
Rebecca didn’t argue. She wrote down his words and asked Nina to preserve the bank’s camera footage, the submission records, and the original document. Then she told Ryan and Diane that further communication about the company would go through counsel.
That afternoon I removed Ryan’s operational authority through our company’s formal procedures and had our IT administrator revoke his access to payroll, vendors, and financial records. I called our controller, Marisol, and told her to review every payment he’d authorized. She didn’t ask why I sounded shaken. She simply said, “I’ll pull the backups.”
By evening, Marisol had confirmed that Friday’s payroll could be paid because the $214,000 wire had never left our account. We would have to rebuild the reserves drained by the fake invoices, but no employee would miss a paycheck. The lender also confirmed in writing that the $380,000 loan would not fund on the forged authorization. The warehouse remained ours.
Then I picked Nora up from Hannah’s house. My daughter reached for me with both hands. I cried for the first time that day, not because I had lost my marriage, but because I had nearly let two people who called themselves family risk everything I had built for her.
I didn’t return home to fight. With Rebecca’s help and advice from a family-law attorney, I secured our records, found temporary housing, and began divorce proceedings. We requested appropriate financial disclosures and temporary parenting and support orders. I also made a police report and submitted the disputed notarization for investigation. I knew there would be no instant courtroom victory. I wanted a record that could not be talked away.
A forensic accountant eventually traced all $92,400 to Diane’s account. There were no matching maintenance services. Her supposed company had no workers or equipment. The notary had never met me, a fact confirmed during the investigation. Ryan’s emails showed he had prepared the financing packet and the townhouse purchase months before he canceled my household card.
Eight months later, our civil case ended in a signed repayment agreement. Diane sold a rental property to return the missing money and cover the accounting costs. Ryan no longer worked at Riverside. The divorce settlement left my preexisting ownership of the business intact, addressed our other marital assets, and established support and a parenting schedule for Nora. The criminal investigation was separate; I left those decisions to the authorities.
Ryan sent me one final message: I was only trying to give Mom some security. You didn’t have to ruin everything.
I looked at the screenshot of his earlier reply, still saved on my phone.
Not my problem. Figure it out yourself.
I deleted neither message. They reminded me why I had stopped apologizing for protecting my daughter.
A week after the settlement, I returned to the same store with Nora, now old enough to point at everything from the cart. I bought two boxes of diapers and paid with a card linked to an account I alone controlled. The cashier didn’t recognize me. I was grateful for that.
As I carried Nora to the car, I understood what that phone call to Nina had really changed. It hadn’t made me powerful. It had reminded me that I already had a voice, a responsibility, and the right to use both.
And this time, nobody could switch them off.