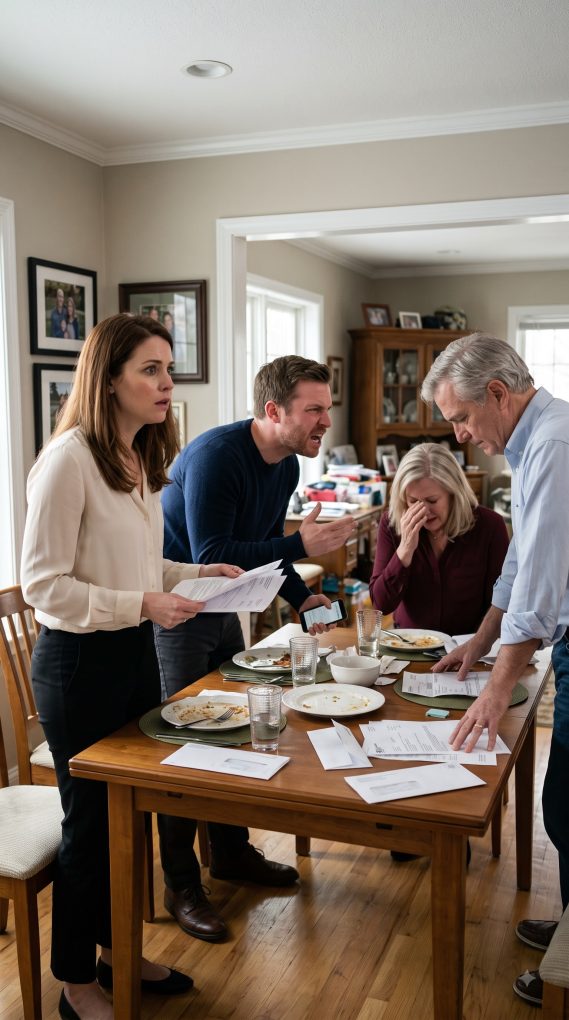
My brother set down his fork and announced he was moving into my house on Monday. Mom nodded as though he had merely asked for more potatoes. “Mom and Dad promised I could live with you,” Ryan said. “The movers are booked. I already changed my address.”
I took a slow sip of water. “That’s awkward. I sold the house last Friday to a couple.”
For a moment, nobody moved. Then Mom’s glass struck the table. “You did what?” I told her the closing was complete, the buyers had their keys, and I was staying in a short-term rental until my new apartment was ready. “You can’t make plans for a house I don’t own anymore,” I added.
Ryan stared at me. “You never told me you were selling.” “You never told me you were moving in.” Mom spoke first. “After everything we’ve done for you, Claire, you could at least have discussed it with us.” She said it with the confidence of someone who had forgotten whose name was on the deed.
“I paid for that house myself,” I said. “And I repaid the money you lent me for the furnace three years ago.” Ryan pushed his chair back. His face had gone from embarrassed to frightened. “Then what happens to my fifty-seven thousand dollars?”
He opened his banking app and showed me a transfer to our parents’ joint account. He had sent them his divorce settlement in August. They had told him it was a buy-in for five years of guaranteed housing at my place. “Mom even gave me an agreement,” he said. “She told me you’d signed it.”
The agreement came out of his jacket pocket, folded into quarters. It described a downstairs bedroom, use of the garage, and a “nonrefundable family equity contribution.” My name appeared at the bottom in a crooked imitation of my signature. “I have never seen this,” I said.
Dad shut his eyes. Mom reached for the paper, but Ryan pulled it away. “Tell me it’s a mistake,” he demanded. Instead, Dad took a thick envelope from beside his chair. “We were going to explain after dinner,” he whispered. Inside was a demand letter from a commercial lender, addressed to me at my parents’ house.
The lender wanted payment on a $218,000 business loan for Morgan Property Solutions LLC. I was listed as the personal guarantor. My Social Security number was on the application, beside another forged signature. The loan was already overdue. And when Ryan turned the next page, his face went white. “Claire,” he said, “they’ve listed me as the owner of this company.”
I looked at our parents. Neither denied it.
“Owner?” Ryan repeated. “I don’t own a company.” He turned the document toward Dad. “What is Morgan Property Solutions?” Dad stared at the table. Mom answered too quickly. “It was supposed to be temporary. We only needed to get through the summer.”
I spread the papers across the table. The application described Ryan as managing member of a property maintenance business with twelve employees. He worked as an auto mechanic. The company had been registered four months earlier, using his name and an old copy of his driver’s license. The signatures on its operating agreement were as false as mine.
“Why use my credit?” I asked. Dad finally looked up. “Because yours was good. The lender wouldn’t approve it without a guarantee.” He said that as though my credit history were a household appliance anyone could borrow. I asked where the $218,000 had gone. Mom said it had kept the family afloat. She would not say which family expenses required two stolen identities.
Ryan pulled up his August transfer again. “And my fifty-seven thousand?” Dad rubbed his forehead. “That covered the mortgage payments we’d missed.” “You told me I was buying a place to live,” Ryan said. His voice cracked on the last word. “You knew I gave you everything I had after the divorce.”
Mom tried to reach for his hand. He moved it away. “We had no choice,” she insisted. “Your father’s business failed. We were going to lose this house.” I glanced at the framed photographs on the dining room wall, the home where we had celebrated every birthday. “Then why didn’t you tell us?” I asked. “Why did you tell him he owned part of mine?”
“Because we thought you’d let us stay there, too,” Dad said.
I stared at him. They hadn’t merely planned to put Ryan in my spare bedroom. They had planned to move themselves in after the bank took their home. Mom whispered that I had always been the dependable one. She had mistaken dependability for consent.
Ryan checked the county court website on his phone. The foreclosure filing was six months old. The sale was scheduled for next month. Our parents had hidden every notice while telling both of us the mortgage was current. Then Ryan saw the lender’s first collection letter, dated two weeks earlier. It asked who had authorized the online signatures.
Dad reached for the letter, but I held it down. “What did you tell them?” Mom’s eyes darted toward the kitchen. Dad’s shoulders sagged. “We sent a statement on Friday.” “What statement?” Ryan demanded. Dad pulled a printed copy from the envelope. At the bottom were both our parents’ names.
The statement said Ryan had handled the application and obtained my agreement without their knowledge. They had used his identity to borrow money, taken his savings, and then told the lender he was responsible for the fraud. Ryan read it twice before looking at Dad. “You were going to let them come after me?”
Dad’s answer was barely audible. “We thought we could fix it before anyone found out.”
Ryan stood so abruptly his chair hit the wall. Mom flinched, but I didn’t move. I laid the false occupancy agreement beside the loan papers and the statement blaming him. Three documents. Two stolen identities. A lifetime of being told we were selfish whenever we questioned our parents.
“Take pictures,” I told him. “Every page.” Dad tried to explain that the statement was only meant to buy time. “You accused your own son of forging his sister’s signature,” I said. “That’s not buying time. That’s choosing who gets hurt.” Ryan photographed the documents with shaking hands, then emailed the images to both of us.
Mom began to cry. “If you report this, we’ll lose everything.” Ryan looked at her with an expression I’d never seen before. “You took everything I had and called it helping me.” Dad asked whether he could call the lender in the morning and straighten it out privately. I told him he could call, but so would we.
Before leaving, I made Ryan cancel the movers. I also called the couple who had bought my house. Ben and Natalie were already unpacking in their new living room. I explained that relatives had been given an unauthorized agreement and might still have an old key. They arranged to change the locks the next morning.
Outside, Ryan sat on the curb beside my car. “I really thought you’d agreed,” he said. “They told me you wanted to help me get back on my feet.” I believed him. I had envied him once. Now I understood favoritism was another leash. They had promised him comfort while quietly spending his future.
On Monday, I called Rebecca Sloan, the attorney who had reviewed my home-sale contract. She confirmed that the sale had closed properly. The business loan was not a lien against the property, so my buyers’ title was not affected. The fake occupancy agreement gave Ryan no right to enter the house. She referred us to a lawyer who handled identity theft and business fraud.
We filed police reports, froze our credit files, submitted identity-theft affidavits, and sent written disputes to the lender. Ryan also provided the transfer receipt for his $57,000. The lender’s fraud department opened an investigation and suspended collection efforts against us while it reviewed the documents. For weeks, I checked every letter with my name on it.
Then the investigator requested the loan’s electronic signing records. The verification codes had gone to a phone number on our parents’ family plan. The applications had been submitted from their home internet connection while Ryan was at work and I was attending a conference in Chicago. Copies of our old driver’s licenses had been uploaded as identification. Mom had asked us for those copies the previous year, claiming she needed to update an insurance file.
The money hadn’t been used to restart a business, as he’d claimed. Bank records showed payments toward overdue mortgage installments, business debts from his failed contracting company, and transfers into their personal account. The “twelve employees” were invented. Morgan Property Solutions existed on paper, with my brother’s name attached to it like a shield.
When Dad called, I put him on speaker so Ryan could hear. “I knew the loan was wrong,” he admitted. “Your mother handled the applications, but I signed that statement about Ryan. I was afraid of losing the house.” “So you chose to lose us instead,” Ryan said. Dad had no answer.
The investigation took months. Eventually, the lender removed my personal guarantee and cleared Ryan of responsibility for the company’s loan after determining that our authorizations had been forged. The debt didn’t disappear; the lender pursued the business and the people who had actually arranged the borrowing. The county prosecutor later filed fraud and forgery charges against our parents. Their attorneys negotiated pleas that included restitution obligations. For once, the consequences did not get passed to their children.
Their house went through foreclosure. Mom had spent years telling neighbors that I would take care of the family no matter what. Instead, she and Dad moved into a small rental on the other side of town. They sold their camper, Dad’s restored truck, and what remained of his business equipment. Along with money drawn from Dad’s retirement savings, the sales covered the $57,000 they owed Ryan. He received the final payment under a written settlement, not a tearful promise across a dinner table.
I didn’t enjoy watching them lose the house where we’d grown up. There were photographs on those walls, pencil marks measuring our heights beside the pantry door, and a hundred good memories tangled with the bad ones. But missing a home is different from being responsible for saving it. I could grieve what happened without volunteering my life to undo it.
Ryan rented a modest duplex near his job. One Saturday, he invited me over for dinner. The table was secondhand, the chairs didn’t match, and he had burned one side of the garlic bread. We laughed harder than either of us expected. Then he looked up and said, “I’m sorry I believed them before I asked you.” I told him I was sorry I’d mistaken his silence for knowing what they were doing.
A month later, Mom mailed me a letter asking when we could be a family again. I wrote back that rebuilding trust would require honesty, time, and respect for boundaries. It wasn’t forgiveness, but it wasn’t revenge either. It was the first decision about my family I had made without waiting for their permission.
The couple who bought my old house sent me a photograph of their first holiday decorations on the porch. They looked happy there. I was happy in my apartment, too. For years, my parents had insisted that family meant keeping your door open, whatever the cost. It took selling one house to understand that love does not give anyone the right to a key.