“Your money is family property now,” my mother announced, smiling as though she’d just won the lottery. I stared at her across the kitchen table, stunned by her arrogance. She had somehow discovered the $680,000 sitting in my savings account, money I’d earned selling my small software company.
My name is Emily Carter, and I’m thirty-six years old. I live in Charlotte, North Carolina, where I spent eleven years building a business from nothing. My mother, Diane, had never invested a dollar in it, but apparently she believed my success belonged to everyone.
“You’re going to help your brother expand his restaurant business,” she continued. “Jason already found a second location, and we promised the bank you’d provide the investment.” I nearly dropped my coffee. Nobody had asked my permission, and I hadn’t agreed to finance anything.
When I demanded an explanation, Mom opened her laptop and showed me a financing application. My savings account was listed as the source of a $500,000 capital contribution. Worse, an attachment claimed I had committed the funds, although I had signed nothing.
I recognized the account number immediately. Years earlier, I’d opened that savings account jointly with Mom while attending college, then continued using it long after becoming financially independent. She hadn’t contributed anything, but her name remained on the account.
I didn’t argue. Instead, I drove straight to my bank, requested a complete transaction history, and transferred the money into a new account held exclusively in my name. I preserved records proving every dollar came from my business sale and investment earnings.
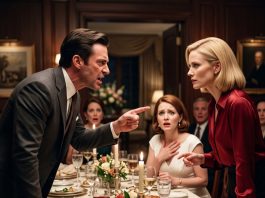
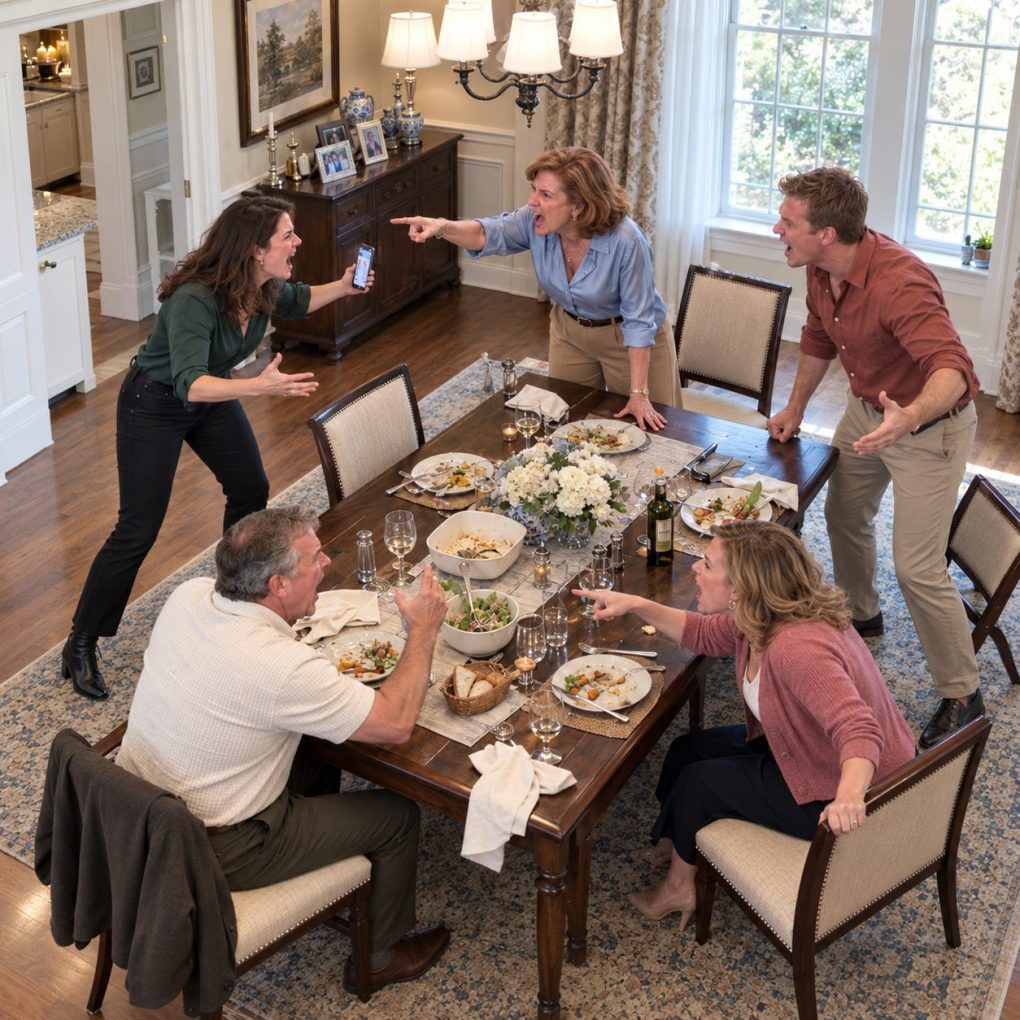
That evening, Mom invited me to Sunday dinner, supposedly to celebrate Jason’s new restaurant. I arrived knowing she’d already promised everyone my money. My father, brother, sister-in-law, and two aunts sat waiting around the enormous dining table.
Jason raised his glass and grinned. “Here’s to Emily finally contributing something useful to this family!” Everyone laughed except me. Mom leaned closer and whispered, “Don’t embarrass us. We made financial commitments based on your account.”
Then she announced that Jason would receive half a million dollars from my savings. My sister-in-law called me selfish when I calmly explained that I had never agreed. Dad slammed his hand against the table and demanded that I respect my mother’s decisions.
I stood up, pulled out my phone, and showed Mom the account’s zero balance. “You promised money that was never yours,” I said. Her smile vanished instantly. Then I revealed that the bank financing officer had already received my written statement denying the supposed commitment.
For several seconds, nobody moved. Mom stared at my phone as if the empty account balance were some kind of technical mistake. Then Jason jumped from his chair, knocking over a glass of wine, and demanded to know where I’d hidden his investment.
“My investment?” I repeated. “Jason, you’ve never invested anything in my company or paid a dollar into that savings account.” He shouted that he’d already signed an agreement to purchase the restaurant property. Apparently, my money was supposed to rescue a deal he’d made without financing.
Mom grabbed my wrist and accused me of deliberately sabotaging the family. I pulled away and told her that promising someone else’s savings was not a business strategy. Dad insisted that because Mom’s name had been on the account, she had every right to use its balance.
I explained that account access didn’t establish who had contributed the money or prove my consent to their proposed investment. Then I showed them the bank statements documenting its source. Mom suddenly became interested in clearing the dinner plates rather than explaining the financing application.
The following morning, my attorney, Rebecca Collins, examined the documents. She discovered that Jason’s restaurant company had applied for a substantial commercial loan based partly on my supposed contribution. The lender had received a letter bearing my typed name, claiming I had agreed to provide $500,000.
Rebecca immediately contacted the lender’s compliance department and requested that the disputed commitment be removed from consideration. She also advised me to preserve all messages and financial records. Within two days, the lender suspended the application pending verification of the proposed funding.
Jason called me seventeen times that afternoon. When I finally answered, he screamed that the restaurant seller was threatening to keep his earnest-money deposit. He had paid $45,000 toward the purchase using funds borrowed against my parents’ house.
That revelation changed everything. Mom and Dad had quietly opened a home equity line of credit months earlier, convinced that Jason’s expansion would make the entire family wealthy. Their existing restaurant was already struggling, and the new location had become their desperate attempt to survive.
At Rebecca’s office, we reviewed the messages Mom had sent Jason. One read, “Emily won’t refuse once everyone knows she’s responsible for our future.” Another instructed him to proceed with the purchase before telling me. Rebecca said the correspondence could help establish that no genuine investment agreement existed.
Three days later, Mom appeared outside my office crying. She admitted the bank wanted additional documentation and that Jason’s purchase might collapse. Then she made one final demand: “Transfer the money back, Emily. Your father and I could lose our house.” I looked at her and asked, “Why did you put your house at risk before asking me?”
Mom couldn’t answer. She stood beside my car with tears running down her face, clutching the expensive handbag she’d purchased during Jason’s first restaurant opening. For the first time, I saw something beneath her usual confidence: genuine fear of losing the comfortable life she’d always demanded.
I told her I would not finance Jason’s expansion, but I would attend one meeting with their accountant to understand the family’s actual financial position. She immediately agreed. I made it clear that attending a meeting did not mean accepting responsibility for their debts.
The accountant, a weary man named Thomas Reed, explained the situation the next afternoon. Jason’s restaurant had been losing money for eighteen months, and my parents had repeatedly covered payroll and supplier bills. Their home equity borrowing had increased the pressure rather than solved anything.
Thomas also revealed that Jason had withdrawn nearly $70,000 from the business over the previous year for personal expenses. His luxury truck, vacations, and expensive watches suddenly made sense. While my parents struggled to keep his employees paid, Jason had continued presenting himself as a successful entrepreneur.
When confronted, Jason exploded. He called the withdrawals compensation for his hard work and accused everyone of turning against him. Dad finally shouted, “We mortgaged our house because you told us the business was profitable!” Jason stormed out, leaving his wife crying beside the conference table.
The restaurant purchase eventually collapsed when financing could not be secured. According to Thomas, Jason negotiated an agreement that allowed the seller to retain part of the earnest-money deposit. The original restaurant remained open temporarily while its creditors and accountant worked through restructuring options.
My parents decided to sell their large suburban house before their debts became unmanageable. They moved into a smaller condominium outside Charlotte and began rebuilding their finances. It wasn’t the life Mom had imagined, but it was one they could realistically afford.
Meanwhile, Rebecca helped me document the ownership history of my savings and close the old joint account. We also pursued clarification regarding the disputed financing letter. The lender ultimately confirmed that no loan had been issued based on the claimed contribution, and I faced no obligation under that application.
Six months later, Mom invited me to lunch at a modest diner. She looked older without her carefully arranged jewelry and expensive clothes. “I treated your success like something I was entitled to distribute,” she admitted. “I was wrong, Emily, and I owe you an apology.”
I accepted her apology but refused to restore the financial access she’d once enjoyed.
Jason still blamed me for his failed expansion, although his debts had existed long before I discovered the scheme. Driving home that afternoon, I realized the greatest thing I’d protected wasn’t my $680,000. It was my right to decide what happened to the life I’d built. And when Mom later asked whether we could start rebuilding our relationship, I told her we could begin with something our family had always struggled to give me: respect.