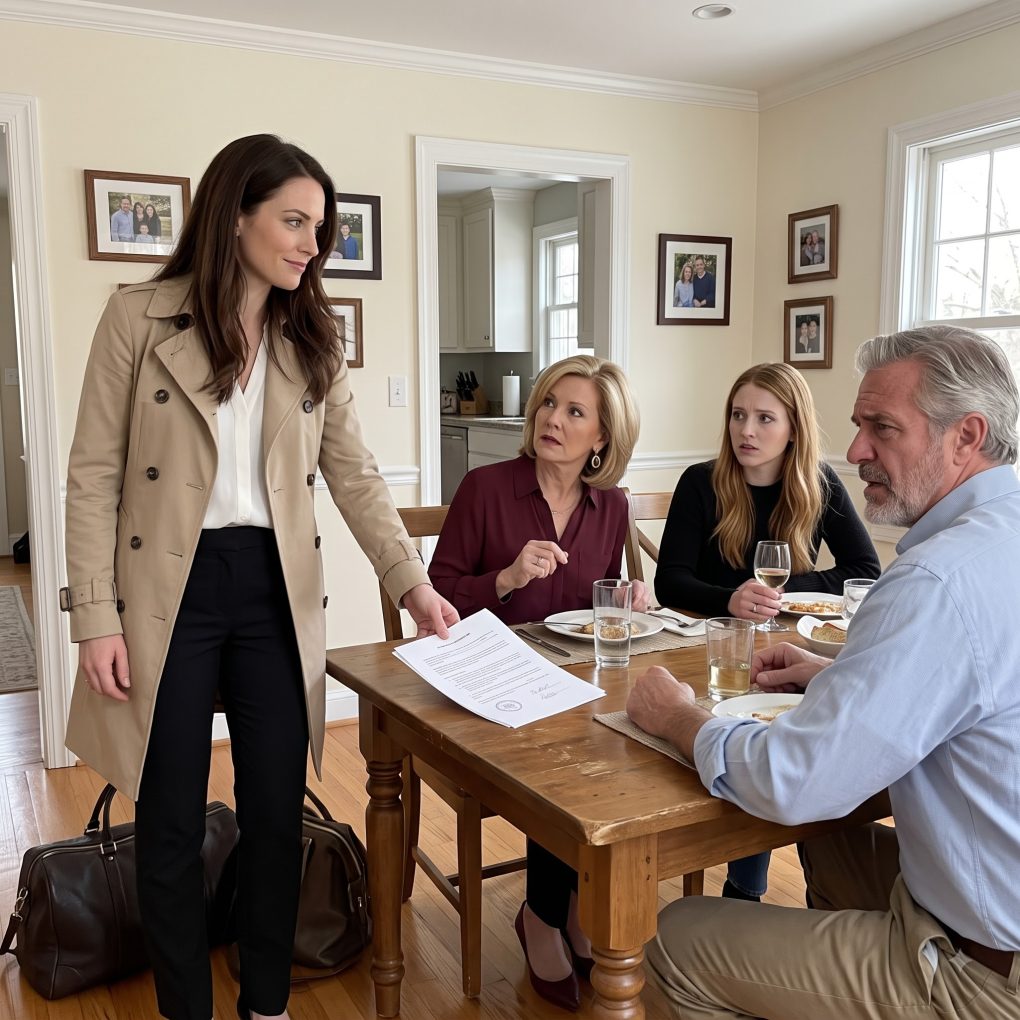
“They sold my home while I was on vacation and laughed that I was homeless. Then I placed a single document on the table.”
The moment I walked through my front door, my mother raised a champagne glass and announced, “Congratulations, sweetheart. You’re officially homeless!”
My sister burst out laughing.
I was still holding my suitcase.
“What did you just say?” I asked.
Mom leaned against my kitchen counter, smiling like she’d won a prize. “I sold your house, Emily. Your sister had $214,000 in debt, and someone had to fix it. Family comes first.”
My sister, Vanessa, lifted her glass. “Honestly, you should thank Mom. You weren’t even here to notice.”
I stared at them.
I was thirty-six years old. I had spent eleven years paying the mortgage on that four-bedroom house outside Austin, Texas. Every renovation, every property tax bill, every emergency repair had come out of my own paycheck.
And now my mother was standing in my kitchen, celebrating the sale of my home.
While I was on a two-week vacation in Hawaii, she’d apparently decided my property was hers to sell.
“Where did you get the authority to do that?” I asked.
Mom rolled her eyes. “Don’t start with the drama. Vanessa was drowning. Creditors were calling her every day. Her marriage was falling apart. You have a good job and no children. You’ll recover.”
Vanessa smirked. “Besides, the buyer already paid. The debt is gone. What’s done is done.”
I slowly set my suitcase down.
“Who bought it?”
Mom exchanged a look with Vanessa.
“Someone who understood the situation,” she replied.
That answer told me everything.
My mother had always treated Vanessa like the daughter who deserved rescuing. When Vanessa maxed out credit cards, I was expected to help. When she lost jobs, I was expected to lend money. When I refused, I was called selfish.
But selling my house?
That was something else entirely.
Mom pointed toward the door. “You can stay with us until you find an apartment. Though, honestly, with your attitude, don’t expect us to make it comfortable.”
Vanessa laughed again.
“Look on the bright side, Emily. At least you don’t have a mortgage anymore!”
I looked from one woman to the other.
Then, unexpectedly, I started laughing.
“Ha… ha… ha.”
Their smiles faltered.
“What’s so funny?” Mom demanded.
I reached into my carry-on bag and pulled out a document folder.
“You really should have checked the paperwork before celebrating.”
I placed a single sheet of paper on the kitchen table.
Mom glanced down.
Vanessa leaned over her shoulder.
Within seconds, the color drained from both their faces.
“What… what is this?” Mom whispered.
I pulled out a chair and sat down.
“It’s the reason neither of you should have touched my house.”
Then the doorbell rang.
Mom looked toward the entrance, trembling.
Because whoever stood outside wasn’t there to congratulate Vanessa.
And the name printed at the bottom of that document was about to destroy the story they’d been telling themselves for years.
My mother thought she’d made me homeless.
She had no idea that the house sale was only the beginning of her problems.
The doorbell rang again.
Mom didn’t move.
Vanessa grabbed the document from the table, scanning it as if the words might rearrange themselves into something less frightening.
“This can’t be legal,” she whispered.
I held out my hand.
“Give it back.”
She dropped the paper onto the table.
The document was a recorded notice of an ownership dispute, filed before the supposed sale had been completed. Attached to it was a copy of the deed showing that the house was held in my name alone.
But that wasn’t the part that frightened them.
At the bottom was the name of the attorney who had prepared the filing.
My attorney.
And beside his name was a case reference connected to a pending investigation into an attempted fraudulent property transfer.
Mom shook her head.
“You can’t do this to your own mother.”
“I didn’t do anything to you, Mom. I came home from vacation and discovered you’d supposedly sold my house.”
“We were trying to help Vanessa!”
“By selling property you don’t own?”
Vanessa slammed her palm against the table.
“You’re acting like we stole from you!”
I stared at her.
“You sold my house without my permission. What would you call it?”
She opened her mouth, then shut it again.
The doorbell rang a third time.
I stood and opened the door.
My attorney, Richard Coleman, stood on the porch beside a woman carrying a leather briefcase. She introduced herself as a representative of the title company that had contacted his office about the transaction.
Richard stepped inside.
“Good afternoon,” he said calmly. “I understand there are questions about the attempted sale of this property.”
Mom immediately launched into an explanation.
She said I’d given her permission. She said the family had agreed to use the proceeds to settle Vanessa’s debts. She said I was upset because I’d returned earlier than expected.
Richard listened without interrupting.
Then he placed another document on the table.
“Mrs. Carter, do you have written authorization from Emily to sell this property?”
Mom’s face tightened.
“I don’t need written permission from my daughter.”
“Unfortunately for you, that’s not how property ownership works.”
Vanessa suddenly looked toward the hallway.
“Mom, you said the buyer knew everything.”
Richard turned to her.
“What exactly did the buyer know?”
Neither woman answered.
The title representative opened her briefcase and removed a copy of the purchase file. The buyer had transferred an initial deposit, but the title company had flagged discrepancies in the seller’s authorization.
The closing had not been finalized.
The deed had not been transferred.
And the funds intended to complete the transaction had been placed on hold while the ownership issue was reviewed.
Mom’s confident expression finally cracked.
“But we already used some of the money,” Vanessa blurted.
The room went silent.
I turned toward her.
“What money?”
Vanessa’s eyes widened as she realized what she’d admitted.
Mom grabbed her arm.
“Stop talking.”
Richard’s expression hardened.
“Mrs. Carter, if money has been transferred or distributed in connection with a disputed sale, we need a complete accounting immediately.”
Mom looked at me, suddenly desperate.
“Emily, please. We can fix this privately.”
I almost felt sorry for her.
Almost.
Then Vanessa said the words that changed everything.
“Mom told me the house wasn’t really yours anymore.”
I frowned.
“What does that mean?”
Vanessa looked down at the paperwork.
“She said Grandma had promised the property to me years ago. She said you were only holding it temporarily.”
My grandmother had died six years earlier.
And I’d never heard anything about that promise.
Richard slowly turned toward Mom.
“Is that claim based on a will, a trust, or a recorded deed?”
Mom didn’t answer.
He repeated the question.
Still nothing.
Then the title representative pulled a second document from her briefcase.
“This was submitted to support the seller’s authority,” she said. “We need to determine whether it is authentic.”
I looked at the page.
It appeared to be a notarized authorization bearing my signature.
Except I had never signed it.
And the notary’s name belonged to someone who had died two years earlier.
Richard stared at Mom.
“Where did this document come from?”
For the first time in my life, my mother looked genuinely terrified.
Because now this wasn’t simply a family dispute over money.
Someone had submitted a document that appeared to authorize the sale of my house using a signature I hadn’t written.
And Vanessa, who had laughed when I walked through the door, suddenly looked as if she might be sick.
The next question was no longer who had sold my house. It was who had created the document—and whether the $214,000 debt had been the real reason for the scheme at all.
Richard didn’t accuse my mother of forgery that afternoon.
He was too careful for that, and I was grateful. A suspicious document was not proof of who created it. We needed the original, a proper review, and a clear record of what had happened.
But the document changed the way everyone behaved.
Mom stopped insisting that she had the right to sell my house.
Vanessa stopped talking about how lucky she was to be debt-free.
And I stopped pretending that a calm conversation would somehow make everything right.
Richard asked everyone to remain seated while he explained the immediate situation.
“The title company has not completed the transfer,” he said. “The property remains in Emily’s name. Until the disputed authorization is investigated, no one should attempt to close the sale, transfer additional funds, or alter any property records.”
Mom folded her arms.
“So you’re saying the sale can still happen?”
“I’m saying the sale cannot proceed on the current documentation. Emily has not authorized it.”
“But the buyer has already paid a deposit!”
“Then the buyer and the title company will address the deposit according to the purchase agreement and applicable law. That does not give you authority to sell someone else’s property.”
Mom looked at me.
“Emily, please. You can stop this.”
I shook my head.
“I can’t stop an investigation into a document I didn’t sign.”
Vanessa began crying.
It was the first time I’d seen her cry that day, and I knew the tears weren’t only about the house.
Her $214,000 debt was real.
She had accumulated it through years of overspending, unpaid taxes on a small business that failed, high-interest credit cards, and personal loans she kept refinancing instead of repaying. She’d hidden the full amount from her husband until the collection notices became impossible to ignore.
Mom had found out about the debt six months earlier.
Instead of helping Vanessa confront the problem, she had promised to make it disappear.
That promise had become the foundation of everything that followed.
“Where did you get the buyer?” I asked.
Mom stared at the table.
“Someone I knew.”
“Who?”
“A man named Gregory. He buys properties.”
“Did he know you weren’t the owner?”
“He knew I was handling things for the family.”
“Did you tell him I had given you permission?”
Mom rubbed her forehead.
“I told him we had an arrangement.”
“That isn’t an answer.”
Richard intervened before the argument could escalate.
“We’ll need the buyer’s identity and all communications about the transaction. Emily, please don’t sign anything or agree to any new arrangement until we’ve reviewed the records.”
I nodded.
Then he asked Mom whether she had copies of the messages and documents she’d exchanged with Gregory.
She said she did.
Richard requested that she preserve them and provide copies to the appropriate parties. He also advised us to document any money already transferred and to avoid moving or concealing funds while the dispute was being investigated.
The title representative left after confirming that the transaction would remain on hold pending review.
Richard stayed long enough to explain our next steps, then promised to contact us the following morning.
When the door closed behind them, the house felt strangely quiet.
Mom sat down heavily.
Vanessa stared at her phone.
I picked up my suitcase and carried it into the bedroom.
My bedroom.
My furniture was still there. My clothes were still in the closet. The framed photograph of my grandmother still sat on the dresser.
For a moment, I needed to see those ordinary things to remind myself that I hadn’t lost everything simply because my mother had announced that I had.
When I returned to the kitchen, Vanessa was standing by the window.
“Emily,” she said quietly, “I didn’t know about the signature.”
I looked at her.
“Did you know Mom was trying to sell the house?”
She hesitated.
“Yes.”
“Did you know I hadn’t agreed?”
Her eyes filled.
“Mom said you would agree once you understood how bad things were.”
“That isn’t the same as asking me.”
“I know.”
“Then why did you laugh when I came home?”
She looked away.
“I was relieved. I thought everything was finally going to be okay.”
“You were relieved because you believed my house had been sold to pay your debts.”
“I wasn’t thinking about it that way.”
“How were you thinking about it?”
She didn’t answer.
I realized then that Vanessa had spent so many years treating our mother’s promises as guarantees that she had stopped asking whether those promises were fair to anyone else.
Mom had always rescued her.
When Vanessa failed a class, Mom blamed the teacher. When her first business collapsed, Mom said her partners had betrayed her. When she accumulated debt, Mom insisted she had simply been unlucky.
And when I succeeded, Mom treated my success as evidence that I could absorb the consequences of Vanessa’s choices.
I had enabled that pattern, too.
Every time I paid an overdue bill to prevent an argument, every time I lent Vanessa money without asking for a repayment plan, every time I let Mom call me selfish until I gave in, I had helped make the next demand seem reasonable.
But I had never agreed to give away my house.
That boundary was not negotiable.
“I’m not going to throw you out of my life,” I told Vanessa. “But I will not cover your debts by surrendering my property. If you want help, we can discuss realistic options. You need to be honest about what you owe and what you can afford.”
She nodded, wiping her face.
“And Mom?”
“I don’t know yet.”
That night, I stayed in my own bedroom while Mom and Vanessa slept in the guest room and on the living room sofa. I didn’t offer them a permanent place to stay. They had arrived expecting me to be the one without a home, and I needed time to decide what kind of relationship I could have with either of them after this.
The following morning, Richard called.
He had reviewed the initial purchase documents and spoken with the title company. The transaction had been flagged because the seller’s authorization did not match the ownership records.
The company had also noticed that the notary information on the authorization appeared inconsistent with the date on the document.
That was enough to stop the closing, but it was not enough to establish who had prepared the paperwork.
Richard explained that the next step was to obtain the original document and have the signature and notarization examined. We would also need to establish what Mom had told Gregory and what Gregory had believed when he agreed to purchase the property.
I agreed to cooperate fully.
Then Richard asked whether my grandmother had ever left me any documents concerning the house.
I thought about it.
My grandmother had helped me with the down payment eleven years earlier, but the house had been purchased in my name. She had given me money as a gift, and I had retained the records.
After her death, Mom had sometimes spoken as if Grandma had wanted the house to remain in the family. She’d never produced a will or trust giving her control over it.
I told Richard exactly that.
He asked me to find the original purchase documents and any records relating to the down payment.
I spent the afternoon going through a filing cabinet in my home office. Inside were mortgage statements, property tax records, renovation invoices, insurance documents, and the closing papers from when I had purchased the house.
There was no ambiguity about ownership.
The deed listed me as the sole owner.
The mortgage was in my name.
The property taxes came from my account.
The house was mine.
I scanned the documents and sent them to Richard.
Two days later, the situation became more complicated.
Gregory, the prospective buyer, contacted Richard through his own attorney. He claimed that my mother had represented herself as authorized to arrange the sale and had supplied documents to support that claim.
He said he had believed the transaction was legitimate.
He also confirmed that he had not received a deed transferring ownership to him.
That meant he did not own my home, despite my mother’s announcement.
But the deposit remained an issue.
Some of the funds had been paid to an escrow account, while other payments were described in messages as advances toward the transaction. The parties would need to determine exactly where the money had gone and whether any of it could legally be retained.
Richard asked me to stay out of direct negotiations with Gregory.
“Let the attorneys handle it,” he advised. “You don’t need to solve everyone else’s financial problem before we establish what happened.”
For once, I listened.
The next week, the original authorization was obtained for review. The signature did not match my known signatures, and the notary information raised further concerns. The matter was referred to the appropriate authorities for investigation.
I was careful not to assume I knew who had created it.
I knew my mother had arranged the sale. I knew she had supplied the paperwork. I knew I had never signed the authorization.
Everything else needed to be established through evidence.
Then Vanessa made a discovery of her own.
She found an email exchange between Mom and Gregory that had been overlooked in the first review.
In one message, Gregory had asked whether the property was subject to any ownership restrictions or family claims.
Mom had replied that she was “handling the family side” and that I would sign the final papers when I returned.
There was no indication that I had agreed to do so.
The email didn’t prove who had created the disputed signature, but it contradicted Mom’s repeated claim that I had already authorized the sale.
Vanessa printed the exchange and brought it to me.
“I thought you should have this,” she said.
I accepted the pages.
“Thank you.”
She looked as though she wanted to say more.
Finally, she admitted, “I knew you hadn’t signed anything. I thought you would be angry, but I didn’t think Mom would go this far.”
I studied her face.
“Why didn’t you call me?”
“Because I was ashamed. And because Mom kept telling me that if I asked you, you’d say no.”
She swallowed.
“I didn’t want to hear no.”
It was the most honest thing she’d said since I returned.
I didn’t excuse what she’d done. She had knowingly benefited from a plan involving property she had no right to claim. But I could finally see the difference between the sister who had laughed at my misfortune and the woman who was beginning to understand how much damage our mother’s behavior had caused.
That didn’t erase her responsibility.
It gave her a choice about what to do next.
Vanessa contacted a nonprofit credit counselor and began organizing her debts. Her counselor helped her list each creditor, interest rate, and repayment obligation. She also spoke with an attorney about her options and learned that paying off a debt through an unauthorized property sale was not a substitute for a legitimate repayment plan.
Her $214,000 problem did not disappear overnight.
She still had to negotiate with creditors, reduce expenses, and decide whether a formal debt-relief process was necessary. But for the first time, she was dealing with the problem herself rather than waiting for Mom to make another promise.
Mom, meanwhile, began calling me every evening.
At first, she was angry.
She said I’d embarrassed her. She accused Richard of frightening her. She insisted Gregory had misunderstood her intentions.
Then her tone shifted.
“Emily, I never wanted you to lose your house,” she said during one call.
“You told me I was homeless.”
“I was upset.”
“You were celebrating.”
She went quiet.
“I thought if the house sold, Vanessa could finally breathe.”
“And what did you think would happen to me?”
“I thought you’d find somewhere else.”
The casualness of that answer hurt more than the insults.
“You thought I’d simply find somewhere else to live,” I repeated.
“You have a good job. You can afford another place.”
“Mom, a house isn’t just a number on a bank statement. It’s my home. It’s where I’ve lived for eleven years. You didn’t get to decide I could lose it because Vanessa had a financial crisis.”
She began crying.
“I was trying to save your sister.”
“Then you should have helped her make a plan. You should never have tried to sell my property.”
For the first time, she didn’t argue.
The investigation continued for several weeks. During that time, the proposed sale remained uncompleted. The buyer’s deposit was dealt with through the appropriate legal process, and the title company refused to proceed without valid authorization from me.
Eventually, the purchase agreement was canceled.
My attorney confirmed that the house remained in my name and that no transfer of ownership had occurred.
The disputed authorization was included in the ongoing investigation. I did not receive a dramatic confession from someone standing in my kitchen, and I did not pretend the matter was resolved simply because the sale had failed.
There were still questions about the document’s origin and the movement of funds.
Those questions belonged with the professionals handling the case.
But one thing was settled: my mother had not succeeded in making me homeless.
A month after I returned from Hawaii, I invited Vanessa to meet me at a coffee shop.
She arrived with a folder of papers and a notebook.
“I’ve made a budget,” she said. “And I listed every debt. I also called the creditors who were willing to discuss payment arrangements.”
I looked through the pages.
The numbers were difficult, but the plan was realistic. She had canceled unnecessary subscriptions, sold a second car, and arranged to take on additional work while she looked for a more stable position.
“I can’t promise I’ll fix everything quickly,” she said. “But I don’t want to keep asking you to rescue me.”
“That is a good place to start.”
She looked down at her coffee.
“I’m sorry I laughed when you came home.”
I let the silence settle between us before answering.
“That hurt more than you realize.”
“I know.”
“No, Vanessa. I don’t think you did then. I think you believed that because Mom had promised you something, you were entitled to it.”
She nodded, tears gathering in her eyes.
“I did.”
I accepted her apology, but I didn’t offer her money. We agreed that if I helped in the future, it would be through clearly defined arrangements that I could afford, with no pressure and no assumptions.
She accepted those terms.
Our relationship improved slowly. We began having conversations that weren’t about money. She asked about my vacation. I asked about her children. Sometimes we laughed about old memories, and sometimes we disagreed.
But the rules had changed.
Mom took longer to accept that change.
Eventually, she sent me a handwritten letter.
She wrote that she had spent years believing she could solve every problem by protecting Vanessa from consequences. She admitted that she’d treated my independence as proof that I didn’t need protection, and my success as proof that I could afford whatever she demanded.
She didn’t ask me to drop the matter or to cover Vanessa’s debt.
She simply apologized for treating my home as something she could give away.
I didn’t forgive her immediately.
Trust doesn’t return because someone finally says the right words. It returns when their actions begin to match those words.
Over the next several months, Mom stopped making financial promises on my behalf. When she wanted to visit, she asked. When she wanted help, she explained what she needed and accepted that I might refuse.
We began rebuilding our relationship, carefully and without pretending the past had vanished.
I also made changes of my own.
I updated my estate documents, secured my property records, reviewed my financial accounts, and made sure no one else had authority to act on my behalf without explicit written permission. I kept copies of everything related to the attempted sale.
Those weren’t acts of revenge.
They were acts of responsibility.
One Saturday afternoon, I stood in my kitchen, the same kitchen where Mom had once raised her champagne glass and announced that I was homeless.
Sunlight fell across the table.
My suitcase was long unpacked. My house was still mine. The framed photograph of my grandmother remained on the dresser, and the rooms that had once been the subject of a family argument were filled with the life I’d built there.
I thought about how easily my mother had dismissed everything I’d worked for.
She’d seen a valuable property and a daughter who could supposedly recover from losing it. She’d seen Vanessa’s debt as an emergency that justified any sacrifice, provided the sacrifice belonged to someone else.
She’d mistaken my patience for permission.
And she’d mistaken my silence for weakness.
When I laughed that day, I hadn’t laughed because I was certain everything would work out. I laughed because, for once, I understood that I didn’t have to argue with someone who had already decided I didn’t matter.
I could let the paperwork speak.
I could protect my home.
I could refuse to carry a debt I had never created.
My mother had wanted a simple ending: Vanessa’s debt paid, the house sold, and me quietly moving on.
Instead, the attempted sale was stopped, the documents were investigated, and the family was forced to confront the difference between helping someone and sacrificing another person without their consent.
Vanessa still had a long financial road ahead of her. Mom still had work to do to earn back my trust. And I still had moments when I wondered whether our family would ever feel as uncomplicated as it once had.
But I was no longer afraid of setting boundaries.
Because the most important thing that paper on the kitchen table had represented wasn’t a legal threat or a clever revenge plan.
It was proof.
Proof that my home was mine.
Proof that I had the right to say no.
And proof that love, no matter how often someone invokes it, does not give them permission to take what belongs to you.
They had celebrated my supposed downfall before checking the facts. By the time they understood what they’d done, the house was still mine—and the power to decide what happened next had never belonged to them.