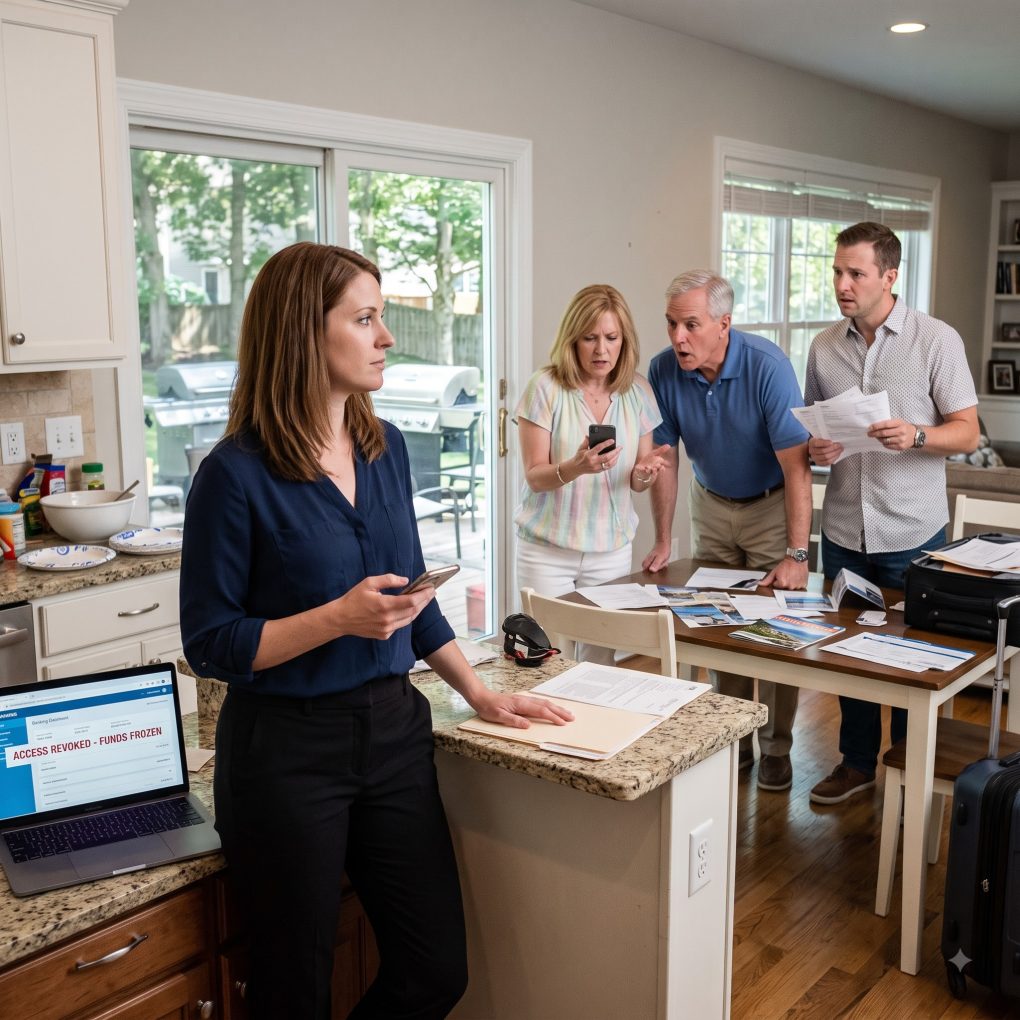
“They laughed when Dad said the vacation was without me. 5 days later, Mom tried to withdraw $6,800 and saw four words on the screen.”
“THE VACATION IS FOR FAMILY, WITHOUT YOU.”
My father said it loud enough for all twenty people at our backyard barbecue to hear.
Then my brother, Tyler, raised his beer and laughed.
Mom laughed, too. So did my aunt. Even my cousin, who’d borrowed money from me last month, suddenly found the joke hilarious.
I stood beside the grill holding a plate of burgers, staring at the people I’d spent the last three years helping financially.
“Dad, I paid the deposit for that vacation,” I reminded him.
He shrugged. “You paid into the family fund. That doesn’t mean you get to control every family decision.”
Tyler grinned. “Maybe if you weren’t so obsessed with money, people would actually want you around.”
More laughter.
I could have reminded them that I’d covered Mom’s property taxes twice, paid Dad’s insurance when his business struggled, and deposited $1,500 every month into the shared account they called our family fund.
Instead, I nodded.
“Got it.”
Dad smiled like he’d won.
Five days later, Mom called me at 9:17 a.m.
“Something’s wrong with the account,” she snapped. “My withdrawal for $6,800 was declined. Fix it immediately.”
I was sitting at my desk in my apartment in Denver, reviewing the account dashboard.
The $6,800 wasn’t for groceries or an emergency. It was the balance due on the luxury family vacation in Hawaii—the same trip I’d been told I wasn’t welcome on.
“I thought the vacation was for family,” I said quietly.
Mom went silent.
Then she hissed, “Don’t you dare punish everyone because your feelings got hurt.”
I opened the account settings.
The family fund had been in my name because my credit score was the strongest, and I’d been the one making the deposits. Everyone had access to a separate debit card, but I’d never questioned their purchases. I’d trusted them.
Not anymore.
I froze the remaining transfers, locked the linked cards, and changed the account label from FAMILY FUND to FUND YOURSELVES.
Then I checked the transaction history.
My stomach tightened.
There were withdrawals I didn’t recognize. Payments to a debt collection company. A recurring transfer to an account belonging to Tyler.
And one payment, made just two days earlier, for $18,400.
Before I could open the details, my phone lit up with a call from Dad.
I answered.
His voice was no longer amused.
“Whatever you just discovered,” he said, “you need to put that money back before your brother’s life is ruined.”
I stared at the screen.
“Why would Tyler’s life be ruined by money I never knew I was lending him?”
Dad didn’t answer.
Then I heard Tyler shouting in the background.
“DID SHE FIND THE LOAN DOCUMENTS?”
My blood ran cold.
Because I had never signed a loan.
And someone had just used my name.
A little more was hidden beneath the family’s laughter…
I had thought the worst part was being excluded from a vacation I helped pay for. I was wrong. The account history was only the beginning, and the documents my father was desperate to hide would reveal why my family had suddenly become terrified of losing access to my money.
“Tell Tyler to stop shouting,” I said.
Dad ignored me. “You’ve made your point. Unlock the cards, transfer the money back, and we’ll discuss this like adults.”
“Discuss what? The $18,400 payment? Or the loan documents with my name on them?”
Silence.
Then Dad lowered his voice. “Your brother made a mistake. Families help each other.”
“Did he use my identity?”
“No one used anything. You’re making this sound criminal.”
That answer told me more than a confession would have.
I ended the call and contacted the bank’s fraud department. Because I was the account owner, they could restrict the remaining funds and review the disputed transactions. I asked them to preserve the records and opened a formal dispute over the unfamiliar payments.
The representative also explained that the $18,400 transfer had gone to a lender—not directly to Tyler. The reference number matched a personal loan application.
My name appeared as a guarantor.
I had never applied for that loan.
By noon, I’d frozen my credit with the major credit bureaus and requested copies of my credit reports. I also saved every account statement and message I could find. I wasn’t going to let anyone convince me that my memory was the problem.
Then Tyler texted.
TYLER: You have no idea what you’ve done. They’ll come after all of us.
ME: Who will?
He called immediately.
“Listen,” he said, sounding breathless. “I borrowed money to cover some business expenses. Dad said the family fund could help me until things turned around.”
“Did Dad tell you to put my name on a loan?”
“He said you’d agreed.”
“I didn’t.”
A long pause followed.
Then Tyler said, “Mom handled the paperwork.”
My hands went cold.
Mom had access to the family fund, but she didn’t have permission to borrow money in my name. I asked Tyler to send me every document he had.
He refused.
“You’re going to destroy this family over a signature?” he demanded.
“No. Someone else signed it. I’m trying to find out who.”
That afternoon, an email arrived from the lender acknowledging my fraud report. Attached was a copy of the application.
The signature looked almost exactly like mine.
But the email address used for verification wasn’t mine. It belonged to Dad’s old business.
Then I found another document in the account’s transaction archive: a spreadsheet titled TYLER—PAYBACK PLAN.
It listed the money I’d deposited each month, the amounts transferred to Tyler, and projected future withdrawals from the fund.
At the bottom, someone had typed:
“Once she covers the remaining balance, we can close everything before she notices.”
I read it twice.
They hadn’t simply expected me to keep supporting Tyler.
They’d planned to make me responsible for his debt.
That evening, my parents arrived at my apartment without warning. Dad held a folder against his chest. Mom looked as if she hadn’t slept.
“We can explain,” she said.
I kept the door open but didn’t invite them in.
Dad placed the folder on the entry table.
“Your brother owes more than you think,” he admitted. “And if the lender investigates that application, everything could fall apart.”
“How much?”
He looked at Mom.
She whispered, “Almost sixty thousand dollars.”
Then Dad opened the folder and showed me a second loan application.
This one wasn’t for Tyler.
It was for me.
And the approval notice was dated three weeks before the barbecue.
I stared at the approval notice.
The loan was for $41,600. The application listed my Denver address, my employer, my annual salary, and the last four digits of my Social Security number.
Every detail was correct.
Except the email address, the phone number, and the signature.
“Who submitted this?” I asked.
Mom sat down without waiting for permission. “Your father thought it was the only way to keep Tyler’s business afloat.”
Dad’s jaw tightened. “That is not how it happened.”
“Then tell me how it happened.”
He glanced at the folder. “Tyler’s business was struggling. He had credit card balances, unpaid suppliers, and a lease he couldn’t afford. We were trying to prevent him from losing everything.”
“And you decided to borrow money in my name?”
“We thought we could repay it before you ever knew.”
The words landed harder than any insult at the barbecue.
They hadn’t made a mistake and hoped to fix it. They had made a plan that depended on me remaining unaware.
Mom wiped her eyes. “We were going to use the family fund to make the payments. You’d never have been responsible in the end.”
“That’s what you told yourselves,” I replied. “But if the loan went unpaid, my credit would be damaged. My financial future would be on the line. And you were perfectly comfortable with that.”
Dad leaned forward. “We are your parents.”
“And I was your daughter when you told everyone I wasn’t welcome on the vacation, right?”
Neither answered.
I took the folder, photographed every page, and told them the conversation was over.
Dad stood abruptly. “If you report this, Tyler could lose his business.”
“If I don’t report it, I could be held responsible for a debt I never agreed to.”
“He’s your brother!”
“And I’m your daughter. You seem to remember that only when you need something.”
I closed the door.
For the first time in years, I didn’t feel guilty watching them leave.
The next morning, I spoke with the lender’s fraud investigator. I explained that I had never applied for either loan, never authorized anyone to sign for me, and never agreed to guarantee Tyler’s debts. I provided the application copies, the suspicious email address, and the account statements.
I also filed an identity-theft report and gave the investigator a timeline of what had happened. I didn’t accuse a specific person of forging the signature because I couldn’t prove who had submitted the documents. I let the records speak for themselves.
The bank began reviewing the disputed transactions. The lender marked the loans as contested while its investigation continued, and I followed up in writing to make sure my dispute was documented.
It wasn’t an instant fix. I spent hours answering questions, checking my credit reports, and submitting paperwork. Some of the money already withdrawn from the family fund couldn’t simply be restored on demand. The bank had to determine which transactions were unauthorized, which had been made with cards I had voluntarily allowed relatives to use, and which required a separate dispute.
That distinction mattered.
I had given my family access to a shared spending account. I had never given them permission to borrow in my name.
Three days later, Tyler finally called.
“I need you to withdraw the complaint,” he said.
Not hello. Not I’m sorry.
Just a demand.
“Why?”
“Because the lender contacted me. They’re investigating the transfers, and my business account is under review.”
“Then cooperate with them.”
He exhaled sharply. “You don’t understand. I’m in trouble.”
“Then tell me the truth.”
For several seconds, all I heard was his breathing.
Finally, he admitted that his landscaping business had been losing money for almost a year. He had taken out credit cards to pay employees and equipment leases, then used one loan to cover another. Dad had been helping him juggle the payments. Mom had managed the family fund and believed the money I deposited could keep the whole arrangement alive.
The $18,400 transfer had paid down part of Tyler’s overdue business debt.
The second loan had been intended to cover the rest.
And the spreadsheet I’d found wasn’t a repayment plan for money Tyler had borrowed from the family.
It was a plan to use my monthly deposits to service obligations I didn’t even know existed.
“Dad said you’d help,” Tyler muttered.
“I did help. Every month. You all just decided my help wasn’t enough unless you could take it without asking.”
“I was going to pay you back.”
“With what money?”
He had no answer.
Then came the twist I hadn’t expected.
Tyler confessed that he had known the loan applications used my information. Dad had told him I would agree once everything was explained, and Tyler had convinced himself that a temporary lie was harmless.
Mom, however, had submitted the lender’s verification details through the email account connected to Dad’s former business. Tyler said he hadn’t personally signed the applications, but he had received money from the resulting transfers and used it to cover his debts.
That didn’t establish every detail of who had done what. The investigation would have to determine that.
But it destroyed the family’s favorite excuse: that nobody knew anything.
They had all known enough to benefit.
I told Tyler I would not withdraw my fraud report. I also told him I wasn’t asking for revenge. I wanted the loans investigated properly, my identity protected, and my money accounted for.
“You’re choosing strangers over your own brother,” he said.
“No. I’m choosing not to take responsibility for decisions you made.”
He hung up.
The following week, Dad sent a long email. It began with an apology, then spent six paragraphs explaining how much pressure he’d been under. He described Tyler’s business as the family’s future and claimed he had acted out of desperation.
At the very end, he asked whether I would consider making one more deposit into the fund to cover their immediate expenses.
I almost laughed.
Even his apology came with an invoice.
I replied with three sentences:
The family fund is closed to future deposits. I will cooperate with the bank and lender until the disputed accounts are resolved. I will not pay Tyler’s debts or take out loans for anyone.
Then I stopped answering messages about money.
Over the next several weeks, the consequences became real.
The lender’s investigation continued, and the disputed loans were not treated as ordinary obligations I had willingly taken on. I received written confirmation that my fraud claim had been recorded and instructions for responding if either balance appeared on my credit reports. I checked those reports regularly and challenged anything that did not belong there.
The bank’s review was more complicated. Some transactions had been made using cards I had knowingly given my relatives, so I couldn’t automatically label every withdrawal fraud simply because I regretted allowing access. But the bank identified transactions that required further investigation, and I provided the records it requested.
I recovered some of the money. Not all of it.
I accepted that reality rather than spending another year chasing every dollar through arguments and promises.
Tyler’s business could not survive without outside money. He sold some equipment, renegotiated leases, and arranged a payment plan with several suppliers. He moved into a smaller operation and took a second job while trying to pay down the debts he had accumulated.
Dad stopped pretending that he could solve everything by moving money between accounts. He met with a financial adviser and began separating his finances from Tyler’s.
Mom had to find a way to cover the expenses she had grown accustomed to paying from my deposits.
Their Hawaii vacation was canceled. The travel company applied what it could toward cancellation fees and returned the remaining eligible amount according to its policy. The family argued about who should absorb the loss, but for once, I wasn’t asked to settle the dispute.
My aunt called me a week later.
“You’ve made your point,” she said. “Your mother is devastated. Can’t you just help them get back on their feet?”
I asked her one question.
“If someone used your name to borrow money, would you call reporting it a punishment?”
She went quiet.
“I didn’t create Tyler’s debt,” I continued. “I didn’t apply for those loans. And I didn’t tell Dad to announce at a barbecue that I wasn’t family enough to join a vacation I helped pay for.”
She never asked me to deposit money again.
Two months after the barbecue, Dad requested a meeting at a coffee shop. I agreed, but I made it clear that we would not discuss loans, deposits, or business bailouts.
He arrived alone.
“I was wrong,” he said after we sat down. “Not just about the money. About how I treated you.”
I waited.
He admitted he had relied on me because I was responsible, while excusing Tyler because Tyler was struggling. In his mind, I could always earn more, recover faster, and handle one more burden. Tyler, he said, was the child who needed rescuing.
“So you made me the safety net,” I replied.
Dad nodded. “Yes.”
It was the first honest answer he had given me.
I didn’t hug him or promise that everything was fine. I told him that trust would take time, and that an apology didn’t erase the financial damage. If we were going to rebuild our relationship, he would have to respect my boundaries even when those boundaries inconvenienced him.
He agreed.
Mom’s apology came later. It was shorter and less polished.
“I should never have let you believe your value to us was what you could pay,” she said.
That sentence hurt because it was true.
I told her I wanted a relationship with her, but not one built around automatic access to my paycheck. She would need to ask before expecting financial help, and I would be free to say no without being mocked, threatened, or punished.
She said she understood.
I didn’t know yet whether she truly did.
Tyler sent me a message near the end of the year. He didn’t ask for money. He said he was sorry for helping Dad convince himself that I would never object, and for treating my support like something he was entitled to.
I appreciated the apology.
I didn’t offer to rescue his business.
That distinction became the foundation of my new relationship with all of them: forgiveness could be possible without handing anyone the keys to my finances.
I eventually created a new savings account exclusively for myself. I changed my passwords, enabled additional security measures, and kept my credit frozen unless I needed to apply for something. I stopped treating financial access as proof of love.
The following summer, my family held another barbecue.
Dad called beforehand and asked if I wanted to come. There was no mention of money, no joke about who counted as family, and no assumption that I would pay for the food.
I went.
Tyler was there, talking quietly with Dad about his payment plan. Mom greeted me at the door and asked whether I wanted a plate. Nobody made a speech. Nobody demanded that I pretend the previous year had never happened.
It wasn’t a perfect reunion.
It was simply a beginning.
At one point, Dad raised his glass and said, “I’m glad you’re here.”
I looked around the yard. The same people were there, but the old arrangement was gone. I was no longer the person expected to quietly absorb every expense so everyone else could enjoy themselves.
I smiled and raised my glass.
“Me too.”
The family fund stayed closed. The investigation followed its course, and Tyler remained responsible for the debts connected to his business. My parents had to learn how to live within their own means, and I had to learn that saying no didn’t make me cruel.
They had laughed when Dad told me the vacation was for family without me.
Five days later, they discovered that the money they depended on came from someone they had treated as expendable.
But the most important thing I took away wasn’t the money I recovered or the accounts I froze.
It was the realization that being family does not give anyone the right to use your name, your credit, or your future without your permission.
I had spent years proving I could help them.
Now they had to learn how to respect me when I didn’t.