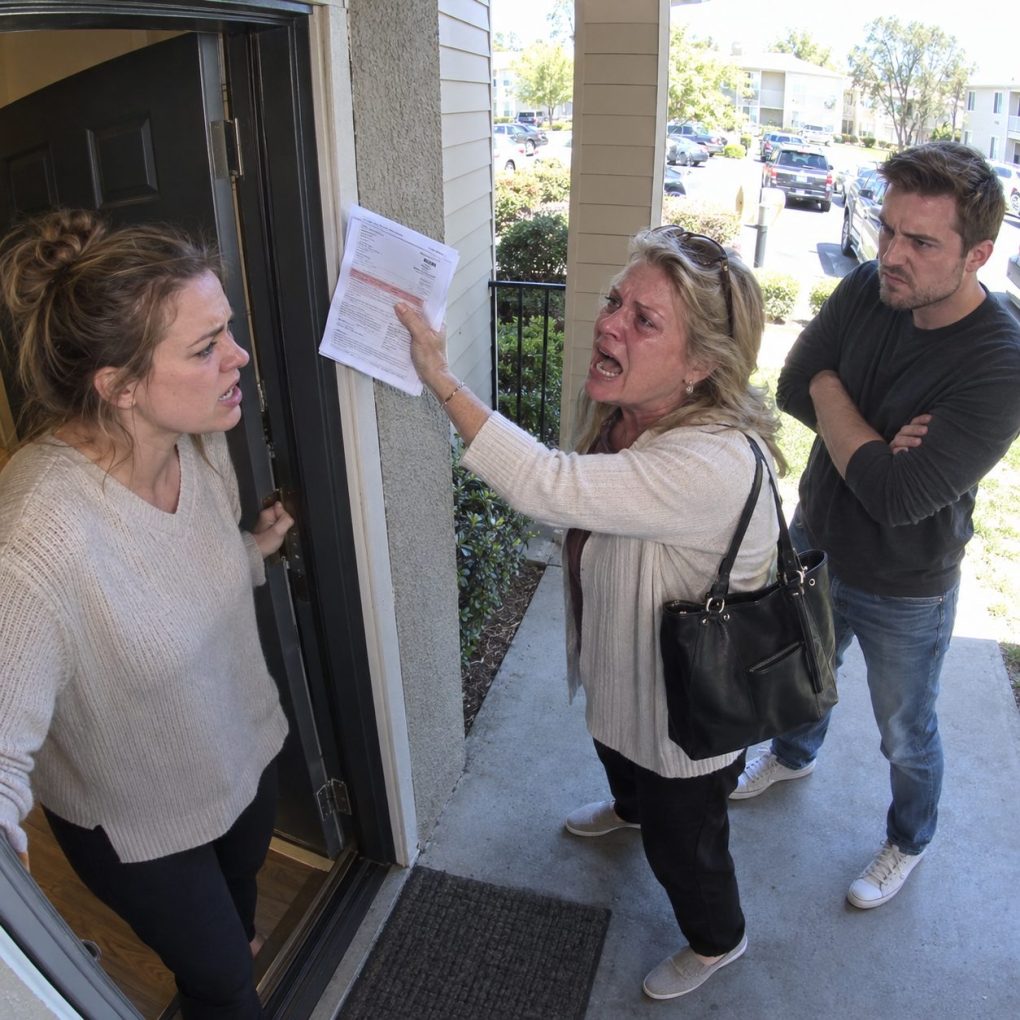
My mother slapped a late-payment notice against my apartment door and demanded $2,480 by Friday. Behind her stood my younger brother, Tyler, with his arms folded. He was the one who would inherit our parents’ house. I was the daughter who had paid its mortgage for fifty-two months. Apparently, stopping made me the villain.
A month earlier, Mom had pushed a folder toward me during Sunday dinner. She wanted me to be executor of her and Dad’s estate because I was responsible. Inside were their updated wills. Tyler would receive the house and whatever savings remained. My name appeared only beside the job of handling the paperwork.
I asked whether something had been left out. Dad stared at his plate. Mom explained that Tyler had two children and a struggling construction business, while I had a steady hospital job and no dependents. Tyler kept chewing. I remember wondering how many bites it took to swallow your sister’s future without choking.
Four years earlier, Dad’s heart surgery had cut his income, and I offered to cover six mortgage payments. Six became twelve, then fifty-two. I had sent $128,960 directly to their lender while living in a one-bedroom rental, postponing dental work and putting my own down payment dreams on hold. They had never offered to repay me.
When I told them I was ending the payments, Mom accused me of putting a price on family. I told her she had done that first. Now, standing in my doorway, she claimed one missed payment would leave them homeless. I suggested calling the lender or selling the oversized house. She said the house was Tyler’s future.
Tyler stepped toward me and asked why I was being cruel to his kids. My throat tightened. I loved my niece and nephew, but I had no ownership, no agreement, and no savings left to burn. I told him that if he expected the house someday, he could help pay for it now. He called me bitter.
I shut the door with my hands shaking. Before I reached the kitchen, my phone flashed a credit-monitoring alert: a $41,700 personal loan was delinquent under my Social Security number. I hadn’t borrowed a cent. The lender’s number was unfamiliar, but the mailing address on the account was my parents’ house.
I called Mom back and told her what I’d found. All the fury went out of her voice. She didn’t ask what loan I meant. She didn’t sound surprised. After a long silence, she asked only whether I’d called the police yet.
I went to the lender the next morning and reported the account as fraud. Someone had applied online eleven months earlier using my personal information and an old email address Mom could access. Her phone number was listed. One missed payment had finally exposed the account.
I froze my credit, filed an identity-theft report, and requested copies of the loan paperwork. Then I drove to my parents’ house. Mom opened the door as though she expected a check. I placed the documents on the table instead. Dad read the first page and lowered himself into a chair.
Mom admitted she had applied for the loan using my information. It had been an emergency, she insisted. Tyler needed equipment for his business, and everyone planned to repay the money before I found out. When I asked why she hadn’t requested my permission, she looked at me as if the question were ridiculous. She knew I would say no.
Tyler came in through the garage and went straight for the papers. He said the money had saved jobs and accused me of turning family trouble into a crime. I asked how much of the $41,700 had gone to employees. He looked at Mom. She looked at Dad. Nobody looked at me.
Dad finally admitted he had known about the application. He’d called it temporary, just like my mortgage payments. I reminded him how I’d sat beside his hospital bed, terrified of losing him. He started crying. I couldn’t. I felt too empty.
Mom offered to rewrite the wills, splitting everything equally, if I withdrew my complaint. Her offer hurt worse than her lies. It proved she still thought my trust had a price. I told her I didn’t want the house. I wanted my name off a debt I hadn’t agreed to carry.
That evening, Tyler sent seventeen messages, warning that an investigation would bankrupt his business. I saved them. Later, Dad called from his car. He wanted to show me statements Mom had hidden. They’d taken a $68,000 home-equity line of credit, mostly for Tyler, and the interest was draining their retirement income.
We met outside a grocery store. The statements showed transfers to Tyler, truck payments, and unexplained cash withdrawals. But Dad had brought something else: a letter Mom had drafted for me to sign, acknowledging the entire personal loan as mine. My name was already typed beneath the statement.
A chill spread through me as I read it. Mom hadn’t just stolen my identity once. She had prepared a way to make me accept the debt forever. Then Dad unfolded one last sheet: a budget that included my mortgage payments for the next twelve years, beside a single handwritten note—Tyler keeps the house.
I read that budget three times in the grocery-store parking lot. Mom had listed my salary and the payments she expected until Dad turned eighty. Tyler’s column showed nothing. I had spent years thinking my parents were surviving a crisis. They had been designing a future that required me never to stop paying.
Dad told me Mom had made the spreadsheet after Tyler’s business lost its biggest contract. She called my income dependable and his prospects promising. Dad had signed off on the home-equity borrowing because he believed Tyler would recover. For the first time, Dad admitted he’d helped make it happen.
I asked him to give the statements and drafted acknowledgment to the investigator, not just to me. He hesitated. His testimony could expose Mom, and himself, to consequences. I told him I wouldn’t lie to protect anyone anymore. Two days later, he made a statement and handed over the documents.
The investigation lasted months. The lender reviewed the application and transfers, then formally removed my responsibility for the fraudulent loan and corrected the credit reporting. Mom eventually accepted a plea agreement that included probation and court-ordered restitution. I didn’t celebrate. I had wanted a mother who would protect my name, not a judge who had to.
The financial consequences arrived without drama or mercy. Between the regular mortgage, the home-equity balance, and their other expenses, my parents could no longer afford the house. They sold it before foreclosure became a real possibility. After closing, they had just enough for a rental deposit and modest savings.
Tyler protested the sale more loudly than anyone. He kept calling it his inheritance even though he had never owned a brick. His contracting business closed, and he took a job managing inventory for a building supplier. He sold the truck. I hoped he would grow up, but I stopped measuring my life by whether he did.
I never recovered the $128,960 I had voluntarily paid toward the mortgage. Nobody could return the years of skipped trips, worn-out shoes, and postponed dreams. Accepting that loss was painful. Sending another payment to avoid an argument would have cost me even more.
The day before the movers arrived, I went back for the childhood photographs Dad had saved. Mom waited in the empty dining room, holding a revised will. Whatever little they had left would now be divided equally, she said. She seemed to think those words erased everything. I asked her to put it away.
She asked how I could abandon them after everything they’d done for me. My voice broke as I reminded her that I’d helped because I loved them. She answered that she’d leaned on me because I was the strong one. That was the moment I finally understood: they had mistaken my ability to endure pain for permission to cause it.
Dad walked me to my car and apologized without asking me to forgive him. We speak occasionally, without money between us. Mom sends cards I don’t always open. My credit is clean, my savings are growing, and I have begun looking at small houses. On the first of every month, I still make a payment—straight into an account for a home that will actually be mine.