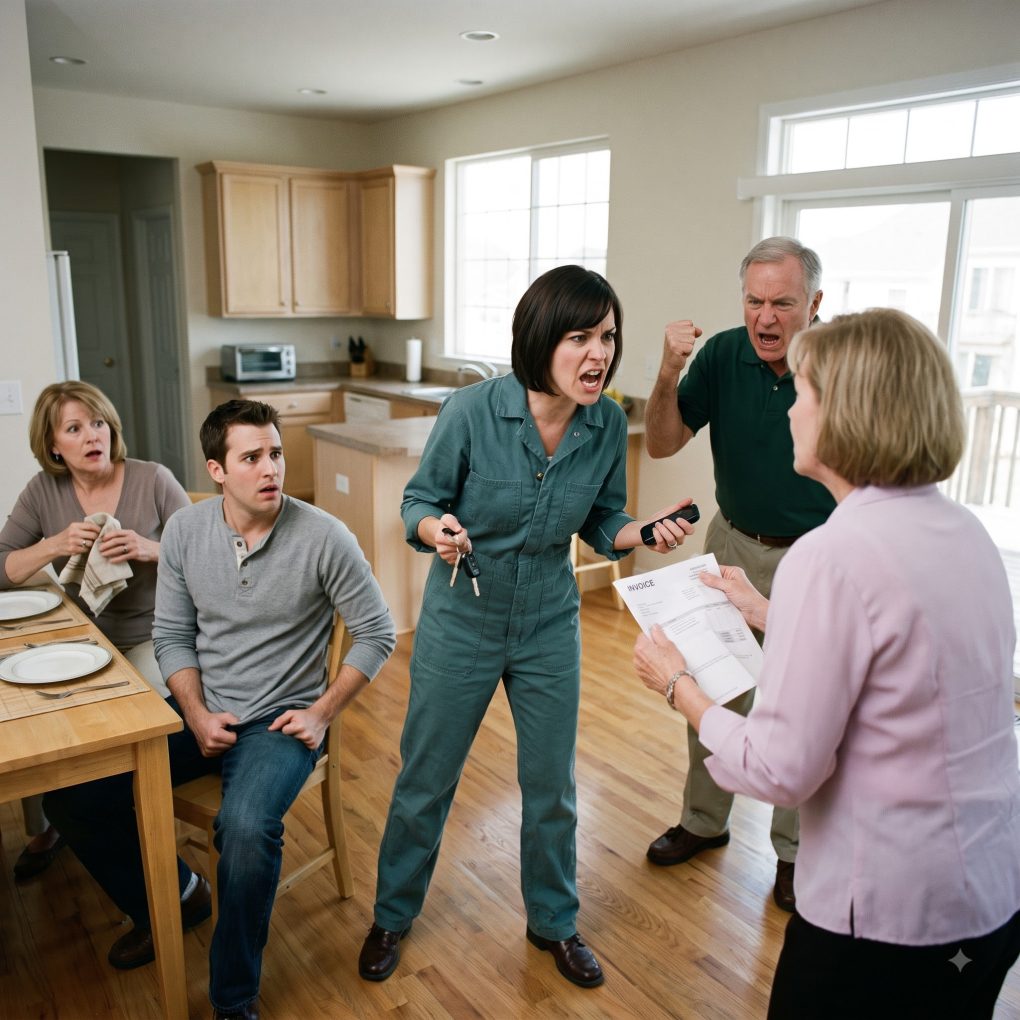
“Thirty thousand dollars in back rent,” my mother announced, sliding a handwritten bill across the kitchen counter. “And fifteen percent interest every month, just like real landlords.” Dad folded his arms and added, “Pay five thousand today or sell your car.” I stood up slowly. “You really want to do this?” They laughed.
My name is Natalie Brooks, and I’m thirty-four years old. For three years, I’d lived in my parents’ Charlotte, North Carolina, home while helping them recover from serious financial problems. They called me their unsuccessful daughter because I wasn’t married and hadn’t purchased my own house.
What they conveniently forgot was that I’d saved their home from foreclosure. When Dad lost his construction management job, I contributed eighty-eight thousand dollars from my savings to cover overdue mortgage payments and essential repairs. My attorney documented the money as a loan, secured by a recorded deed of trust.
Our written arrangement allowed me to live there without rent while I covered utilities and helped with maintenance. My parents agreed to repay the loan when they sold or refinanced the property. Everyone signed the documents, and for three years, nobody questioned the arrangement.
Then my younger brother, Brandon, announced plans to open another restaurant. His previous business had failed, but Mom insisted he deserved another opportunity. When I refused to invest, my parents suddenly decided I owed them three years of imaginary rent, plus outrageous monthly interest.
I reminded Dad about the eighty-eight thousand dollars. He laughed and said family loans didn’t count because I’d been living under their roof. Mom claimed the new charges would teach me financial responsibility, then threatened to have my belongings placed outside if I refused.
I didn’t scream or beg. I photographed their ridiculous invoice, collected my car keys, and told them any future communication about money would go through my attorney. Dad shouted that I wouldn’t survive a week without them, while Mom called me an ungrateful daughter.
That evening, I checked into a hotel and called my friend Sarah. She offered me her spare bedroom until I found an apartment. I returned the following day with professional movers, collected my belongings by agreement, and left my house key behind.
Seven days later, my phone displayed thirty-seven missed calls from my parents. They’d contacted Sarah, questioned my coworkers, and even called my office receptionist. At first, I thought something terrible had happened, until a voicemail from an unfamiliar real estate agent explained everything.
My parents had secretly listed their house for sale. A buyer was ready, but the title company had discovered my recorded eighty-eight-thousand-dollar loan. The sale couldn’t close with that debt unresolved. Suddenly, I understood why my parents were desperately searching for me. They didn’t need their daughter back. They needed my signature.
The real estate agent, Karen Mitchell, sounded uncomfortable when I returned her call. She explained that my parents had accepted an offer of four hundred and ten thousand dollars. The buyer expected a clean title, but my recorded deed of trust had to be satisfied before the transaction could close.
I asked whether my parents had mentioned the loan. Karen admitted they’d described it as an informal family arrangement that I’d supposedly agreed to forgive. I told her no such agreement existed and referred her to my attorney, Michael Grant, who had prepared the original documents.
Michael reviewed the sale information and confirmed that my secured loan remained enforceable. The documents required repayment when the property was sold, and my parents couldn’t simply declare the debt canceled. He advised me not to sign any release until the title company arranged full payment.
That afternoon, Mom finally left an honest voicemail. She said Brandon had already signed a lease for his new restaurant and needed money immediately. My parents had promised to finance his business using the proceeds from their house, apparently assuming I’d quietly surrender my eighty-eight thousand dollars.
I called Brandon directly. He admitted that Mom had told him I was making up the loan to punish the family. When I sent him copies of the signed agreement and recorded documents, he went silent. Then he asked whether I could forgive the debt as a wedding gift to nobody.
I nearly laughed at the absurdity. Brandon wasn’t getting married, and his restaurant had nothing to do with my financial security. I reminded him that the money represented years of savings, overtime, and sacrifices I’d made while helping our parents keep their home.
Two days later, Dad appeared outside my office building. He demanded that I release the lien immediately, claiming I was preventing him from selling his own property. I told him he was free to sell, but repayment of a legitimate debt wasn’t optional.
Dad’s face reddened. He accused me of abandoning my parents and threatened to send his thirty-thousand-dollar rental invoice to a collection agency. I reminded him that we’d signed a written occupancy agreement and that his sudden retroactive charges had no basis in our arrangement.
That evening, Michael sent my parents a formal letter explaining the loan terms and requesting that all further financial communications go through his office. He also offered to coordinate directly with the title company so repayment could occur from the closing proceeds. I wanted my money returned, not revenge.
The following morning, Mom sent me a photograph of Brandon standing inside his empty restaurant. Beneath it, she wrote that my selfishness would destroy his future and leave my parents homeless. Then she added something that made my stomach twist: they’d already spent most of their savings preparing for a move they could no longer afford.
I didn’t respond to Mom’s message immediately. Instead, I sat with the discomfort of knowing my parents had created another financial crisis while blaming me for refusing to rescue them. They’d risked their home once before, and now they were treating my life savings as money Brandon deserved.
Michael reviewed the property’s estimated sale proceeds with the closing attorney. After the existing mortgage, ordinary selling expenses, and my eighty-eight-thousand-dollar loan were paid, my parents would still receive a substantial amount. They weren’t losing everything, despite the frightening story Mom had been telling relatives.
I sent Brandon the figures and explained that my parents had chosen to promise him money they didn’t actually have available. He became defensive at first, insisting that his restaurant needed immediate funding. Then he admitted he’d known about the planned sale before my parents presented their rental demand.
That admission hurt more than I expected. Brandon had watched our parents threaten to throw me out while knowing they needed my cooperation for the sale. He apologized for remaining silent, but I told him that accepting an apology didn’t mean financing another risky business.
A week later, Mom requested a meeting with Michael present. She arrived looking exhausted, with Dad following several steps behind. For the first time, neither mentioned rent, interest, or my car, and Dad admitted they’d invented the thirty-thousand-dollar demand to pressure me into giving up part of the loan.
Mom began crying and said she’d been terrified Brandon would fail again. I asked why protecting him always required sacrificing me. She couldn’t answer, and Dad finally acknowledged that I’d helped save their house while they treated my generosity as something they were entitled to.
We agreed that the sale could proceed if the title company paid my loan directly from the closing proceeds. Michael coordinated the necessary documents, ensuring the release would become effective only as part of the properly funded transaction. I didn’t waive a dollar, and my parents received the remaining proceeds.
The closing happened three weeks later without another confrontation. When the eighty-eight thousand dollars reached my account, I felt relieved rather than victorious. I’d recovered the money, but no bank transfer could erase the memory of my parents laughing while threatening to throw me out.
I rented a bright two-bedroom apartment near my office and began saving toward a home of my own. Dad eventually apologized without making excuses, and Mom started respecting my requests for space. Brandon postponed his restaurant plans after a lender rejected his projections, and he returned to full-time employment.
Six months after that terrible dinner, Mom invited me to Sunday lunch. I declined politely because I wasn’t ready to pretend everything was normal. My parents had demanded thirty thousand dollars for the privilege of living under their roof, forgetting that I’d once paid eighty-eight thousand dollars to save it. They spent a week searching everywhere for me because they needed my signature. But the daughter they found afterward was different. She still loved them, but she would never again confuse love with unlimited access to her money.