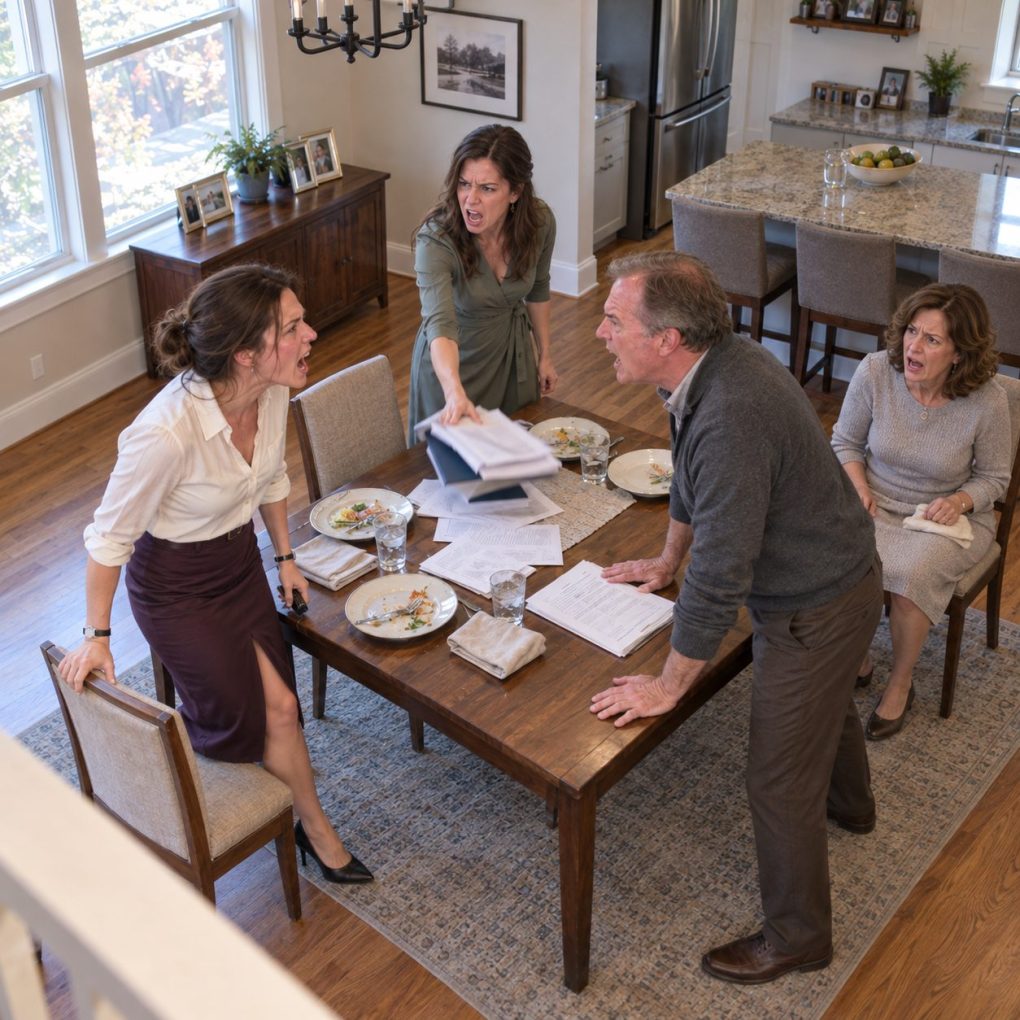
“Your sister owes $240,000. You’re going to pay it,” my father announced, slamming a folder onto the dining table. My mother nodded as though he’d asked me to buy groceries. When I refused, Dad leaned closer and said, “If you don’t pay, you’re not our kid anymore.” I looked at both of them. “Then I guess I’m not.”
My name is Claire Bennett, and I’m thirty-five years old. I work as a financial analyst in Denver, Colorado, and I’ve spent most of my adult life rescuing my younger sister, Megan. She’s thirty-one, unemployed again, and somehow always manages to turn her mistakes into my responsibility.
This time, Megan had borrowed $240,000 through several business loans and private financing agreements. She’d opened a luxury beauty studio without researching expenses, then spent thousands renovating a building she didn’t own. Six months later, the business collapsed, leaving her creditors demanding repayment.
My parents, Robert and Linda, invited me to dinner under the pretense of celebrating my recent promotion. Instead, Megan sat crying beside Mom while Dad presented a spreadsheet outlining how I could liquidate my investments. He’d already calculated my savings, retirement contributions, and estimated home equity.
I asked whether Megan had personally guaranteed the loans. Dad admitted she had, then suggested I refinance my townhouse to cover the balance. When I pointed out that I hadn’t signed anything, Mom accused me of caring more about money than family.
Then Dad revealed something that made my stomach turn. Two years earlier, I’d established a $90,000 savings account to help my parents with future medical expenses. They had begun describing that money to Megan’s lenders as proof that the family could support her debts.
I reminded them the account belonged exclusively to me. Dad shrugged and said I’d promised to take care of the family. Megan finally spoke, insisting that I could rebuild my savings while she had nothing left to lose.
I stood, collected my handbag, and told them I wouldn’t sacrifice my home or retirement for debts I hadn’t created. Dad shouted that I was no longer welcome in his house. Mom watched silently as I walked out, while Megan screamed that I’d destroyed her future.
That night, I called my bank and requested a review of every account connected to my family’s financial arrangements. I revoked an old limited authorization allowing Dad to obtain information about the medical savings account. I also transferred the funds into a new account under my sole control.
Seven days later, my doorbell rang repeatedly. Through the camera, I saw my parents, Megan, two aunts, and my uncle standing on my porch. Dad held a stack of papers, and Mom was crying. I opened the door just enough to face them. “You missed your chance.”
Dad immediately demanded to know why the bank had refused to confirm the availability of my savings. Megan stood behind him, pale and furious, clutching a letter from one of her lenders. Apparently, she’d told a creditor that my money would be available to help settle her debts.
I asked everyone to leave except my parents and Megan. My uncle objected, claiming family problems required family solutions, but I refused to discuss my finances with an audience. After several uncomfortable minutes, the relatives walked back to their cars.
Dad handed me the lender’s letter. It stated that Megan had submitted a personal financial statement listing anticipated family assistance of $90,000. The lender wanted clarification because the promised contribution had never materialized, and Megan’s proposed repayment plan depended on it.
I looked directly at Megan and asked whether she’d used my name without permission. She admitted she’d told the lender I was helping, but insisted she never meant to deceive anyone. Dad interrupted, saying the family had always intended to persuade me eventually.
That was when I understood how far they’d gone. They hadn’t simply asked me to rescue Megan after her business failed. They’d already built a financial plan around money I had never agreed to contribute, assuming emotional pressure would force me to cooperate.
I told them my bank had removed Dad’s information-access authorization and that no family member could discuss my accounts on my behalf. I’d also instructed my financial adviser to stop sharing account summaries with my parents. Dad accused me of treating him like a criminal.
Mom began crying and explained that she’d personally guaranteed a separate $45,000 loan for Megan’s studio equipment. If Megan defaulted, the lender could pursue Mom under that guarantee. For the first time, I understood why my parents were so desperate.
I asked why they’d hidden the guarantee during our original dinner. Mom admitted she feared I’d refuse immediately if I knew she’d willingly signed for Megan’s business. I told her that concealing the truth had destroyed whatever trust remained between us.
Megan suddenly demanded that I sell my townhouse. She said I had a successful career and no children, so losing my home wouldn’t hurt me as much as losing her business had hurt her. Dad didn’t challenge her, and Mom stared at the floor.
I stepped backward and told them the conversation was over. Before closing the door, I said I’d consider helping Mom understand her legal obligations, but I wouldn’t pay Megan’s debts. That evening, I received an email from the lender containing a document I had never seen before, bearing my name beneath a supposed promise of financial support.
The document was a one-page statement claiming I intended to contribute $90,000 toward Megan’s repayment plan. My name appeared in a typed signature block, but the signature wasn’t mine. I immediately forwarded it to my attorney, Rebecca Hayes, and asked the lender to preserve the original submission records.
Rebecca explained that the document didn’t automatically make me responsible for Megan’s loans. However, someone had apparently represented my financial intentions without authorization, which required immediate correction. She prepared a written notice stating that I had never promised payment or authorized anyone to sign for me.
The lender acknowledged my notice and removed the anticipated contribution from Megan’s proposed repayment plan. Its compliance department began reviewing how the document had been submitted. I didn’t know who had prepared it, and Rebecca warned me against making accusations without evidence.
Three days later, Megan called and admitted she’d created the statement herself. She claimed she believed I’d eventually agree to help because our parents had always convinced me before. I told her that using my name without permission was not a misunderstanding, and I saved the conversation details for Rebecca.
Megan began crying and said her creditors were threatening legal action. I suggested she consult a bankruptcy attorney and a qualified debt adviser to understand her options. She accused me of abandoning her, but I reminded her that refusing to assume her debts wasn’t the same as causing them.
Meanwhile, Mom finally met with an attorney about her $45,000 guarantee. She learned that her liability depended on the contract she’d signed, not on whether she could persuade me to rescue Megan. Dad admitted he’d encouraged her to guarantee the loan because he believed Megan’s business couldn’t fail.
For several weeks, my parents barely contacted me. Then Dad sent a letter acknowledging that he’d used our relationship as leverage to demand money. He admitted that threatening to disown me had been cruel and that he’d treated my savings as though they belonged to the entire family.
I didn’t immediately forgive him. Instead, I explained that any future relationship would require respect for my financial independence and an end to threats, guilt, and secret arrangements. Mom apologized separately, admitting she’d sacrificed our trust because she couldn’t bear watching Megan face consequences.
Megan eventually closed the remaining business accounts and sought professional advice about her debts. The lender continued reviewing the unauthorized statement, and I cooperated through Rebecca without agreeing to pay anything. I also changed my financial arrangements so my parents would never again have access to confidential account information.
Six months later, I hosted a small dinner for friends in my townhouse. As we laughed around the table, I realized how peaceful life had become without constant demands for rescue money. My parents had once threatened to erase me from the family unless I paid $240,000 that I didn’t owe. They expected me to panic and surrender. Instead, I protected my future and let their decisions remain their responsibility. When they finally understood what they’d lost, I was no longer waiting for permission to live my own life.