“My parents sold my childhood home behind my back and said, ‘Our house, our decision.’ 3 months later, Dad opened the mortgage papers and froze.”
“Your parents sold the house this morning. The buyers are already signing the paperwork.”
My younger brother, Tyler, delivered the news over the phone while I stood outside a hardware store, holding a set of keys I’d planned to use on the home I’d dreamed of buying for years.
“What do you mean, they sold it?”
“Mom said you were taking too long to make up your mind.”
I felt my stomach drop.
For months, my parents had promised me the first opportunity to buy our childhood home in Columbus, Ohio. I’d grown up there, buried our family dog beneath the maple tree, and watched my father measure my height against the kitchen doorframe every birthday.
I’d been saving for a down payment and had already spoken with a mortgage lender.
My parents knew all of it.
When I called Mom, she answered as though I were interrupting her lunch.
“Why didn’t you tell me you were selling?”
“Because we didn’t need permission, Claire.”
“You promised I’d have the first chance to buy it.”
“And we changed our minds. Our house. Our money. Our decision.”
Dad joined the call.
“You don’t own that property. Stop acting like you do.”
I stood there, gripping my phone, fighting the urge to remind them how many weekends I’d spent repairing that house, how I’d paid for the new furnace when Dad’s savings ran short, and how I’d covered several mortgage payments during his business downturn.
Instead, I said three words.
“Okay. I understand.”
Mom sounded almost disappointed that I wasn’t arguing.
“Good. The sale is final.”
I hung up and drove home.
That evening, I opened the folder I’d kept locked in my desk. Inside were bank statements, signed agreements, and copies of payments I’d made over the previous four years.
My parents had always called that money a temporary family loan.
But the documents contained something they’d apparently forgotten.
Two years earlier, when Dad nearly lost the house after falling behind on his mortgage, I’d agreed to refinance part of the debt through a lender in exchange for a legally documented interest in the property. My attorney had insisted everything be recorded properly.
My parents had signed.
They’d later paid me back some of the money, but never completed the final release.
I hadn’t mentioned it during our argument.
Three months passed.
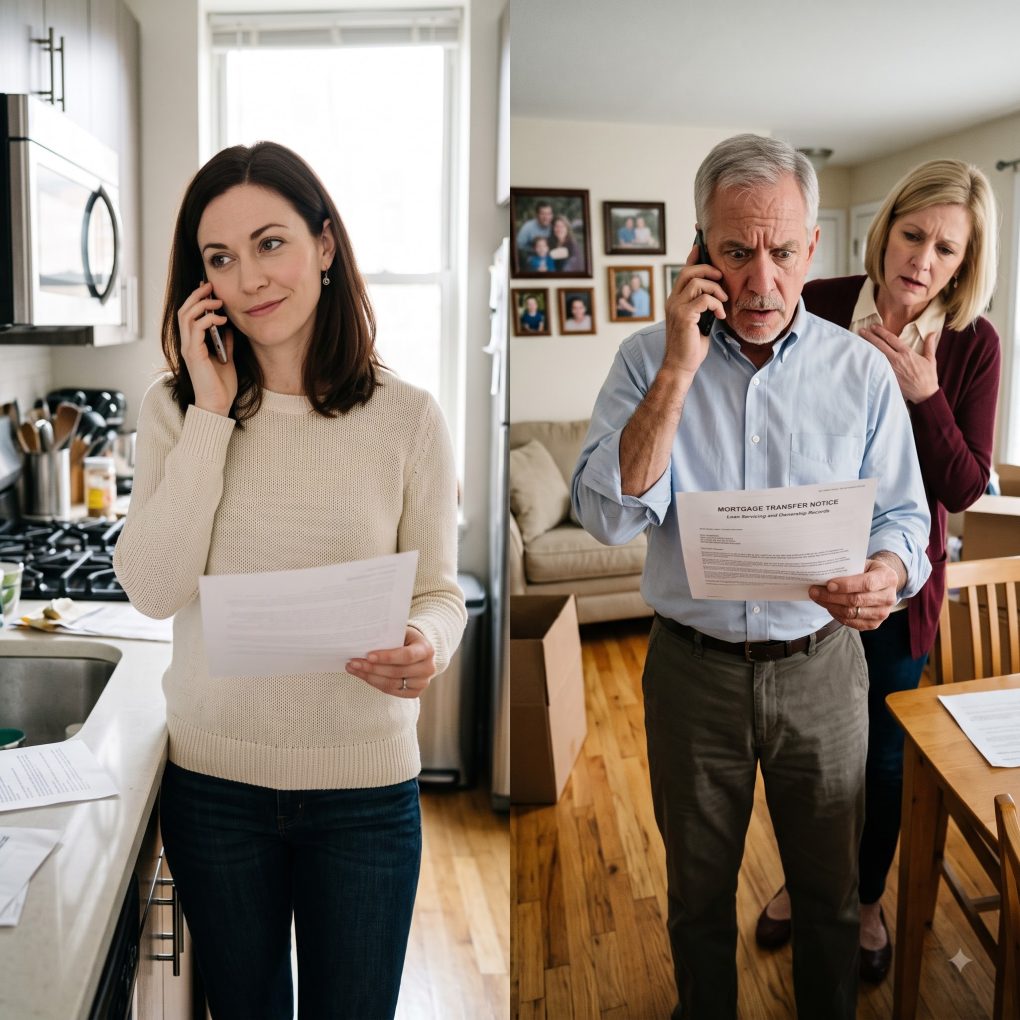
Then, at 7:12 on a Tuesday morning, my phone rang.
Dad sounded terrified.
“Claire, we just opened a mortgage transfer letter. The bank says the loan is being reassigned for review, and there’s a document attached with your name on it.”
He took a shaky breath.
“Why is your name on our loan?”
I looked at the file on my desk.
Then I answered calmly.
“You told me owners make their own decisions, Dad.”
Silence.
And then he asked the one question that revealed he had no idea what he’d actually signed.
“What exactly did you do to us?”
My parents believed selling the house would erase their promises and leave me with nothing but memories. They didn’t realize the paperwork they’d signed years earlier could follow the property long after the sale. And when I finally examined the bank’s latest notice, I discovered the sale had exposed a second secret—one that could put the entire transaction at risk.
“Tell me what you did,” Dad repeated.
I sat down at my desk.
“I didn’t do anything to you. I received a letter from the lender, just like you did.”
“Don’t play games with me, Claire. The bank says your name is connected to the mortgage.”
“Then you should ask the bank what the documents say.”
Mom grabbed the phone from him.
“Your father is having a terrible morning. If this is some kind of revenge because we sold the house, you need to stop immediately.”
I almost laughed.
For three months, they hadn’t called to ask how I was doing. They hadn’t apologized for breaking their promise. They’d simply assumed I’d accept their decision and disappear from the conversation.
Now they wanted an explanation.
“Mom, do you remember when Dad’s contracting business nearly went under?”
She went quiet.
“You needed help keeping the house. I paid $86,000 toward the overdue mortgage, taxes, and repairs. In exchange, we signed an agreement documenting my financial interest and setting out how that money would be repaid.”
“That was years ago,” she snapped.
“Yes. And you repaid part of it. But the agreement was never fully released.”
Dad came back on the line.
“That was just between family members. It wasn’t supposed to affect the house.”
“It was signed and reviewed by an attorney. You received copies.”
He began speaking faster.
“The buyers have a mortgage. They already moved some of their things in. You can’t interfere with their home.”
“I haven’t contacted them. I haven’t interfered with anything.”
That was true.
When the lender notified me that the property had been sold, I forwarded the sale information to my attorney. She advised me not to make assumptions or contact the buyers before reviewing the title and loan documents.
The bank’s letter wasn’t a declaration that I owned my parents’ mortgage. It was a notice that a recorded financial interest and an unresolved repayment agreement had surfaced during a post-sale review.
The distinction mattered.
And my parents were about to learn why.
That afternoon, my attorney, Melissa Grant, called.
“Claire, I’ve reviewed the county records and the closing documents we were able to obtain,” she said. “There’s a problem, but it’s not exactly what your father thinks.”
“What kind of problem?”
“The sale documents appear to have represented that the property was being transferred free of any unresolved claims. We need to determine whether your recorded interest was properly addressed at closing.”
I felt my chest tighten.
“Can the buyers lose the house?”
“Not automatically. They may have protections, and the title insurer will have its own process. We need the complete record before drawing conclusions.”
Then she added something that made me sit up straight.
“The mortgage transfer notice isn’t the only issue. The closing file also contains a payoff statement that doesn’t match the balance shown in the lender’s records.”
I stared at the wall.
“Who submitted it?”
“Your father and the closing agent will need to explain that. I don’t want to speculate before we have the original documents.”
That evening, Dad called again.
This time, he wasn’t angry.
He was frightened.
“The title company says there’s a hold on the remaining sale proceeds,” he said. “They’re asking us for your signed release.”
I closed my eyes.
“I never signed one.”
“Your mother says you agreed to let it go.”
“I didn’t.”
A long silence followed.
Then Dad whispered, “Claire, we used some of the sale money to pay off Tyler’s business debt. We thought the rest would be enough to settle everything.”
My blood ran cold.
“How much did you use?”
“That’s not the point.”
“It is if you spent money before resolving the claim.”
He exhaled sharply.
“Your brother was about to lose his business.”
And there it was.
The house hadn’t simply been sold because my parents wanted to move on.
They had used its value to rescue Tyler again.
But Melissa’s next call revealed the bigger twist.
The closing documents didn’t merely overlook my agreement.
Someone had submitted a statement claiming I had already waived my interest in the property.
The signature beside my name looked convincing at first glance.
But I had never signed it.
And when Melissa enlarged the scanned document, she noticed something that made her immediately request the original file.
The signature was dated on a day I could prove I’d been hundreds of miles away.
Melissa called me at nine the following morning.
“Don’t contact your parents about the signature yet,” she said. “We need to preserve the records and let the professionals investigate.”
I stared at the folder on my desk.
“Do you think they forged it?”
“I think the signature needs to be authenticated. I won’t accuse anyone without evidence. What I can tell you is that the document doesn’t match the agreement in our file, and the date raises a serious question.”
She explained the situation carefully.
Years earlier, my father, Robert Carter, had nearly lost his contracting business after several clients delayed payments and a large project went over budget. The family home was at risk of foreclosure. My parents had exhausted their savings, and the lender had given them a deadline to bring the account current.
I was twenty-six at the time. I had a stable job in commercial property management and had saved money for my own home.
Instead of buying a place for myself, I agreed to help them.
My contribution was substantial: $86,000 toward the overdue mortgage, property taxes, and urgent repairs. I didn’t hand over the money casually. I wanted everyone to understand that this was not a gift that would disappear into the family’s vague promises.
With an attorney’s help, we documented the arrangement. The paperwork addressed repayment and established a recorded interest connected to the property, subject to the terms and applicable law.
My parents signed the documents.
Dad thanked me repeatedly.
Mom cried and promised that when they eventually sold the house, I would have the first opportunity to purchase it.
“You’re the one who saved our home,” she’d told me. “You’ll always have a place here.”
For a while, they honored the agreement.
They made some repayments, and I continued with my life. I rented an apartment, worked overtime, and rebuilt my savings. I didn’t demand that they move out or treat the house as mine. I simply expected the agreement to mean what it said.
Then, years later, they began talking about downsizing.
Mom called me into the kitchen during a family visit and told me they were considering selling.
“I want to buy it,” I said immediately.
She smiled.
“We knew you would. We’ll give you the first chance.”
I contacted a mortgage lender, gathered my financial documents, and began exploring financing. I wasn’t asking for a discount. I wanted a fair purchase price and enough time to arrange the down payment.
My parents knew I was working on it.
But Tyler’s business was struggling.
He had opened a small home-renovation company and borrowed money to buy equipment and a work van. Several projects fell through, and he was left with debts he couldn’t comfortably manage.
Dad believed Tyler needed one final rescue.
Mom agreed.
Instead of discussing the problem with me, they decided to sell the house to an outside buyer who was ready to close quickly.
When I challenged them, Mom delivered her familiar line.
“Our house. Our money. Our decision.”
At the time, I thought the betrayal was emotional.
I believed they had broken a promise because they preferred an easy sale over helping their daughter buy the home she’d grown up in.
I had no idea that the closing process would uncover unresolved financial paperwork, a disputed waiver, and a payoff statement that didn’t match the lender’s records.
Now Melissa was telling me that these details could affect everyone involved.
“Here’s what we do,” she said. “We cooperate with the review. We don’t threaten the buyers, and we don’t assume the house automatically belongs to you. We establish what was signed, what was recorded, what remains owed, and what remedies the agreement provides.”
I agreed.
That afternoon, she sent a formal notice to the title company and the parties involved, requesting preservation of the original closing records and clarification of the disputed documents.
The buyers, a couple named Mark and Susan Miller, had purchased the home in good faith. They had already begun moving in, and their children had started school in the neighborhood.
I couldn’t bear the thought of their lives being thrown into chaos because my parents had mishandled an agreement.
When Melissa asked whether I wanted to pursue the matter, I answered carefully.
“I want my rights respected. I don’t want innocent people punished for something they didn’t know about.”
She assured me that we could pursue a lawful resolution without assuming the buyers had done anything wrong.
The next few days were tense.
Dad left three voicemails. Mom sent a long message accusing me of trying to destroy the family. Tyler texted that I was being selfish and that his business would collapse if the sale proceeds remained unavailable.
I didn’t respond to the accusations.
Instead, I sent one message to all three.
“My attorney is handling the documents. Please direct any questions about the agreement or the closing through her. I will not discuss this through threats or family pressure.”
For the first time, I stopped allowing the loudest person in the family to determine what happened next.
The title company began reviewing its file. The lender confirmed that the payoff statement required further reconciliation. The disputed waiver was referred for examination, and the parties were asked to provide original records and supporting information.
A week later, Melissa called with an update.
“The title company has confirmed that your recorded interest was not properly resolved in the closing file,” she said. “They have not made a final determination about the disputed signature. But the current evidence supports your position that no valid release was provided by you.”
“What does that mean for the house?”
“It means we have a stronger basis to negotiate a resolution. It doesn’t mean you automatically get the property back. The buyers’ rights, the mortgage, the title insurance, and the terms of your agreement all have to be considered.”
Then she told me about the payoff statement.
The amount submitted at closing had been based on an outdated figure. The discrepancy wasn’t enough, by itself, to establish fraud, but it required correction and an explanation of how the remaining funds had been distributed.
That was when Tyler finally admitted what he’d told Dad.
He had expected a substantial portion of the sale proceeds to cover his outstanding business debts. Dad had promised him that the sale would take care of everything.
Neither had properly accounted for my unresolved claim.
They had treated the money as if it were entirely theirs before the closing obligations had been settled.
The realization didn’t make me happy.
It made me tired.
I had spent years helping my family because I believed that when someone was in trouble, you did what you could. But somehow, my willingness to help had become an expectation that I would always absorb the consequences.
Three weeks after the first letter arrived, Melissa arranged a meeting with my parents and their attorney.
I agreed to attend.
Dad arrived looking older than I remembered. Mom sat beside him, clutching a folder. Tyler was not invited because the immediate dispute concerned the property agreement and closing records.
Melissa began by explaining the documented facts.
My contribution had been recorded. The repayment agreement remained unresolved. No release signed by me had been established as valid. The sale had proceeded without properly resolving the disputed interest, and the title company was working with the lender and insurers to determine the appropriate correction.
Dad interrupted.
“We never intended to cheat Claire.”
Melissa didn’t argue about his intentions.
“Intent is a separate question. Today, we need to determine the facts and discuss a resolution.”
Then she placed the disputed waiver on the table.
Dad stared at it.
Mom’s fingers tightened around her folder.
“Did either of you prepare this document?” Melissa asked.
Mom began crying.
“I didn’t understand what the closing agent needed.”
Dad looked at her sharply.
“What are you talking about?”
She wiped her face and admitted that she had sent the closing agent an old scan of the agreement and a separate page she believed would allow the sale to proceed. She said she had copied my signature from an earlier document because she thought it was only confirming that I’d been repaid.
She insisted she hadn’t intended to forge a legal release.
But copying someone’s signature without permission does not become acceptable because the person doing it misunderstands the consequences.
Melissa made it clear that the circumstances would need to be fully documented and assessed by the appropriate professionals. No one in the room could simply declare the matter harmless.
I looked at my mother.
“You copied my signature?”
She nodded through her tears.
“I thought we could sort it out later.”
“You promised me the first chance to buy the house. Then you sold it without telling me. And when the paperwork became inconvenient, you signed my name.”
“I was trying to help your father and Tyler.”
“And who was trying to help me?”
She had no answer.
Dad stared at the table.
For once, he didn’t tell me to stop arguing or remind me that family came first.
The meeting continued for another hour. The lawyers discussed several possible solutions, including repayment, a negotiated settlement, and the steps necessary to protect the buyers while resolving the title issues.
The final arrangement took time.
The Millers’ purchase was not casually canceled. Their attorney and title insurer worked with the relevant parties to determine how the unresolved claim could be addressed without unnecessarily disrupting their ownership.
My parents agreed to settle the documented amount owed under our agreement, subject to the final accounting and legal terms. The remaining sale proceeds were reconciled, and a repayment schedule was established for the balance that could not be paid immediately.
The disputed waiver was withdrawn from reliance in the transaction, and the parties cooperated with the review of how it had been submitted.
The exact consequences of my mother’s actions were left to the appropriate legal process. I did not demand a dramatic punishment, and I did not promise to protect anyone from the consequences, either.
My priority was a truthful record and a fair resolution.
Several months later, the settlement was finalized. The buyers’ title was resolved through the agreed process, and I received the amount established under the settlement.
I did not get my childhood home back.
That was painful, but I eventually understood that owning the house would not restore the family I thought I had.
The house had been important to me because of what it represented: birthdays marked on the kitchen doorframe, summer evenings beneath the maple tree, and the belief that my parents’ promises meant something.
Those memories remained mine, even after someone else owned the property.
With the settlement money and the savings I’d rebuilt, I purchased a modest townhouse on the other side of Columbus. It had a small kitchen, a narrow backyard, and enough room for the furniture I’d collected over the years.
The first thing I did was hire a lawyer to review the closing documents and make sure every part of the transaction was properly recorded.
The second thing I did was plant a young maple tree.
It wasn’t the tree from my childhood, and I didn’t pretend it could replace it.
It was simply something I wanted to watch grow.
Dad called after I moved in.
“I never thought this would go so far,” he said.
I stood at my new kitchen window, looking at the small patch of soil outside.
“You thought I’d let it go because you were my father.”
He didn’t deny it.
“We were in a difficult position.”
“So was I.”
“I know.”
It was the first time he’d acknowledged that my needs had mattered in the situation.
He asked whether we could start over.
I told him we could work toward a relationship, but it would have to be different. No more promises made to keep me quiet. No more treating my financial help as an obligation. And no more expecting me to protect the family from the consequences of its own decisions.
He agreed, although rebuilding trust took much longer than saying the words.
Mom’s apology came later, in a handwritten letter. She admitted that she’d prioritized Tyler’s problems and Dad’s fears over my right to make my own choices. She acknowledged that copying my signature had been wrong, regardless of what she believed it would accomplish.
I didn’t immediately forgive her.
But I stopped waiting for her to become the mother I wished she’d been before deciding how I wanted to live.
Tyler eventually sold some of his equipment, restructured his business, and began repaying the money he’d borrowed from our parents. I didn’t rescue him financially. He had to make his own decisions and live with their consequences.
We became less close for a while, but the distance was healthier than our old pattern of emergencies followed by resentment.
A year after the sale, I drove past my childhood home.
The Millers had repainted the front door. A child’s bicycle rested beside the porch, and the old maple tree stood in the yard.
I didn’t stop.
I didn’t feel the need to reclaim the house or prove that my parents had lost something valuable.
I’d already learned the lesson that mattered.
They had told me, “Our house. Our money. Our decision.”
They were right that they had choices to make about their property. But those choices did not erase the agreements they had signed or give them the right to use my name without permission.
And I had a choice, too.
I could spend the rest of my life trying to make them admit that they’d hurt me, or I could build a future that no longer depended on their approval.
I chose the future.
My new home wasn’t as large as the house where I’d grown up. It didn’t have the old kitchen doorframe marked with pencil lines or the maple tree beneath which we’d buried our dog.
But every document was in order. Every payment was mine to make, and every decision about the property was mine to take responsibility for.
One evening, Dad called again.
“Claire,” he said quietly, “I finally understand why your name was on that loan.”
I waited.
“Because you were the one who helped us when we had nothing. And we acted as though that meant we could decide what happened to your money.”
For the first time, I heard an apology without an excuse attached.
I didn’t tell him everything was forgiven.
I told him I appreciated his honesty.
Then I hung up and went outside to water my maple tree.
The house my parents sold was no longer mine. The years I had spent helping them would never be returned. And the family I had once imagined was still something I had to grieve.
But my life belonged to me.
They had made their decision.
I had made mine.
And this time, I didn’t need to argue with anyone to stand by it.