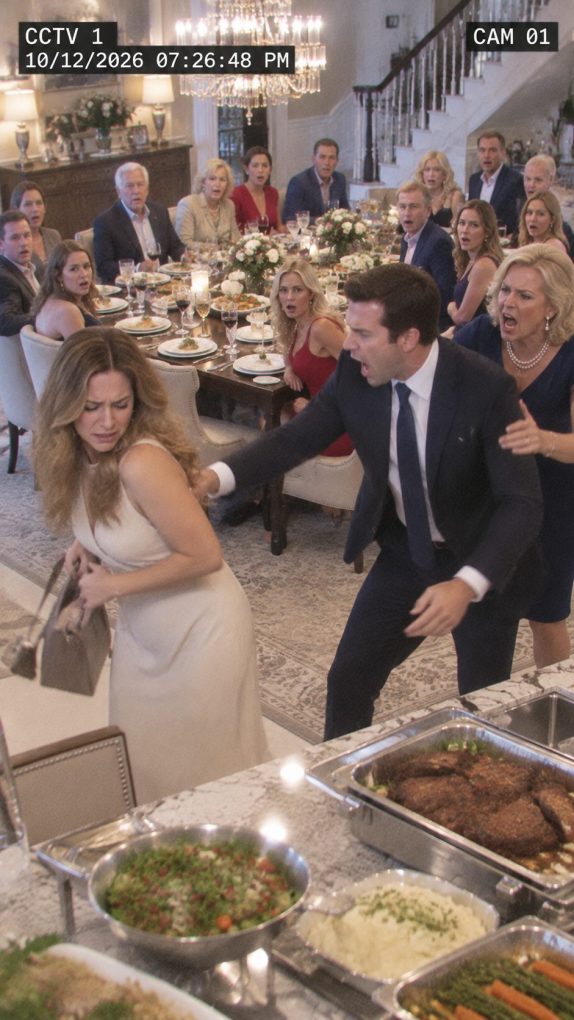
The first thing my husband’s mother said when I walked into her dining room was, “Oh good, the food is here.” She did not mean the catering trays. She meant me. I had been married to Nathan for eight months, but because his family lived outside Charleston and had skipped our small courthouse wedding, this was the first formal dinner where I would meet everyone at once. I had spent $3,600 arranging the meal because Nathan insisted his mother, Patricia, would judge me by “how seriously I treated family.” Twelve relatives sat around a polished mahogany table drinking wine I had purchased while Patricia inspected me as though Nathan had brought home an employee she had not approved.
Dinner had barely begun when Nathan looked at my empty chair and said, “Claire, Mom needs help in the kitchen.” I thought he meant bringing out one tray. Instead, Patricia handed me an apron. “You can plate the sides, refill glasses, clear as they finish, and make coffee afterward.” I stared at Nathan, waiting for him to laugh. He continued eating. His sister Madison smiled and said, “Mom always said Nathan needed a wife who could actually take care of people.” That was when I realized there was no misunderstanding. They expected me to serve the dinner I had paid for while everyone else sat down.
I removed the apron, placed it on the counter, picked up my purse, and walked toward the front door. Nathan followed me into the hallway. “Don’t embarrass me.” I almost laughed. “You ordered your wife into the kitchen in front of twelve people.” His expression hardened. “This is how my family does things.” I opened the door. “Then enjoy your family dinner.” Behind him, Patricia called, “If she leaves, who’s cleaning this up?” I did not turn around.
At home, I showered, changed clothes, and ignored seventeen calls from Nathan. At 11:47 p.m., my banking app sent an alert.
TRANSFER ATTEMPT: $24,800.00
I sat upright.
The destination was an account I did not recognize. The transfer had been blocked because the bank required secondary verification for amounts above $20,000. Seconds later, another request appeared for $19,500. Then another for $4,900. Someone was splitting the amount to avoid the security threshold.
I called the bank’s fraud line and froze outgoing transfers. The representative told me the requests had been initiated through online banking using the correct password from a device previously associated with our home network.
Nathan knew my old password.
But he did not know I had changed the verification number after a strange login attempt two weeks earlier.
At 12:03, Nathan finally texted:
Stop being dramatic and approve the transfers. Mom already committed the money.
I read it three times.
Then I called my attorney, Rebecca Sloan.
“Committed it to what?”
Rebecca told me not to answer him until morning. She asked me to forward every message, then requested screenshots of the blocked transfers.
At 12:26, Nathan sent another text.
It’s not like the money is disappearing. It’s staying in the family.
That sentence made my stomach drop.
The next morning, Rebecca called after reviewing the account name attached to the attempted transfer.
“Claire, the destination belongs to an LLC.”
“Whose?”
She paused.
“Patricia’s.”
I closed my eyes.
Then Rebecca continued.
“And I think you need to see what that LLC signed yesterday.”
A contract had already been executed for a $410,000 beach condo.
The buyer was Patricia’s company.
The earnest-money deadline was noon.
And under “source of funds,” someone had listed my personal savings account.
Rebecca’s first instruction was simple: do not move money impulsively, do not threaten anyone, and do not assume an attempted transfer was automatically criminal simply because I had not approved it. We needed records showing who initiated it, what authority they believed they had, and what Patricia had represented to the seller.
The bank preserved the login history. The transfer attempts came from Nathan’s laptop while he was still at Patricia’s house. He had entered my username and password correctly, then failed when the bank requested verification through my phone.
Nathan initially claimed we had always treated money as shared. That was only partly true. We maintained a joint household account, but the savings account he tried to access had existed before our marriage and remained solely in my name.
The $49,200 he attempted to move represented the condo’s earnest-money deposit plus closing reserves. Patricia had signed the purchase contract the previous afternoon, before the family dinner even began.
That explained why she seemed so pleased when I arrived. The dinner was not merely an introduction. She expected Nathan to persuade me to fund the purchase before the night ended.
According to Patricia, Nathan had promised that I wanted to “help her settle somewhere permanent” because she had spent so much supporting him when he was younger. I had never discussed buying her property. I had never even seen the condo.
The realtor produced texts from Nathan saying, Claire has significant liquid savings and will wire the deposit after dinner. He also said I preferred not to appear on the deed because the condo was meant to be a gift.
When Rebecca showed me that message, my anger became strangely quiet. Nathan had not misunderstood my generosity. He had converted it into permission without ever asking.
Then we reviewed the previous eight months of marriage. I had paid most household expenses because Nathan said he was aggressively rebuilding retirement savings after a difficult divorce years earlier.
His retirement contributions had been real—but much smaller than he claimed. Nearly $3,000 each month had instead gone to Patricia for rent, travel, and credit-card bills.
I could have accepted helping her if we had discussed it. What I could not accept was being told one financial story while another operated behind my back.
Nathan finally came home two days later accompanied by his brother. I did not meet them alone. Rebecca had advised me to communicate in writing while finances were being reviewed.
His message said I was destroying the marriage over “one mistake” and embarrassing his mother by jeopardizing her condo contract.
The seller ultimately retained only the portion of Patricia’s deposit she had actually paid herself under the contract terms. The purchase collapsed because she could not produce the promised remaining funds.
Then the bank’s security review uncovered something older.
Three months before the dinner, Nathan had requested an additional debit card on my savings relationship.
The request was rejected because the account permitted cards only in the owner’s name.
Attached to the request was a note:
Spouse authorized for full access.
Below it appeared my electronic signature.
I had never signed it.
And suddenly I understood that the midnight transfers were not Nathan’s first attempt to reach my money.
They were simply the first one I caught.
Rebecca disputed the earlier authorization and asked the bank to preserve all underlying records. The signature image closely resembled one from paperwork I had signed when adding Nathan as an emergency contact, but the bank could not establish that I approved any debit access.
No additional card had ever been issued, and no money had left through that request. That limited the financial damage, but it did not repair what the attempt revealed about our marriage.
Nathan eventually admitted he had copied the signature image into the form. He insisted he believed marriage meant he could access the account if necessary and claimed Patricia’s condo qualified as a family need.
I asked him one question through our counselor: “If you believed I would agree, why didn’t you ask?” He could not give an answer that survived more than a few seconds.
Patricia gave one. She said women in her family had always contributed whatever their husbands required and that I had entered marriage with “too much separation between mine and ours.”
That conversation helped me understand the dinner. Ordering me into the kitchen had not been random cruelty. It reflected the same assumption behind the bank transfer: marrying Nathan meant becoming useful to his family on terms they defined.
I filed for divorce after ten months of marriage. Because the marriage was short and our major premarital assets remained largely separate, the financial unwinding was less complicated than it could have been.
We divided the joint account, personal property, and legitimate shared expenses through mediation. My individual savings remained mine. Nathan retained his retirement account and the debts attached to his own obligations.
Patricia never bought the beach condo. She eventually moved into a smaller apartment within her existing income. Contrary to Nathan’s predictions, she was not left homeless or destitute.
What she lost was the upgrade she had planned using money that had never been offered.
Months later, Madison contacted me. She apologized for laughing at dinner. She admitted Patricia had treated every new woman entering the family as though she needed to prove herself through service.
“You were the first one who just left,” she said.
That surprised me.
I had spent weeks wondering whether walking out made me rude.
It turned out the simplest boundary had looked revolutionary only because nobody before me had been allowed to have one.
Nathan sent one final message after the divorce became official.
I wish you had stayed that night so we could have talked like adults.
I stared at it for a long time before replying.
Adults ask before spending someone else’s money.
Then I blocked the number.
The strange part is that I barely remember what food I ordered for that first family dinner anymore. I remember the linen napkins, Patricia’s smile, and the apron she held out as though my place had already been decided.
But mostly I remember 11:47 p.m.
The glowing screen.
The transfer alert.
The exact moment I realized that being ordered into the kitchen and having my savings treated as family property were not two separate humiliations.
They came from the same belief:
that once I became Nathan’s wife, access to me automatically became access to everything I could provide.
I had paid for every plate on that table.
I did not owe them the privilege of serving it too.