“Stay home. We’re giving your cabin to my mother-in-law,” my daughter texted at 8:17 Tuesday morning. I stared at the message beside the $31,400 vacation itinerary I had paid for. By noon, I had canceled the cruise reservations I controlled and blocked every additional card issued on my credit accounts. Two days later, Lauren was pounding on my front door, screaming that I had humiliated her at the airport.
I’m Eleanor Mitchell, sixty-four, a retired school administrator living outside Charleston, South Carolina. My daughter Lauren, thirty-six, married Adam five years ago. I’d planned this Caribbean cruise to celebrate my retirement and finally spend a peaceful week with family.
I booked three cabins: a premium suite for myself, a balcony cabin for Lauren and Adam, and an ocean-view room for Adam’s mother, Diane. I also paid for airfare, transfers, and excursions. Every reservation was made through my travel agent using my own accounts.
The previous weekend, Lauren suggested Diane needed my suite because her knees hurt. I offered to ask about accessible cabins, but Lauren dismissed the idea. She insisted I could stay home and watch their vacation photographs instead.
When I refused, she sent that text and followed it with, “Don’t make a scene. We already told Diane it’s hers.” Adam messaged that I should respect their decision. Neither offered to reimburse a cent of the money I had spent.
I called the travel agent, explained the situation, and requested cancellation under the booking terms. Some airfare became credits, and the cruise line retained cancellation penalties. I accepted those losses rather than finance a trip from which I’d been deliberately excluded.
Next, I called my bank about the authorized-user cards I’d given Lauren and Adam for travel emergencies. The representative confirmed they were linked to my accounts, not theirs. I locked those cards, requested their removal, and changed the account passwords.
On Thursday morning, Lauren tried to pay for airport parking and a replacement flight with the card I’d disabled. It was declined. She called eleven times before noon, then texted that she’d already told Diane they were still going.
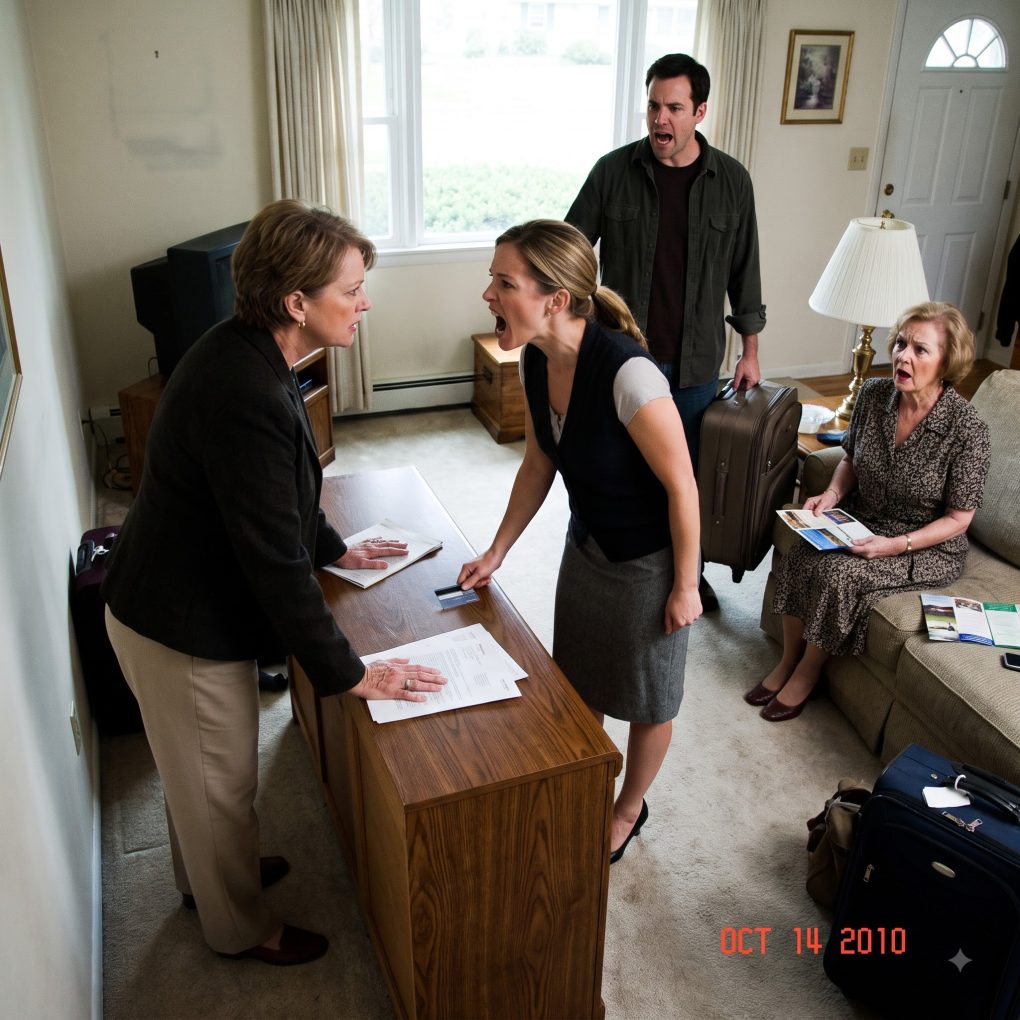
At three, a car stopped outside my house. Lauren emerged carrying a rolling suitcase, followed by Adam and Diane. I could hear Lauren shouting before I opened the door, accusing me of stealing their vacation.
I stayed behind the threshold and said, “You told me to stay home. I did.” Lauren shoved her phone toward my face, displaying a canceled booking notice. Then Diane spoke for the first time: “You owe me that suite.”
Diane said Lauren had promised her the premium cabin weeks earlier. I asked whether anyone had mentioned whose money purchased it. She looked from me to Adam, and neither answered immediately. Her voice echoed across my front porch, drawing curious glances from the neighbors who had been watering their gardens.
Lauren claimed I had agreed to pay for a family vacation, not a vacation for myself. I reminded her that the suite was booked under my name and that I had never consented to surrender it. Her response was to demand the cash value of the canceled reservations.
I explained that cancellation did not produce a full refund. The travel agent had provided a written breakdown of penalties, credits, and amounts returning to my original payment method. Those remaining funds were mine, just as the original payments had been.
Adam stepped forward and accused me of endangering his mother by leaving her stranded. I asked how they could be stranded when none had boarded a plane. They had driven home from the airport after learning the cruise bookings were canceled and their replacement plans were unaffordable.
Then Lauren revealed the real reason for her panic. She’d promised Diane a luxury suite and had charged several extra vacation purchases to my authorized-user card earlier that week. Now she feared those legitimate pending charges would still reach my account, while future payments were blocked.
I told her I would review each charge with my bank and dispute only anything genuinely unauthorized. I would not claim purchases were fraudulent simply because I regretted trusting her. But the permission to spend more of my money ended the moment she excluded me.
Lauren began crying and said she’d lose face with Adam’s relatives. Diane demanded that I apologize to her for ruining a milestone birthday. I reminded them that I had offered her an entirely separate ocean-view cabin as a gift.
My neighbor appeared across the street after hearing the shouting. I asked Lauren to lower her voice and leave, because the conversation was over. Adam called me vindictive, but he finally guided Diane toward the car without touching me.
That evening, my travel agent forwarded an email chain Lauren had sent behind my back. She had asked the cruise line to replace my name on the premium suite reservation with Diane’s, claiming I had authorized the change. The agent had refused without my direct confirmation.
I read the messages twice before calling Lauren. She admitted she’d tried to transfer the suite because she believed I would be too embarrassed to object publicly. I ended the call, forwarded the correspondence to my attorney, and realized that our argument was no longer just about a vacation.
My attorney, Rebecca Hayes, reviewed the reservation records and bank documents the next morning. She explained that a misleading request to the travel company did not automatically establish a crime, but it did justify preserving the messages. She also advised me to keep all future discussions in writing.
The bank confirmed that Lauren and Adam’s additional cards had been disabled and removed from my account. Several charges made before the lock remained payable under the card agreement, while one unfamiliar purchase required further review. I paid the amounts I had actually authorized and disputed only the charge I could not verify.
For a week, Lauren sent messages calling me selfish and cruel. Then her tone changed when she learned the company would not reinstate our canceled cabins at the original prices. The suite she had promised Diane was gone, and no amount of shouting could restore it.
Adam came to see me alone that Sunday. He admitted Lauren had told him I had agreed to give up the premium cabin, and he’d chosen not to ask me directly. He apologized for repeating her story and offered to reimburse the extra travel charges he’d made.
I accepted his repayment, but I refused to finance another vacation. I told him that no one had the right to volunteer my savings or my accommodations without asking. He nodded, looking ashamed, and left without arguing.
Diane later called and surprised me by apologizing too. She said she had believed the suite was a gift from all three of us, not something taken from me. Once she saw Lauren’s messages, she understood why I had canceled.
Lauren was the last to reach out sincerely. She arrived one evening without Adam or a suitcase and admitted that she’d wanted to impress her mother-in-law. She said she’d begun treating my retirement savings as a family budget instead of money I’d spent forty years earning.
I told her an apology could not erase what she’d done, especially the attempt to alter my reservation. We agreed to meet for coffee occasionally, but I would no longer give her access to my payment cards or book costly trips on everyone’s behalf. Trust, I said, would have to return slowly.
Months later, I used part of my airline credit for a quiet trip to Maine with an old friend. We stayed in a small inn, walked beside the ocean, and paid our own bills. Nobody argued over rooms or expected me to disappear so someone else could enjoy my holiday.
On the last morning, I checked my phone and saw a simple message from Lauren asking whether I’d arrived home safely. For once, there was no request for money attached. I answered her, then put my phone away and watched the waves. I had lost some cancellation fees, but I had finally stopped paying for the privilege of being pushed aside.