My mother-in-law added the fourth rib-eye package to the cart while Daniel pretended not to notice.
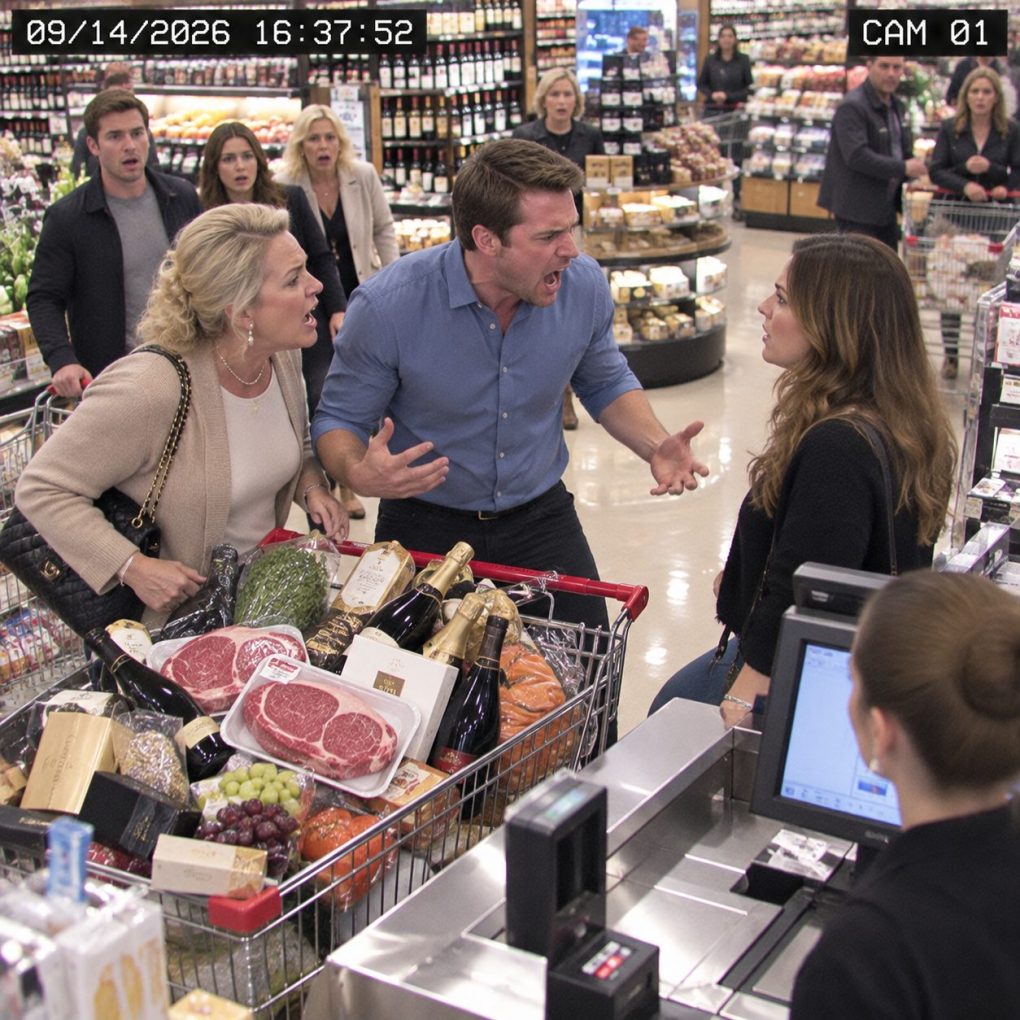
By the time we reached the register, Patricia had filled almost half of it herself—prime steaks, imported cheese, lobster tails, expensive olive oil, six bottles of wine, and enough specialty groceries to stock her kitchen for a month. I had come to Costco for detergent, cereal, chicken breasts, and school snacks for our daughter. Patricia had invited herself along because, according to Daniel, she “needed a few things.”
Her few things came to $486.
The cashier finished scanning everything and looked at us.
Patricia took one elegant step backward.
Daniel looked at me.
I stood still.
“Aren’t you paying?” he asked.
“No.”
His cheeks turned red instantly. “What do you mean, no?”
“I mean your mother put those things in the cart. She can pay for them.”
Patricia laughed as though I had made an embarrassing joke.
Daniel did not.
“You expect my mom to pay for her own food?”
People in the next checkout lane turned.
I calmly answered, “Yes.”
Daniel stared at me as if I had insulted his mother instead of asking a sixty-two-year-old woman to buy her own groceries. Patricia immediately started removing items with theatrical sighs. “Forget it, sweetheart. Clearly I’m not welcome.”
Normally, that sentence would have worked.
For eight years, Daniel had trained me to avoid scenes involving his mother. A restaurant bill appeared? I paid. Patricia needed new tires? Daniel used our household account. Her property taxes were short one year? Somehow that became a family emergency. Whenever I questioned anything, Daniel said the same thing: “She raised me. I’m not going to nickel-and-dime my own mother.”
The problem was that he was not using his nickels or dimes.
Three days earlier, I had finally reviewed twelve months of statements from an account funded almost entirely by income from the two rental properties I owned before our marriage. Daniel had a debit card because the account was supposed to cover household expenses: groceries, utilities, our daughter’s school costs, home repairs.
Instead, I found payments to Patricia’s salon, wine club, furniture store, country club guest fees, and a monthly cleaning service at an address that was not ours.
Total: $31,840.
I had already called the bank.
Daniel’s card had been an authorized-user debit card tied to an account solely in my name. I revoked it, ordered a replacement card, and moved household autopayments to a new account he could not access.
Daniel did not know yet.
He found out twelve minutes after the grocery-store argument.
Patricia reluctantly paid for her own purchases. We walked into the parking lot in silence. Daniel stopped at the gas station across the street and tried his card.
Declined.
He tried again.
Then turned toward me.
“What did you do?”
“I removed your access.”
“You can’t just cut me off.”
“I removed you from my account.”
His expression changed.
Then his phone rang.
Patricia.
She was shouting loudly enough that I could hear her through the speaker.
“Daniel, what happened to the Lakeview payment?”
I looked at him.
“What Lakeview payment?”
He went completely still.
Patricia stopped talking.
Daniel ended the call.
I asked again.
“What is Lakeview?”
He said nothing.
That night, I searched twelve months of transactions again.
I had missed it because the payments were labeled as property management.
Every month, exactly $2,750 had gone to Lakeview Residential Services.
It was not managing either of my rental houses.
The next morning, I called them.
The receptionist pulled up the account and said pleasantly:
“Yes, Mrs. Carter. Those payments cover the condominium occupied by Patricia Carter.”
I gripped the phone.
“My mother-in-law?”
“Yes.”
Then she added the sentence that turned $31,840 into something much worse.
“According to our file, you’ve been paying her housing costs for almost three years.”
I did not confront Daniel immediately. I asked Lakeview for whatever records they were permitted to provide to the person whose account had been charged. By the afternoon, I had a payment history showing thirty-three monthly withdrawals connected to Patricia’s condominium.
The amount was staggering. Between monthly housing charges, assessments, and two special maintenance payments, more than $101,000 had left my account over nearly three years. I had noticed the merchant name before but assumed it belonged to the company servicing one of my rentals because Daniel handled several household payments.
That assumption was my mistake. It did not make his decision acceptable. My bank confirmed Daniel had not hacked the account or stolen a password; I had knowingly given him transaction authority years earlier. The issue was how he used that access and what he had told me about those charges.
I pulled old messages. Whenever I asked why household expenses had risen, Daniel blamed insurance, repairs, grocery inflation, and our daughter’s activities. Once, when I suggested reviewing the budget together, he told me I was becoming obsessive about money.
That evening I put the statements on the kitchen table. Daniel looked at them, then sat down without asking what they were. “How long?” I asked. He knew exactly what I meant. “Almost three years,” he said quietly.
Patricia had sold her house after retiring and moved into a luxury condo. Daniel said she underestimated the monthly fees and began struggling within six months. Instead of telling me, he offered to cover the difference temporarily. Temporary became permanent.
“Why didn’t you use your salary?” I asked. Daniel earned good money as a regional sales manager. He admitted his salary already covered his car, personal investments, vacations, and several debts he had never fully discussed with me. My rental account had simply been easier.
Then I asked the question that mattered. “Did your mother know the money was mine?” He hesitated long enough to answer. Patricia knew the payments came from “our family account.” Daniel had never explained that the account was legally mine or that most of its money came from properties I owned before we married.
Patricia arrived twenty minutes later without being invited. She accused me of humiliating Daniel at the store and abandoning her after years of treating her like family. I asked whether she had ever wondered why I never once mentioned paying for her condo.
Her face changed. “Daniel said you didn’t mind.” I turned toward him. “Did I ever say that?” He looked down. Patricia stopped talking.
I did not demand that she move immediately. Her agreement with Lakeview was separate from me, and I had no authority to evict her from a condominium I did not own. I simply notified Lakeview that future payments from my account were unauthorized unless I personally approved them.
The first payment Patricia had to make herself was due in nine days. She had enough retirement income to cover it, but doing so meant reducing travel, dining, and other discretionary spending. The crisis was not homelessness. It was lifestyle.
Daniel became furious when he realized I would not reverse the change. He said marriage meant sharing resources. I agreed. Then I placed his last twelve months of personal statements beside mine. He had invested more than $38,000 into an account solely in his name while using my rental income to support his mother.
He stared at the numbers.
For years, Daniel had described himself as the generous son.
The statements revealed something different.
He had been generous with money he expected me never to count.
Daniel slept in the guest room that night. I did not demand an immediate divorce or freeze every dollar in our marriage. I scheduled an appointment with a family-law attorney and another with a financial counselor because I needed to understand both my rights and the full shape of our finances before making permanent decisions.
The review uncovered no secret second family, gambling account, or dramatic criminal scheme. What it revealed was more ordinary and, to me, more damaging: years of unilateral decisions. Daniel treated his salary as something he managed and my rental income as something the household could absorb without discussion.
We rebuilt three years of spending from statements. Patricia’s condo was the largest expense, but there were also vacations, restaurant bills, furniture, insurance deductibles, and gifts Daniel had paid for on her behalf. The total exceeded $140,000.
Patricia initially insisted she would repay me every cent. I told her not to make promises she could not realistically keep. Some payments had occurred because Daniel authorized them using access I had given him. Sorting out every dollar through litigation could cost years and destroy whatever remained of the family.
Instead, my attorney helped document that I would no longer fund Patricia’s living expenses and that my premarital rental accounts would remain under my sole control. Daniel and I also separated household spending from personal spending so neither of us could quietly redefine generosity again.
Patricia sold several pieces of expensive furniture, canceled her wine club, stopped taking two international trips a year, and eventually moved from the luxury condo into a smaller apartment near her sister. She hated the change at first. Six months later, she admitted the old lifestyle had never matched her retirement income.
Daniel struggled more. He kept saying he had only wanted to take care of his mother. I eventually told him, “Taking care of someone requires giving something that belongs to you.” That sentence ended the argument faster than any spreadsheet.
We separated for four months. During that time, Daniel paid his own expenses, contributed directly to our daughter’s needs, and began counseling. For the first time since our marriage, he had to decide how much support he could personally afford to give Patricia without silently transferring the cost to me.
I did not make staying together easy. Trust was not restored because he apologized once. Daniel gave me full disclosure of our joint obligations, stopped using my accounts, and acknowledged to Patricia that I had never agreed to finance her condominium. Most importantly, he stopped calling financial boundaries selfish.
We eventually reconciled, but the marriage changed. There are no mystery cards now. No shared account exists without both of us receiving statements. Gifts to relatives come from personal discretionary money unless we explicitly agree otherwise.
Patricia and I never became close, but we became honest. The following Christmas she brought groceries to my house. When I offered to reimburse her, she actually laughed. “I can afford my own steaks,” she said.
So could she at Costco.
That was never really the problem.
The problem was the expectation that her son’s marriage contained a wallet without an owner, and that saying no was more offensive than taking without asking.
Daniel once believed providing for his mother made him a devoted son.
Eventually, he understood why I had been so angry.
He had not sacrificed for her.
He had volunteered me.
And the day I removed him from my account was not the day I stopped believing in family generosity.
It was the day I finally required generosity to include one essential thing:
consent.