“I overheard my family planning to bankrupt me this Christmas. When Mom called me furious later, I just smiled: ‘Enjoying my present?'”
“By January, she won’t have a dollar left. Then we can finally take control of everything she owns.”
I froze outside my parents’ dining room, a wrapped Christmas present in my hands.
Inside, my mother was laughing.
My brother, Daniel, lowered his voice. “What if she finds out about the loan documents?”
“She won’t,” Mom replied. “She trusts us. Besides, she’s always wanted our approval. Just tell her the papers are for the family investment.”
Then my father said something that made my stomach turn.
“Once she signs, the debt becomes her problem. We’ll use her credit to cover Daniel’s losses, and if everything collapses, she’ll be the one filing for bankruptcy.”
I stood motionless.
They weren’t discussing some distant relative.
They were talking about me.
My name is Emily Carter, I’m thirty-two, and I had spent seven years building a small accounting consultancy in Ohio. I had worked weekends, skipped vacations, and saved enough to buy my own house.
My family had always called me selfish whenever I refused to pay for Daniel’s mistakes.
Now, apparently, they had decided to take everything.
I quietly backed away before anyone noticed me. I left my present beneath the Christmas tree, kissed everyone’s cheeks, and smiled through dinner while my mother talked about family loyalty.
Then she handed me a thick envelope.
“Just a few documents for our new investment,” she said sweetly. “Sign them after Christmas. We’re counting on you.”
I looked at the papers.
The first page authorized a substantial personal loan. The next contained a guarantee that could make me responsible for Daniel’s business debts.
And tucked between them was a document bearing a signature that looked almost exactly like mine.
Someone had already forged my name.
I slipped the envelope into my purse and said, “Of course, Mom. I’ll look at everything.”
That night, I called my attorney.
By morning, I had discovered that my family’s plan was bigger than I imagined. They had been preparing for months, and someone had already contacted a lender using my information.
So I prepared a little Christmas present of my own.
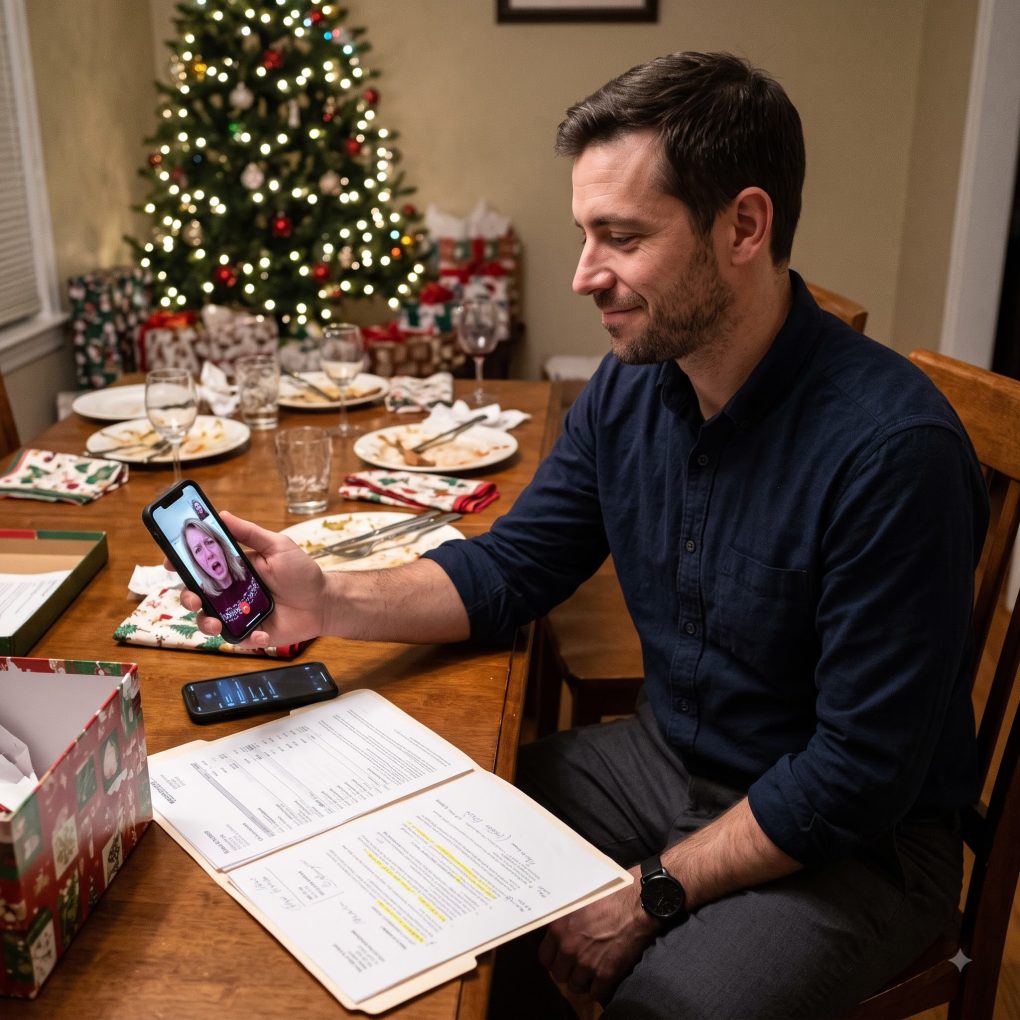
At 8:17 p.m. on Christmas Day, my phone rang.
Mom’s name flashed across the screen.
I answered.
“What on earth have you done?” she screamed.
I leaned back in my chair, smiled, and asked the question I had been waiting to ask.
“So, did you enjoy my little present?”
For three long seconds, she said nothing.
Then I heard my father shouting in the background, and Daniel suddenly yelled, “MOM, HANG UP! SHE CAN’T KNOW ABOUT THE OTHER ACCOUNT!”
My smile disappeared.
The other account?
I pressed the phone closer to my ear just as my mother whispered, “Emily, whatever you think you found, you need to come home immediately. Before the police get involved.”
And then someone knocked violently on my front door.
What my family had planned was bad enough. But the documents I uncovered next revealed that the people I trusted most had been hiding something far more dangerous—and Christmas night was only the beginning.
The pounding on my door came again.
“Emily Carter? We need to speak with you.”
I looked through the peephole and saw two uniformed police officers standing on my porch.
My mother was still on the phone.
“Don’t open that door,” she whispered urgently. “You need to listen to me.”
I almost laughed.
Five minutes earlier, she had been screaming at me. Now she sounded terrified.
“Why are the police at my house, Mom?”
“I don’t know.”
“Then why did you tell me to come home before they got involved?”
Silence.
I ended the call and opened the door.
The officers explained that a financial institution had reported suspected identity theft connected to a loan application. My name appeared on the application, but the signature and supporting documents had raised concerns.
They weren’t there to arrest me. They wanted to establish whether I had submitted the application.
I showed them the envelope, explained what I had overheard, and provided my attorney’s contact information.
One officer studied the documents.
“Ms. Carter, did you authorize anyone to apply for this loan on your behalf?”
“No.”
“Do you recognize this business?”
He showed me a company name I had never seen before: Carter Family Holdings LLC.
My brother had created it six months earlier.
The officers left after recording my statement, but not before advising me to preserve every document and contact the lender’s fraud department.
I immediately called my attorney, Rachel Morgan.
Within an hour, Rachel had reviewed the paperwork and identified several red flags. The loan application listed my house as collateral, even though I had never authorized a lien against it.
Worse, the documents claimed I had agreed to guarantee $380,000 in business obligations.
“Don’t sign anything,” Rachel warned. “And don’t confront them without a plan. We need the original records and the lender’s file.”
Then she asked me a question that changed everything.
“Emily, have you ever given your parents access to your financial accounts?”
“Years ago. Mom helped me organize paperwork when I started my business.”
“Did you give her copies of your identification or tax returns?”
I remembered a folder I had left at my parents’ house during a difficult tax season.
Inside had been copies of my driver’s license, tax documents, and business information.
My family hadn’t needed to steal my identity from a stranger.
I had trusted them with the pieces they needed.
The following morning, Rachel contacted the lender and submitted a formal fraud notice. I froze my credit, changed my passwords, and began reviewing every business and personal account.
Then we found a second company account linked to Carter Family Holdings.
It had received money from Daniel’s struggling construction business. Some of the transfers were labeled as repayments. Others were described as consulting fees supposedly paid to my firm.
I had never received them.
Someone had been using my business’s name to make the company’s finances appear healthier than they were.
And the account showed that money had recently been moved into an account controlled by my father.
That was why Mom had panicked when I mentioned my Christmas present.
I hadn’t merely interrupted their plan to borrow against my house.
I had sent the lender a packet containing copies of the suspicious documents, a written denial of authorization, and a request to investigate the application before any money was released.
The lender had immediately suspended the application and begun reviewing the records.
My present was a locked door.
They had expected to walk through it with my signature.
Instead, they had walked into an investigation.
But Rachel wasn’t finished.
“There’s something else,” she said, placing a printed email on my kitchen table. “This message was attached to the records your brother submitted.”
The email was from my father.
It read:
Once Emily’s signature is on the guarantee, we can transfer the remaining balance and close the old account before anyone connects it to Daniel.
Below it was a reply from my mother.
What about the money from Grandma’s trust?
My hands went cold.
My grandmother had died eighteen months earlier. I knew she’d left money to several family members, but my parents had handled most of the arrangements.
I had assumed everything had been distributed properly.
Rachel looked at me carefully.
“Did your grandmother leave you an inheritance?”
“Yes. A small trust. My parents said the funds were being held until the estate paperwork was complete.”
“Did you ever receive a final accounting?”
“No.”
Rachel turned her laptop toward me.
“We need to find out whether these two things are connected.”
Then my phone lit up with a message from Daniel.
You have no idea what Dad did with Grandma’s money. If you keep pushing, all of us could go down.
Before I could respond, another message appeared.
Meet me alone tomorrow. There’s something you need to see before Mom and Dad destroy it.
I stared at the screen.
For the first time, I wondered whether Daniel had been the mastermind—or whether he had finally realized he was disposable, too.
I forwarded both messages to Rachel.
Then I agreed to meet him.
But I didn’t tell him that my attorney would be watching from a nearby table.
Because if Daniel was finally ready to tell the truth, I needed to know one thing first:
Was he trying to save me—or save himself?
Daniel chose a diner outside Columbus, far enough from our parents’ neighborhood that he apparently believed nobody would recognize his car.
He arrived twenty minutes late.
He looked exhausted. His shirt was wrinkled, his eyes were bloodshot, and he kept checking the parking lot as if someone might follow him inside.
“You actually came,” he said.
“You said you had something to show me.”
He slid into the booth and placed a thick manila folder on the table.
“Before you look at that, I need you to understand something. I didn’t start this.”
I folded my hands.
“You submitted the loan application.”
“Dad handled the paperwork.”
“You knew they were using my name.”
Daniel stared at the tabletop.
“I knew they wanted you to guarantee some of the business debt. I didn’t know they were going to use your house as collateral.”
“That distinction won’t help you much.”
“I know.”
For once, my brother didn’t argue, blame me, or remind me that our parents had always treated him differently.
He simply opened the folder.
Inside were bank statements, emails, copies of company registrations, and several pages from my grandmother’s trust records.
The first statement showed a transfer of $92,000.
The receiving account belonged to Carter Family Holdings LLC.
Another transfer, dated three months later, showed $47,500 moving into Daniel’s construction business.
A third payment had gone toward a personal credit line my father controlled.
I looked up.
“Why was Grandma’s trust paying your business expenses?”
Daniel rubbed his face.
“Because Dad said the money was supposed to help the family. He told me Grandma had wanted us to use it to keep the business alive.”
“Did you see a document saying that?”
“No.”
“Did you ask?”
He swallowed.
“I didn’t want to.”
That answer hurt more than I expected.
Daniel had always been the golden child. Our parents paid for his college apartment, helped him buy his first truck, and rescued him whenever a business venture failed. I had paid my own tuition, worked through school, and learned early that asking for help usually meant being reminded of what I owed.
But even Daniel had known our grandmother loved us both.
“She left money for you, too,” he said quietly. “Dad told me your share was being held up by legal fees.”
“How much?”
He hesitated.
“About $160,000.”
I felt the room narrow around me.
I had spent the previous year believing the estate was still being settled. I had accepted my parents’ explanation because I hadn’t wanted to turn Grandma’s death into a fight.
“Where is it?”
“I don’t know where all of it went. But I found these when I started looking through the company records.”
He pushed a printed email toward me.
It was dated four months earlier.
My father had written to a bookkeeper:
Keep the trust transfers separate from the operating account. If the company is audited, we need to show that the money was an authorized family loan.
The bookkeeper had replied:
I need the signed trust authorization before I can classify it that way.
My father’s response was one sentence.
I’ll take care of the signature.
I recognized the initials on the following page.
They were mine.
Not a perfect forgery this time, but close enough that someone unfamiliar with my signature might have accepted it.
I sat back.
“Why are you giving me this now?”
Daniel’s expression crumpled.
“Because Mom called me after you sent that packet to the lender. She said you were going to ruin the family. Dad said if the investigation went any further, they’d tell everyone you approved the transfers and were now trying to avoid your debts.”
He looked directly at me.
“They were going to blame you for everything.”
I believed him.
Not because he had suddenly become trustworthy, but because the documents supported what he was saying.
There was another email in the folder. This one came from my mother to Daniel.
Once Emily signs the guarantee, we can stabilize the company. She has savings, equity, and a clean credit history. She’ll recover eventually. You won’t.
I read it twice.
My mother had never seen me as a daughter whose future mattered.
She had seen me as the emergency fund that never ran out.
Daniel lowered his voice.
“There’s one more thing. Dad has been telling everyone that your company owes him money. He says he invested in your business when you started.”
“He never invested a cent.”
“I know. But he has invoices.”
I examined the papers. They listed consulting services allegedly provided to my company by Carter Family Holdings. The invoices were dated during months when the company hadn’t even been operating.
The amounts totaled $64,000.
“Are these real?”
“No. I checked the business records. Dad created them after your Christmas visit last year.”
My father hadn’t simply been planning to bankrupt me.
He had been building a paper trail designed to make it look as though I owed the family money, while using my identity to support his claims.
The forged loan documents were only one piece of a larger scheme.
I closed the folder.
“Daniel, I’m going to ask you one question. I need the truth.”
He nodded.
“Did you know they were going to do this before Christmas?”
His eyes filled with tears.
“Yes.”
The word sat between us.
“I knew they wanted you to sign the guarantee. I knew Dad was using some of Grandma’s money. I told myself it was temporary. I thought the business would recover and everyone would get paid back.”
“And when you heard them planning to make me bankrupt?”
“I should have stopped them.”
“Yes,” I said. “You should have.”
He didn’t ask me to forgive him.
For the first time in our lives, Daniel understood that admitting the truth did not erase what he had done.
I took the folder to Rachel.
Over the next several days, we organized the records and provided them to the lender, the relevant financial institutions, and the attorney handling my grandmother’s estate. Rachel also advised me to preserve the original messages and avoid discussing the evidence publicly while the investigation was underway.
The process was neither quick nor glamorous.
There were interviews, document requests, and repeated questions about dates, signatures, and transfers. I had to explain why I had trusted my parents with financial records and why I hadn’t questioned the delayed distribution of the trust.
The answers were painful.
I had trusted them because they were my parents.
That was all.
Meanwhile, the lender formally rejected the fraudulent application. No loan was issued against my house, and no valid lien was placed on the property. The lender’s investigation also confirmed that I had not authorized the guarantee.
I received written confirmation and kept copies in a secure file.
For the first time in weeks, I could breathe without wondering whether I would lose my home because of a document I had never signed.
But my parents weren’t finished.
On December 29, Mom arrived at my house without warning.
She carried a pie from the grocery store, the kind she used to bring whenever she wanted to pretend a family argument had never happened.
I didn’t invite her in.
“Emily, we need to talk.”
“We can talk here.”
She looked past me into the house.
“Your father is devastated. Daniel is under tremendous stress. You’ve made a terrible situation much worse.”
“I reported a loan application made in my name without my permission.”
“You could have handled it privately.”
“You forged my signature.”
Her face tightened.
“Watch your language.”
“Then explain the signature.”
She glanced toward the street.
“Your father was trying to help Daniel. The business was struggling. We thought you could support your brother for a little while.”
“With my house?”
“You have a good job. You can afford it.”
I stared at her.
There it was again. The family rule I had grown up with: because I could manage on my own, I was expected to carry everyone else.
“What happened to Grandma’s trust money?”
Mom’s expression changed.
“That’s an entirely separate matter.”
“Then you’ll have no problem providing the accounting.”
She clutched the pie box.
“You’re destroying this family over money.”
“No,” I said. “I’m refusing to let the family destroy me over money.”
She began to cry.
For a moment, I felt the old instinct to comfort her, to apologize, to make the tension disappear.
Then I remembered the email.
She’ll recover eventually. You won’t.
My mother had written those words about me without hesitation.
I didn’t open the door wider.
“Please communicate with Rachel from now on.”
“You can’t shut out your own mother!”
“You made that decision when you decided my future was an acceptable price for Daniel’s.”
She left the pie on my porch and drove away.
I didn’t bring it inside.
In January, the estate attorney completed an independent review of my grandmother’s trust. The records showed that the money designated for me had not been distributed as promised. Some transfers had been recorded as family loans, but the supporting authorizations were missing or questionable.
The attorney also found a signed copy of my grandmother’s original instructions confirming that my share was intended for me alone.
It wasn’t a magical document that instantly returned every dollar. Recovering the money required formal demands, further review, and cooperation from the financial institutions involved.
But it established something crucial: my parents had no authority to use my inheritance as their own.
The investigation continued for months.
My father eventually admitted that he had prepared the loan paperwork and directed the transfers. He claimed he believed he could repay the money once Daniel’s business recovered. My mother acknowledged that she had known about the plan to use my credit, although she denied intending to leave me permanently responsible for the debts.
Their explanations did not undo the records.
Daniel cooperated with the review, supplied additional documents, and accepted responsibility for his part in the scheme. His business still suffered serious financial consequences, and he had to sell equipment and negotiate with creditors. I did not rescue it.
The forged loan was canceled before funding, and the estate’s claims were handled through the appropriate legal process. After negotiations and recovery efforts, a substantial portion of the misused trust funds was returned, while the remaining disputed amounts were addressed through the estate’s legal remedies.
My parents also had to answer for the false invoices they had created against my consultancy.
The consequences were real. Their financial arrangements unraveled, relatives began asking questions, and the family image my mother had carefully maintained could no longer survive on polished Christmas photographs and cheerful Facebook captions.
I never posted the private emails online.
I didn’t need to.
The truth belonged in the records, not in a public argument.
By the following Christmas, my house was quiet.
I decorated a small tree in the living room and invited a few friends who had supported me through the investigation. We ate takeout, laughed about terrible office parties, and exchanged inexpensive gifts.
There was no grand family reunion.
There was no dramatic apology at the door.
And there was no obligation to pretend everything had returned to normal.
On Christmas Eve, Daniel sent me a message.
I know I don’t deserve your trust. I’m sorry I let them do this to you. I won’t ask you to forgive me. I just wanted you to know I’m trying to make things right.
I read it twice before replying.
Keep telling the truth, even when it costs you something. That’s where you start.
It wasn’t forgiveness.
But it was a beginning.
My mother sent one final message a few days later.
I hope you’re happy with what you’ve done to this family.
I looked at the screen for a long time.
Then I typed:
I didn’t create the debt, forge the signatures, or take Grandma’s money. I stopped you from putting those things in my name. Those are not the same.
I sent it, blocked her number, and set my phone aside.
For years, I had believed that being a good daughter meant keeping the peace. I thought that if I worked hard enough, earned enough, and gave enough, eventually my family would stop treating my independence as an insult.
I had been wrong.
Sometimes, the people who call you selfish are simply upset that you have stopped making their choices possible.
My Christmas present hadn’t been an expensive watch or a designer handbag.
It had been a warning to the lender, a record of the truth, and a refusal to sign away my future.
When my mother called that night, furious because the plan had collapsed, she had expected me to panic.
Instead, I had asked whether she enjoyed my little present.
She hadn’t.
But I had finally given myself something far more valuable than her approval: the freedom to live without being afraid of what my own family might take next.
And that was the one thing they could never put on a loan application.