The funeral flowers were still in my father’s living room when my sister-in-law stood up and announced that the entire $11 million estate belonged to her husband. She smiled at me as though I should already be packing my belongings. Attorney Samuel Brooks glanced at me, and we both started laughing. Not because anything about Dad’s death was funny, but because her husband had secretly sold his inheritance rights back to our father three years earlier.
My name is Caroline Whitmore. I’m forty-one, and I live in Charleston, South Carolina. My father, Richard Whitmore, built a successful commercial property business over forty years. My older brother, Nathan, was always treated like the natural successor, although he’d never shown much interest in managing anything.
Nathan’s wife, Vanessa, had been planning her future around Dad’s fortune for years. She talked about buying a waterfront mansion, replacing her car, and spending winters in Europe. At Dad’s funeral, she even asked whether the estate would be distributed before Christmas.
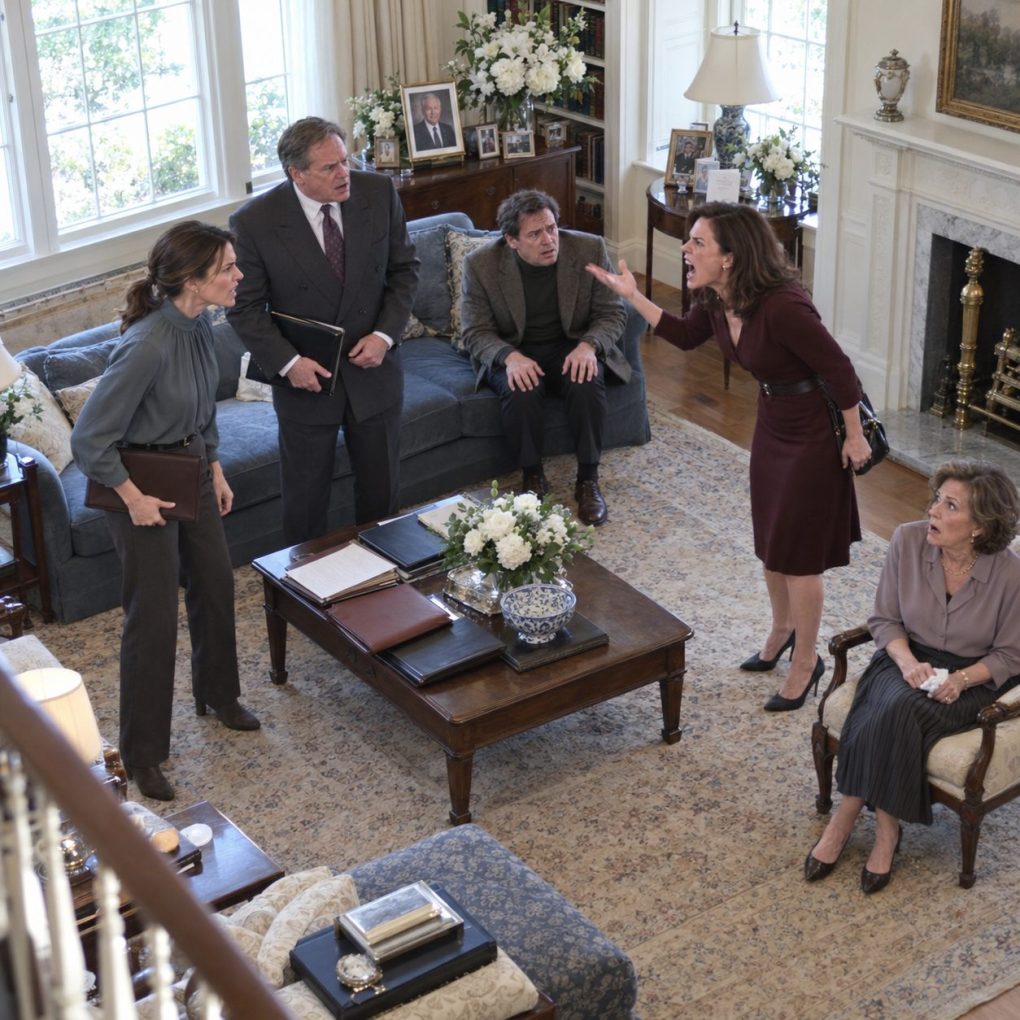
When Samuel gathered us for the will reading, Vanessa barely waited for him to open his folder. She declared that Nathan, as the eldest son, was entitled to everything. Nathan sat beside her, staring at the carpet, his face turning an uncomfortable shade of red.
Samuel calmly explained that South Carolina law didn’t automatically award an entire estate to the eldest child. Vanessa interrupted, insisting Dad had promised Nathan control of the family company. Then she demanded the attorney produce whatever documents were necessary to transfer the assets.
I looked at Nathan. Three years earlier, he’d approached Dad privately because his restaurant investment had collapsed. He owed creditors nearly $900,000 and desperately needed money to avoid losing his home. Dad had agreed to help, but only under carefully documented conditions.
Nathan owned a minority interest in Whitmore Holdings, the family property company. He sold that interest to Dad under an independently valued agreement, receiving $1.15 million. The transaction was completed, the payment cleared, and Nathan signed the transfer documents with his own attorney present.
Vanessa didn’t know. Nathan had told her that Dad had simply advanced him money against his future inheritance. Samuel placed the signed sale agreement on the table, and Vanessa’s confident smile disappeared. She turned toward Nathan, demanding to know why he’d never mentioned it.
Nathan whispered that he’d planned to explain everything eventually. Vanessa grabbed his sleeve and demanded that Samuel continue reading the will. She was certain there had to be something else waiting for her husband.
Samuel opened the next document and announced that Dad’s remaining estate plan had been revised after the business-interest sale. Most of the property interests were now held in a trust, and I was its designated successor trustee. Then Samuel looked directly at Nathan and revealed the condition Dad had attached to his final personal gift.
Samuel explained that Dad had left Nathan a separate cash gift of $250,000. It wasn’t payment for his old company interest, which he’d already sold. The gift was intended to help Nathan rebuild his finances, but Dad had directed that it be held in a trust administered by an independent trustee.
Vanessa immediately demanded that the money be released. Samuel explained that distributions would follow the trust’s written terms, which allowed payments for specified needs and later distributions at defined ages. Nathan wouldn’t receive a check simply because his wife wanted a new house.
I watched my brother’s shoulders sink. He’d spent years allowing Vanessa to believe he was waiting to inherit millions. In reality, he’d received substantial money from Dad, used most of it to settle his debts, and never told her how close he’d come to financial ruin.
Vanessa accused me of manipulating our father during his final illness. I told her that Dad had revised his estate documents while still managing his own affairs and receiving independent legal advice. Samuel confirmed that the relevant records documented those meetings and the execution of the documents.
The estimated $11 million estate included commercial property interests, investment accounts, and Dad’s residence. The figure represented an approximate gross valuation, not an amount of cash available for immediate distribution. Estate expenses, taxes, and outstanding obligations still had to be reviewed.
Dad had named me successor trustee because I’d worked beside him for fifteen years. I handled tenant relationships, renovation budgets, and financial reporting while Nathan pursued unrelated ventures. The trust’s beneficiaries included me, Nathan’s children, and several charitable organizations, according to the distribution provisions.
Vanessa stood so suddenly that her chair scraped across the floor. She demanded to know whether my children would benefit while her husband received only a restricted gift. Samuel explained that the trust documents identified beneficiaries and their respective interests, and that marriage to a beneficiary didn’t create an independent entitlement.
Nathan finally spoke. He admitted that he’d concealed the sale because he was ashamed of losing his investment money. Vanessa stared at him as though he were a stranger, then accused him of ruining the future he’d promised her.
She stormed out, leaving Nathan behind. I expected him to follow, but he remained seated, staring at the signed agreement. After a long silence, he asked whether Dad had left him anything personal, something that wasn’t measured in dollars.
Samuel reached into his briefcase and produced a sealed envelope. Dad had written Nathan a letter shortly before his death, asking that it be delivered after the will reading. When Nathan unfolded it, the first sentence made him cover his face with both hands.
Dad’s letter began with an apology. He wrote that he’d spent too many years rewarding Nathan whenever he failed, hoping money would eventually teach him responsibility. Instead, every rescue had made it easier for Nathan to avoid difficult conversations and depend on someone else.
He explained that the $250,000 trust wasn’t punishment. It was a final attempt to provide Nathan with stability without placing another large sum directly in his hands. Dad also wrote that he loved both his children equally, even though their financial circumstances required different arrangements.
Nathan cried quietly while reading. I’d seen him angry, defensive, and embarrassed, but I’d rarely seen him acknowledge his mistakes. When he finished, he asked Samuel for copies of the documents so he could finally explain everything honestly to Vanessa.
Over the following weeks, the estate administration proceeded through the appropriate legal process. Samuel coordinated the necessary filings, and the trustees began reviewing property valuations, liabilities, and beneficiary records. Nobody received millions overnight, and I didn’t suddenly gain unlimited access to Dad’s assets.
Vanessa hired an attorney to examine the estate documents and Nathan’s earlier sale. Her lawyer requested records concerning the transaction and Dad’s capacity when he signed the relevant agreements. Samuel provided appropriate documentation through counsel, including the valuation, payment records, and evidence of independent legal representation.
After reviewing the materials, Vanessa’s attorney advised that the eldest-son argument had no legal basis. Nathan’s prior sale was a completed business transaction, and Dad’s estate plan contained no promise that Nathan would inherit the company. Vanessa eventually stopped threatening to challenge everything, although her marriage remained strained.
Nathan moved into a smaller apartment while he and Vanessa attended counseling. He found steady work managing operations for a local hospitality company, earning a regular salary for the first time in years. He also began meeting with a financial counselor to understand budgeting and long-term planning.
I continued overseeing the family properties under the trust’s terms, working with accountants and professional advisers. Some tenants needed repairs, and several buildings required expensive maintenance. Managing Dad’s legacy was a responsibility, not a reward that made every problem disappear.
Six months after the funeral, Nathan visited me at Dad’s old house. He brought a framed photograph of the three of us fishing when we were children. He apologized for allowing Vanessa to treat me like an obstacle and admitted he’d spent most of his adult life confusing inheritance with achievement.
We placed the photograph on the mantel, beside Dad’s favorite clock. Nathan said he finally understood why our father had structured his estate the way he did. I told him the most valuable thing Dad had left us wasn’t the property portfolio or the money. It was the chance to stop repeating the same mistakes. Vanessa had entered the will reading expecting an $11 million victory because she’d married the eldest son. Instead, she discovered that wealth wasn’t guaranteed by birth order, marriage, or entitlement. My brother had already received his opportunity and lost much of it. What remained was something harder to obtain than an inheritance: the responsibility to build a life he could honestly call his own.