On my sixty-sixth birthday, my daughter gave her mother-in-law a luxury Hawaii vacation and called her the only mother who made them proud. I received nothing. That evening, I moved my $96,000 savings into a protected account. Hours later, I opened their construction plans and discovered the beautiful bedroom I’d financed was being built for someone else.
My name is Margaret Wilson. I’m a retired elementary school teacher from Portland, Oregon. My husband died eight years ago, leaving me with a modest pension and the savings we’d accumulated together. My only daughter, Jessica, had always known how carefully I managed money.
Six months earlier, Jessica and her husband, Brandon, convinced me to help finance an addition to their suburban home. They promised a private ground-floor suite where I could live comfortably as I grew older, close to family instead of alone.
I paid $9,400 toward architectural plans and preliminary construction expenses. Another $96,000 was scheduled for transfer once the financing arrangements were finalized. Jessica repeatedly assured me the addition was designed around my needs. I believed her because she was my daughter.
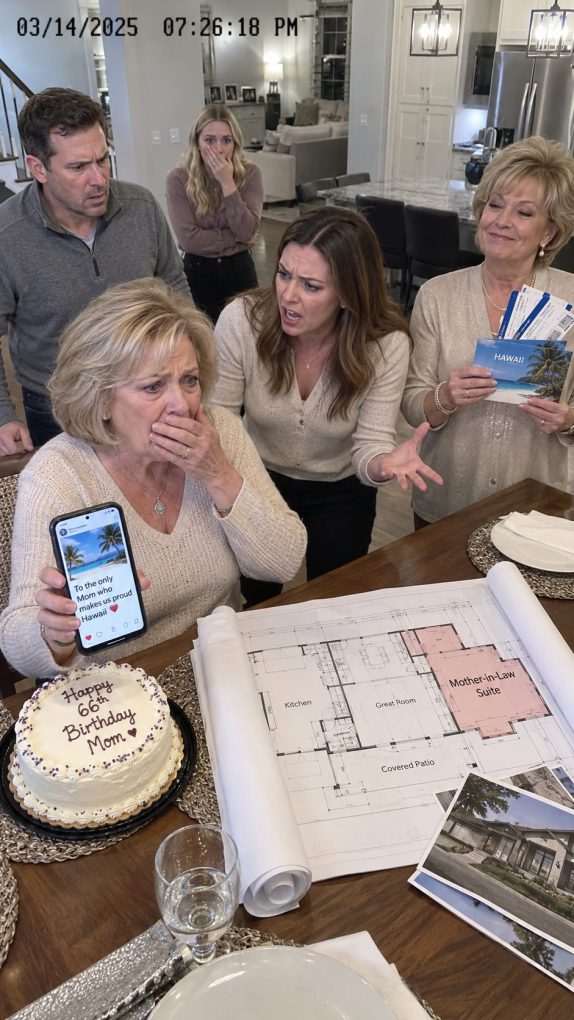
Then came my birthday dinner. Instead of celebrating me, Jessica presented Brandon’s mother, Patricia, with two first-class tickets to Hawaii and a luxury resort reservation. Everyone applauded when Jessica announced that Patricia was the only mother who truly made their family proud.
I sat quietly, staring at the birthday cake nobody had bothered to bring. Patricia hugged Jessica and thanked her for the wonderful surprise. Brandon glanced toward me and asked whether my construction contribution would arrive Monday. Not one person wished me a happy birthday.
I excused myself and drove directly to my bank’s evening-service branch. I canceled the scheduled transfer and moved the $96,000 into a separate savings account under my sole control. Something about their sudden generosity toward Patricia had left me deeply unsettled.
Later that night, I returned to Jessica’s house to collect my forgotten cardigan. While searching the downstairs office, I noticed the latest architectural drawings spread across a desk. I recognized the addition I’d helped finance and opened the folder.
The largest ground-floor bedroom was labeled PATRICIA’S PRIVATE SUITE. It featured a luxury bathroom, garden entrance, and sitting room. My name appeared beside a tiny converted storage room marked TEMPORARY GUEST ACCOMMODATION. The beautiful retirement suite Jessica had promised me was never intended for me.
Then I discovered an attached financing statement listing my $96,000 as an irrevocable family gift. Beneath it was a signature resembling mine. I had never signed that document. Suddenly, I understood why Brandon desperately wanted the transfer completed. They weren’t preparing a home for me. They were using my retirement savings to build one for Patricia.
I photographed every page before leaving the office. My hands shook as I drove home. For six months, I’d imagined growing old beside my daughter, helping with family dinners and watching my grandchildren play in the garden. Now those dreams felt deliberately manufactured to obtain my money.
The following morning, I contacted attorney Rebecca Hayes, who specialized in estate and property matters. She reviewed the drawings and financing statement, then asked whether Jessica had provided any written agreement guaranteeing my right to occupy the promised suite. I admitted she’d repeatedly postponed signing anything.
Rebecca explained that paying for construction on someone else’s property wouldn’t automatically give me ownership or lifelong housing rights. The supposed gift letter was even more concerning. If submitted as genuine, it could misrepresent my intentions to the lender and expose me to unnecessary financial disputes.
We contacted the mortgage lender’s compliance department. Its representative confirmed that Brandon had submitted the gift statement during the construction financing process. However, the lender had not yet received the promised funds and had not completed its approval. Rebecca formally disputed the signature.
Within hours, Jessica called screaming. Brandon’s loan officer had suspended consideration of their financing application pending verification. Jessica demanded to know why I’d withdrawn my money without warning. I calmly asked why Patricia’s name appeared on the suite I’d been promised.
For several seconds, she said nothing. Then she claimed Patricia needed the larger bedroom because of her arthritis. I could still stay in the converted office, Jessica explained, and share their kitchen whenever I wanted. She spoke as though she’d offered me something generous.
I reminded her that I had paid for the plans and was expected to contribute nearly another hundred thousand dollars. Jessica snapped that I was being selfish. Brandon joined the call, insisting my money was a family contribution, not payment for a particular room.
I asked why the financing statement carried a signature I’d never provided. Brandon suddenly became cautious. He claimed Jessica had uploaded an old signature sample because the lender needed the documents quickly. He promised they’d obtain proper authorization afterward. Rebecca had warned me that excuse changed nothing.
That afternoon, Patricia called unexpectedly. She had discovered the truth during an argument with Brandon. Jessica had told her the new suite was being financed through their own savings. Patricia sounded shaken when she realized the construction depended on my retirement fund.
Then she revealed something else. Brandon had promised her exclusive use of the suite for life, while telling me I would receive the same privilege. Two mothers had been promised one room, but only one had been expected to pay. I finally understood that my daughter hadn’t simply preferred her mother-in-law. She had built an entire financial plan around deceiving me.
Rebecca demanded that Jessica and Brandon withdraw the disputed gift statement and correct their financing application. The lender opened an internal review and requested fresh documentation. Without my contribution, their construction budget no longer worked. The project was suspended before major building began.
Jessica accused me of ruining their future. She claimed they’d already purchased expensive furniture and committed to contractors. I reminded her that those decisions were made without my informed agreement. My attorney also documented the $9,400 I’d already spent, although recovering that money would require separate negotiations.
Patricia canceled her plans to move into the new suite. She told Brandon she refused to occupy a room financed through deception. The Hawaii vacation had been a gift from Jessica and Brandon, but learning what they’d done to me made her uncomfortable accepting their hospitality.
Two weeks later, Jessica appeared at my door carrying the architectural drawings. She’d marked out Patricia’s name and written mine over it. She offered to restore the original arrangement if I transferred the money immediately. I asked whether she thought changing a label could restore my trust.
For the first time, Jessica began crying. She admitted that Brandon wanted his mother living with them because Patricia had promised to help finance his business someday. They had assumed I would accept a smaller room rather than risk losing contact with my grandchildren.
I told her how deeply that hurt. I’d spent decades putting her needs before mine, helping with tuition, childcare, and emergencies. Yet on my birthday, she’d publicly declared another woman more worthy of respect while privately arranging to spend nearly everything I’d saved.
Jessica apologized, but I refused to release the money. Through Rebecca, we negotiated reimbursement of the preliminary expenses I’d paid. The couple agreed to repay the documented $9,400 in installments. Their lender required corrected paperwork before considering any future construction financing.
Over the following months, I found a comfortable single-story condominium near a park. I used part of my protected savings for the down payment and kept the remainder invested for retirement. My new home had wide doorways, a sunny bedroom, and a garden I could maintain myself.
Jessica eventually began visiting without discussing money. Our relationship remained complicated. She acknowledged that she’d treated my retirement security as something she could control. I agreed to rebuild our connection slowly, but made clear that my savings, home, and future decisions would remain mine.
On my sixty-seventh birthday, I invited a few close friends to dinner in my new home. Jessica arrived with flowers and a handwritten card. There were no expensive gifts or extravagant announcements. As I blew out the candles, I remembered the construction plans that exposed everything. My daughter had promised me a room in her house while giving someone else the place I’d paid for. I finally understood that the safest home wasn’t the one a family promised me. It was the one nobody could take away.