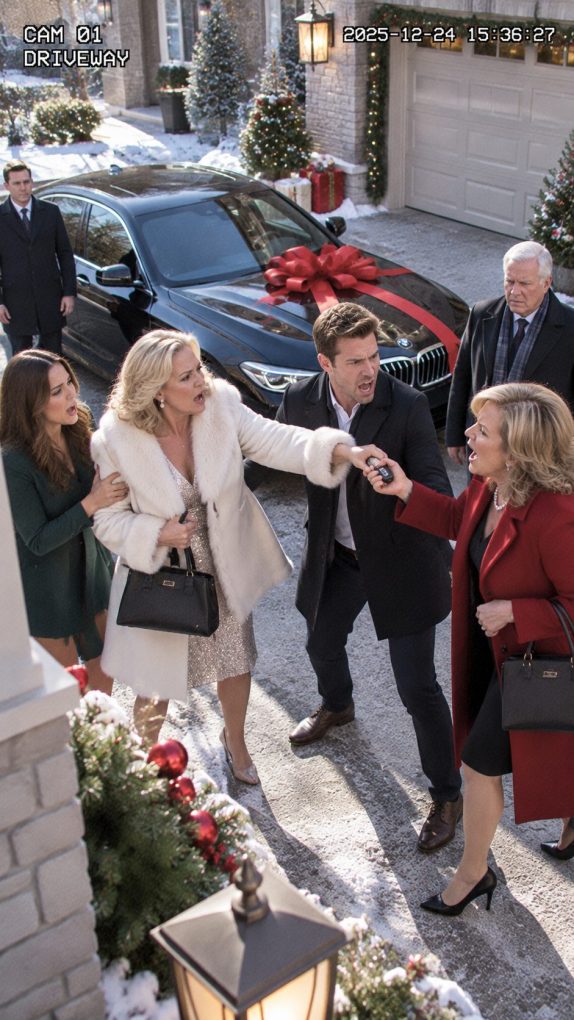
My son parked the BMW directly in the center of his driveway so nobody arriving for Christmas dinner could possibly miss it.
It was midnight blue, still wearing the dealership ribbon, with a giant silver bow stretched across the hood. My daughter-in-law’s mother, Victoria, stood on the porch with both hands over her mouth while Nolan jingled the keys in front of her.
“Merry Christmas,” he said.
Victoria started crying.
My daughter-in-law, Chelsea, filmed everything.
Then Nolan placed the keys in Victoria’s hand and announced to twenty relatives, “You’ve spent your whole life taking care of everyone else. Now it’s our turn to take care of you.”
Everyone applauded.
I did too.
For about three seconds.
Then I saw the temporary registration taped inside the windshield.
The purchase date was December 11.
That was the exact morning I had transferred Nolan $75,000.
Two weeks earlier, he had come to my house outside Denver looking sick with worry. His commercial landscaping company had supposedly been blindsided when a large property-management client delayed payment on several invoices. Payroll was due. Christmas bonuses had already been promised. Fourteen employees, he told me, were counting on him.
“I hate asking you,” he said. “But if I miss payroll right before Christmas, some of these families won’t recover.”
I was sixty-four and recently retired from hospital administration. The money came from a conservative investment account I had spent years building.
I did not gift it to him.
My attorney drafted a short-term loan agreement. The $75,000 was restricted to payroll, employee benefits, taxes, and other ordinary business expenses. Nolan agreed to repay me within six months after the outstanding invoices were collected.
I signed because I believed I was protecting fourteen workers.
Standing in his driveway, I began wondering whether I had purchased a BMW instead.
Inside, Nolan handed me my own Christmas present: a scented candle and a framed photograph of his family.
I thanked him.
I said nothing about the car.
During dinner, Victoria kept protesting that the gift was too much. Nolan laughed.
“Business has been great. Let me enjoy doing something nice.”
My fork stopped halfway to my mouth.
Across the table, Chelsea saw my face.
She immediately looked away.
That told me more than Nolan’s speech did.
Later, while everyone opened presents, I stepped into the laundry room and checked my banking app. The $75,000 transfer had gone to Nolan’s business account exactly as agreed.
I could not see where it went afterward.
But my loan agreement required monthly accounting until repayment.
Nolan had sent me none.
When I walked back toward the kitchen, I heard Chelsea whispering behind the pantry door.
“You should have waited until after Christmas.”
Nolan answered, “Mom isn’t going to ask questions.”
“She gave you that money for the company.”
“I’ll replace it when the Hawthorne payment clears.”
“And if it doesn’t?”
He laughed softly.
“She’s my mother. What’s she going to do, sue me?”
I stood perfectly still.
Then Chelsea said something worse.
“What about the employee bonuses?”
Nolan lowered his voice.
“They can wait until January.”
I looked through the doorway at fourteen unopened Christmas cards sitting on the counter—cards from employees who apparently believed Nolan had saved their holiday.
I left without confronting him.
At 8:30 the next morning, I called my attorney.
By noon, we had requested the business records required under the loan agreement.
And three days later, Nolan’s accountant called me personally.
“Mrs. Bennett,” he said carefully, “I think you need to know something before your son sends you the statements.”
I gripped the phone.
“What?”
“The BMW isn’t the only thing your money paid for.”
Nolan’s accountant, Aaron Price, could not simply hand me confidential company records because I was his client’s mother. But the loan agreement required Nolan’s company to provide specific documentation, and once Nolan authorized the response, the numbers began arriving.
The supposed payroll crisis had been exaggerated. Nolan’s company had enough cash to cover regular wages through December. The delayed client payment was real, but it had not placed fourteen jobs in immediate danger.
What Nolan lacked was enough cash to do everything else he wanted while preserving his company balance.
Three days after my $75,000 arrived, his company transferred $61,940 to a BMW dealership. Another $4,800 paid Chelsea and Nolan’s holiday trip deposit. Nearly $3,000 covered a private-club balance.
Only $5,260 remained.
Not one dollar had gone toward employee Christmas bonuses.
I stared at the ledger until the numbers blurred.
My attorney, Mara Ellison, pointed to the section Nolan had signed: funds were restricted to ordinary business expenses, with misuse constituting a default allowing immediate repayment to be demanded.
“We can send notice,” she said. “That doesn’t mean you’ll magically have $75,000 tomorrow.”
“I understand.”
“Are you sure you want to do this?”
I thought about Nolan laughing behind the pantry door.
“Yes.”
The formal default notice went out that afternoon.
Nolan called within eleven minutes.
“You involved a lawyer?”
“You involved one first. Remember the loan agreement?”
“That was paperwork.”
“No. It was an agreement.”
He accused me of trying to ruin Christmas because he had bought Victoria a nice gift. I told him the gift was not my concern. The money used to buy it was.
Then he said the sentence that permanently changed how I heard him.
“You have plenty.”
That was his entire moral defense.
Not that he misunderstood.
Not that the transfer was accidental.
I had enough money, therefore taking it under false pretenses should not matter.
Victoria learned the truth from Chelsea the following day. She called me crying and said she had believed Nolan’s company purchased the BMW after an unusually profitable year.
“I don’t want this car,” she said.
I told her she had done nothing wrong.
She returned it to the dealership herself. Because it had already been titled and driven, the dealership would not unwind the entire transaction at full value, but Nolan sold it back at a significant loss.
The proceeds reduced what he owed me.
He still owed tens of thousands.
Meanwhile, the employee bonuses became public inside the company for a completely different reason. Nolan had told workers the bonuses were delayed because a client failed to pay. One supervisor knew the client’s finance director personally and discovered most invoices had already been settled.
Employees began asking questions.
Two senior crew managers resigned within a month.
Several others followed.
I did not contact a single employee.
Nolan had created that problem himself.
Then Aaron discovered another issue while reconciling year-end accounts. Nolan had recorded part of the BMW payment as a “client development vehicle expense” even though the car was registered to Victoria personally.
Aaron refused to sign off on the classification.
That forced Nolan to amend the books and explain the transaction to his lender.
The bank did not cancel his company.
It did something more realistic and more frightening.
It declined to renew a favorable working-capital line without additional collateral.
And suddenly Nolan needed cash for the exact reason he had originally claimed.
Only now, the emergency was real.
Nolan asked me for another loan in February.
I thought he was joking.
He came to my house alone, looking thinner than he had at Christmas, and placed a cash-flow forecast on my kitchen table. His company had lost two experienced managers, winter contracts were underperforming, and the bank’s decision had tightened everything.
“I can fix this,” he said. “I just need ninety days.”
I shook my head.
“No.”
He stared at me as though I had spoken another language.
“You’re really going to watch my company fail?”
“No. I’m going to let you run your company without using my retirement account as insurance against your decisions.”
He became angry, then apologetic, then angry again.
None of it changed my answer.
Nolan eventually sold a recreational boat, canceled the private-club membership, and took a smaller personal loan secured by assets he actually owned. He also reduced his own salary before cutting additional staff.
That should have happened before he came to me the first time.
My original loan was eventually repaid over ten months rather than six. Mara negotiated a written repayment schedule rather than forcing a lawsuit that would have pushed the company closer to insolvency.
I accepted that because my goal was never to destroy him.
It was to make the agreement real.
Victoria and I became unexpectedly close afterward. She had spent years believing I disliked her because Nolan constantly compared the two of us—her as the “warm” grandmother and me as the “career-focused” one.
I discovered he told her stories about me that resembled the story he told himself.
Apparently, I did not need appreciation because I was “comfortable.”
I did not need invitations because I was “independent.”
I did not need repayment quickly because I was “financially secure.”
Every strength had become permission to give me less.
Chelsea apologized several months later. She admitted she knew where the BMW money came from and convinced herself Nolan would replace it before I noticed.
“Why didn’t you stop him?”
She looked ashamed.
“Because Mom had never had anything that nice.”
Neither had I.
But that was not the point.
Generosity cannot be built from money obtained through deception.
Nolan’s company survived.
Smaller, humbler, and with an outside bookkeeper controlling disbursements above a set amount, but it survived.
He eventually paid the employee bonuses too, although months late.
The following Christmas was completely different.
There was no luxury car in the driveway.
No giant ribbon.
No speech.
Nolan gave Victoria a leather photo album filled with pictures of her grandchildren.
She cried harder than she had over the BMW.
My gift was an envelope.
For a second, everyone became uncomfortable.
Then I opened it.
Inside was the final payment receipt showing Nolan’s loan balance at $0.00.
He had framed a copy.
“I know this is strange,” he said. “But paying you back is the first thing I’ve done all year that actually feels like a gift.”
I looked at him for a long moment.
Then I hugged him.
Not because the money erased what happened.
It did not.
Trust returned far more slowly than principal.
But Nolan had finally learned something I wish I had taught him years earlier.
Love does not mean resources without limits.
Having more than someone else does not make what belongs to you communal property.
And being someone’s mother does not turn a loan into permission to lie.
That first Christmas, Nolan placed a $60,000 BMW in the middle of his driveway because he wanted everyone to see how generous he was.
What nobody could see was the person who had actually paid for it.
A year later, there was nothing expensive in the driveway.
Yet for the first time, my son gave me something worth keeping.
Accountability.