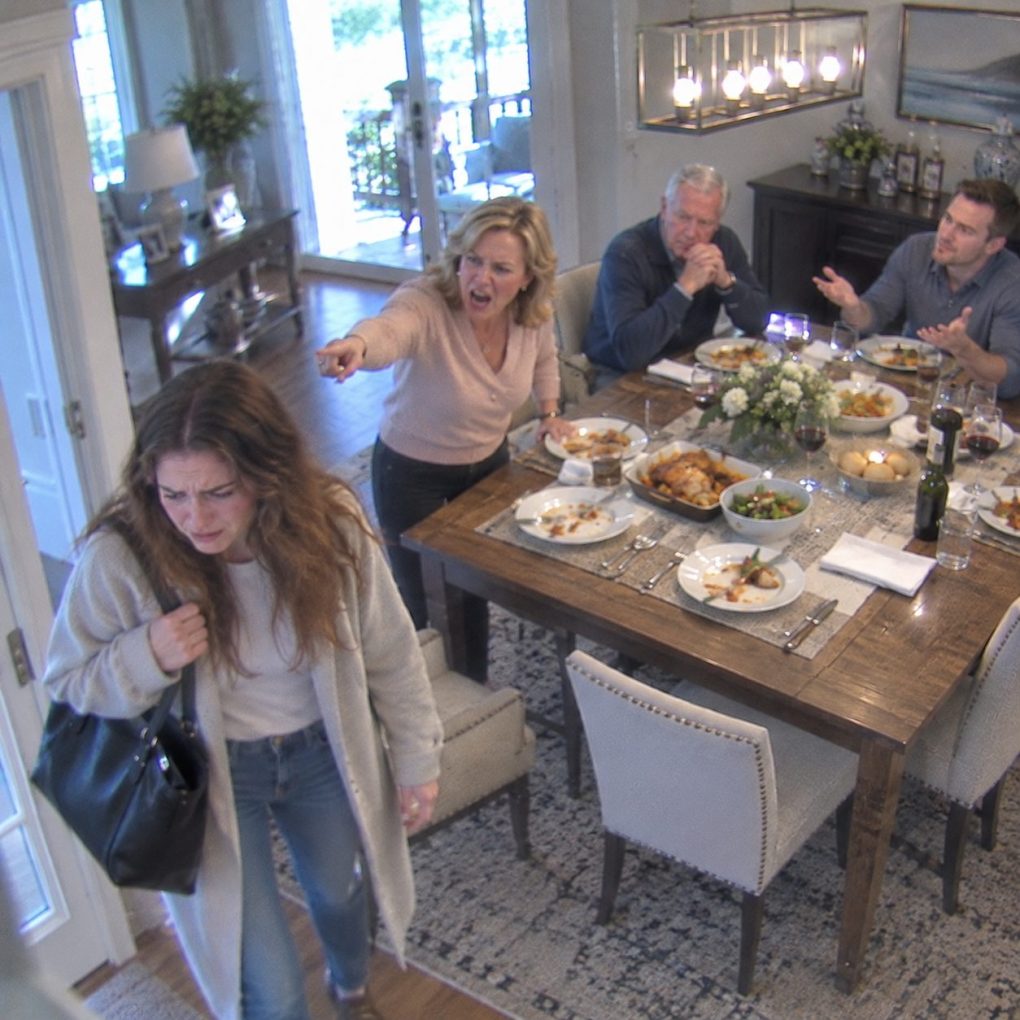
“Pay your brother’s $340,000 debt, or you’re no daughter of mine!”
Mom said it across the Sunday dinner table, between the roast chicken and the birthday cake she’d bought for my brother, Kyle. Nobody had asked how he planned to repay the money his contracting business owed. Somehow, that had become my responsibility.
I set down my fork. “Then I’m not.”
Dad kept staring at his plate. Kyle leaned back, the same little smile he wore at sixteen when he broke my laptop and Mom told me to stop making trouble.
“You have savings, Erin,” Mom said. “You have a good job. Your brother has children.”
“So do I,” I reminded her.
My daughter, Lucy, was nine. She had spent that morning helping me decorate cupcakes to bring to Grandma’s house. Now she was sitting beside me, peeling the paper off one without taking a bite.
“Don’t bring the child into this,” Mom snapped.
I took Lucy’s hand and stood. Dad finally looked up, but only to say, “Can we discuss this when everybody’s calmer?”
I’d been the calm one for seventeen years. When Kyle crashed his truck, I covered the insurance deductible. When his business fell behind on payroll, I lent him $12,000 that never came back. During Mom’s knee replacement, I drove to Dayton after work three evenings a week with groceries in the trunk. Each time, I told myself this was what family did.
But no one had asked whether Lucy needed anything.
At home, she placed the untouched cupcake on the counter. “Grandma doesn’t mean you’re not her daughter, right?”
I wanted to tell her no. Instead, I wrapped the cupcake in foil and said, “What Grandma said wasn’t okay.”
That night, after Lucy was asleep, I called my attorney, Rebecca Lane. She advised me not to sign any financial papers, to keep my messages, and to check my credit. My accounts looked normal. I thought the worst part was over.
Three weeks later, an alert from my credit-monitoring service arrived while I was packing Lucy’s lunch: New mortgage inquiry — $340,000 application.
I hadn’t applied for a mortgage.
I called the lender’s fraud department. After verifying my identity, they confirmed someone had listed me as a co-borrower on a cash-out loan against a house in Dayton.
Mom’s house.
The contact address was hers. The income documentation had my name.
Then the representative gave me the application date.
It had been submitted the Saturday before Mom threatened to erase me from the family.
The lender stopped the application for investigation before any money was released. The closing hadn’t happened, but my signature had already appeared on electronic consent forms, and an old pay statement had been uploaded as if I’d provided it.
I recognized the document. Four years earlier, when Mom refinanced her house, I’d helped her organize her paperwork. She’d kept a blue folder of copies in the hall cabinet, including an old tax return and a scan of my driver’s license.
I filed an identity-theft report, froze my credit at all three bureaus, and gave the lender written notice that I had authorized nothing. Rebecca helped me request the application and ask that the fraudulent inquiry be removed. No one promised it would be fixed by lunchtime.
Mom called after the lender contacted her.
“You had no right to embarrass us,” she said.
I was standing beside Lucy’s school backpack. A tiny plastic dinosaur hung from its zipper; Dad had bought it for her when she started first grade.
“You used my name on a loan.”
“We weren’t going to make you pay it.”
“Then why did you need my income?”
She breathed hard into the phone. “You have no idea what your brother stands to lose.”
I thought about how Mom used to sit with me at the kitchen table when I was little, tracing multiplication problems in pencil until I understood. I’d spent years believing she was hardest on me because she knew I could handle it. Hearing her defend the forgery, I wondered when confidence in me had become permission to use me.
Kyle texted next: If you ruin this, the house goes. Hope you can live with that.
Dad arrived that evening without warning. He carried the blue folder under one arm, its corners softened from years in the cabinet.
“I should have spoken at dinner,” he said.
He laid the papers on my counter. There was a personal guarantee, signed by Mom two years earlier. Kyle had borrowed against equipment for his company, and she had guaranteed the debt. His business had collapsed; the lender was demanding payment from both of them.
“Mom said it was Kyle’s debt,” I whispered.
“It is,” Dad said. “But she put herself on the hook for it. I found out when the demand letter came.”
He turned over the final page: the lender’s notice of default. The balance was $340,000, including charges.
And at the bottom, in Mom’s handwriting, she had written two words beside my name.
Only option.
Dad stayed while I put Lucy to bed. I had promised myself I wouldn’t cry where she could hear me, but I stood outside her room listening to her turn pages and felt the old reflex to fix everything.
When I came back, Dad was washing the two mugs we’d used. He always washed dishes when he couldn’t find words.
“You knew she wanted me to take over the loan,” I said.
“I knew she planned to ask you for help. I didn’t know about the forged application.” He put the mug down. “I should have asked more questions.”
That was the closest he’d come to admitting that his silence had helped her.
Rebecca arranged for the lender to receive my sworn identity-theft statement and supporting records. Its investigation found that the consent forms had been submitted using an email account controlled by Kyle, and the loan was canceled before closing. With the investigation documents, I disputed the unauthorized inquiry on my credit reports. It took several weeks and more phone calls than I cared to count, but the entry was removed.
I also filed a police report. An investigator interviewed me and reviewed the documents. I cooperated, but I didn’t try to control whether anyone was charged. I only wanted my identity—and my daughter’s future—left out of their debts.
Mom demanded that I withdraw my complaint. When I refused, she sent a message saying I’d chosen money over family.
I read it sitting in my car outside Lucy’s dance class. Through the window, my daughter was following the teacher with serious concentration, one shoe untied. I’d bought those lessons with the money I’d once sent to Kyle every month.
For the first time, I didn’t answer.
Kyle sold his remaining work trucks and equipment. It covered part of the debt, not all of it. Mom and Dad decided to sell their house rather than take on a new mortgage they couldn’t afford. After paying the lender and the costs of moving, they bought a small condo outside Dayton. It had no formal dining room and no backyard, but it was theirs without an undisclosed guarantee hanging over it.
Dad called me after the move. “Your mother says she misses Lucy.”
“Then she can write to her,” I said. “I’ll decide what’s appropriate to share.”
I wasn’t using my daughter to punish anyone. I just couldn’t teach her that love meant accepting threats, deception, and financial risk because somebody shared her last name.
Months later, a letter arrived from Mom. She wrote that she’d been terrified of losing the house and ashamed of having signed Kyle’s guarantee. She admitted she had convinced herself I would agree eventually, so putting my name on the application felt like getting a head start. It was an explanation, not an excuse. For once, she didn’t ask for anything.
I replied with three sentences. I was glad she was safe. I needed distance. Any relationship we rebuilt would require honesty and respect for my boundaries.
On Lucy’s tenth birthday, we had cake in our small kitchen. She insisted on lighting the candles herself. When she handed me the first slice, she said, “You can have the big one, Mom.”
I thought of the dinner where my place in the family had been measured in dollars.
Then I sat down beside my daughter, took the slice she offered, and let it be enough.