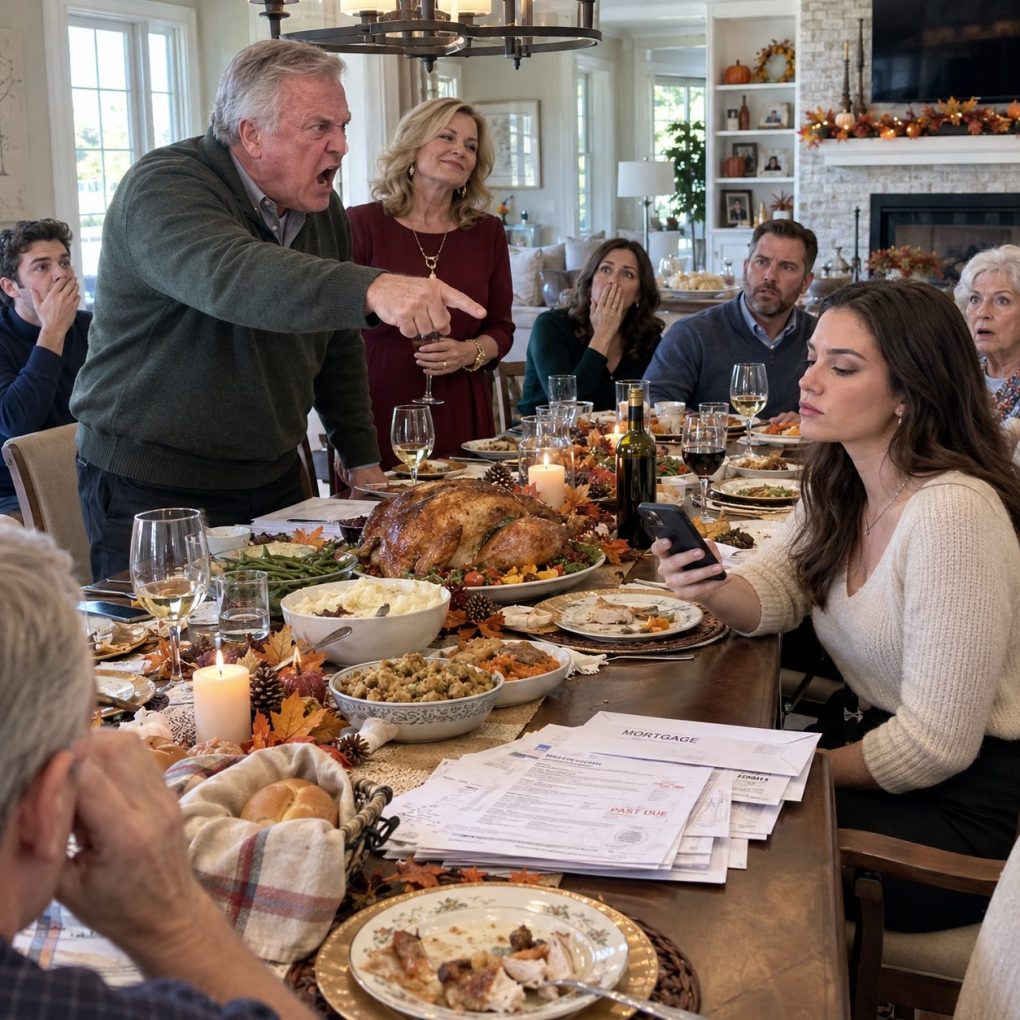
“I disown you. From now on, talk to my lawyer.”
My father’s text arrived at 7:42 on Thanksgiving evening, while I was standing in my kitchen washing a plate I’d eaten dinner from alone.
I read it twice, dried my hands on a dish towel, and typed one word.
Okay.
Then I opened my banking app and canceled every future payment I’d scheduled for his household.
The $2,860 mortgage. The $417 electricity bill. The $189 internet and television package. Even the $340 monthly transfer I’d labeled Dad’s prescriptions.
For three years, those payments had gone out of my account automatically.
My father, Robert Whitaker, lived in a beautiful five-bedroom house outside Charlotte, North Carolina, with his second wife, Vanessa.
I lived forty minutes away in a two-bedroom townhouse, driving a Honda with 168,000 miles on it.
He called me ungrateful.
I called it enough.
The argument had started that afternoon when Vanessa announced she wanted a new SUV for Christmas. Dad expected me to contribute $15,000 toward the down payment.
“After all, you don’t have children,” Vanessa said, casually slicing another piece of pumpkin pie. “What else are you spending your money on?”
I was thirty-nine, a hospital administrator who’d spent fifteen years working toward financial stability. I didn’t explain the fertility treatments I’d undergone before my divorce, or why her question made my hand tighten around my fork.
“I won’t be contributing,” I said.
Dad set down his wineglass.
“You’ve become selfish, Claire.”
I’d heard that word before.
When I refused to pay for their anniversary cruise.
When I asked whether Vanessa could contribute toward the mortgage.
When I told Dad I couldn’t keep missing work to handle his financial paperwork.
He stood up.
“Perhaps you should leave.”
So I did.
That evening, his text made the separation official.
I didn’t cancel payments already completed or touch accounts that belonged to him. I simply stopped the voluntary transfers from my own money, then emailed his attorney requesting that any future communication come through her office.
Before going to bed, I opened the spreadsheet I’d maintained since Dad’s heart surgery.
Thirty-six months of payments.
More than $137,000.
At the bottom was an old email from Dad, sent shortly after Mom died.
Your mother would be proud of how you’re taking care of us.
I stared at those words until the screen dimmed.
Forty-eight hours later, Vanessa called.
She was crying so hard I could barely understand her.
“Claire, your father lied to me. The mortgage isn’t the problem.”
Then she said something that made me sit down.
“Your name is on a loan application I’ve never seen, and the bank says your father submitted it.”
I asked Vanessa to send me photographs of everything she’d found.
Ten minutes later, six images appeared on my phone.
The first showed a home-equity loan application for $175,000. The second listed Dad and Vanessa as borrowers. The third identified me as an additional guarantor, with my salary, employer, and estimated savings entered beneath my name.
At the bottom was a signature that looked almost exactly like mine.
Except I hadn’t signed anything.
“Where did you find this?” I asked.
“In Robert’s desk. I was looking for the mortgage statement because he said you’d stopped paying everything.”
I enlarged the photograph.
The application was dated three weeks earlier.
“Vanessa, don’t sign anything else. I’m contacting the lender.”
She started crying again.
“He told me we had plenty of money. He said his investments were covering our expenses.”
I looked toward the spreadsheet still open on my laptop.
“Those investments were me.”
There was a long silence.
The next morning, I called the lender’s fraud department, disputed the purported guarantee, and requested that the application be investigated. I also placed fraud alerts on my credit files.
Then I contacted a consumer attorney, Rebecca Lawson, and forwarded the documents.
Rebecca called that afternoon.
“Claire, we need the lender to preserve the original application, including its electronic submission records. Don’t confront your father about the signature yet.”
But Dad was already calling.
I let it go to voicemail.
“Claire, you’ve embarrassed Vanessa and me enough. You canceled our mortgage payment without warning. If you don’t straighten this out, my attorney will make sure you regret it.”
I saved the recording.
The mortgage payment wasn’t due for another eleven days. Dad had received my written notice, and the bank hadn’t threatened foreclosure. He was simply furious that the money would now have to come from somewhere else.
That afternoon, my aunt Susan called.
“Your father says you’re trying to take his house.”
“I’m not on the deed, Aunt Susan.”
“He told us you had an agreement to buy it from him.”
I put down my coffee.
“What agreement?”
“He said you’d been paying the mortgage toward eventual ownership.”
Dad had never mentioned such an arrangement to me. The payments had always been voluntary assistance after his surgery.
Susan hesitated.
“Claire, there’s something else. Last spring, he told your uncle that you were helping him qualify for another loan.”
I remembered Dad asking for copies of my pay statements during the previous tax season. He’d said an accountant needed them to prepare paperwork for a family financial plan.
I’d emailed them without thinking.
Now my stomach tightened.
That evening, Vanessa arrived at my townhouse holding a gray folder.
She looked nothing like the woman who’d smiled over pumpkin pie.
“Robert told me the house was almost paid off,” she whispered. “Claire, we still owe $389,000.”
I opened the folder.
There were credit card statements, loan documents, and an insurance policy Dad had recently surrendered for cash.
Then Vanessa pulled out a handwritten note.
“I found this beneath the application.”
It was Dad’s handwriting.
Claire won’t refuse once the paperwork is processed. She always fixes things.
Beneath it was a photocopy of my late mother’s signature.
And when Vanessa explained why Dad had kept it, I finally understood how long he’d been planning to use me.
Vanessa unfolded a second piece of paper.
It was a letter, supposedly written by my mother shortly before she died.
Claire has always been the responsible one. I know she will continue supporting Robert financially, whatever happens.
Beneath those words was Mom’s signature.
The same careful, looping handwriting I’d seen on birthday cards my entire childhood.
I stared at the date.
March 14.
Mom had been in hospice that week, barely able to hold a spoon. I remembered feeding her peach yogurt while Dad complained in the hallway about the cost of her care.
“She didn’t write this,” I whispered.
Vanessa looked at me.
“I found three drafts in his desk. One had your mother’s signature photocopied at the bottom. He was practicing how to make the letter look authentic.”
I sat with the paper between my hands.
For three years, Dad had told me Mom wanted me to help him. Every time I hesitated over another expense, he’d mention how proud she’d been of me.
I’d mistaken those words for memories.
Now I wondered how many had been rehearsed.
“What did he intend to do with it?” I asked.
“Convince you that refusing him meant betraying your mother.”
I folded the letter and set it beside the loan application.
The following week, the lender confirmed in writing that the disputed application had been suspended pending investigation. I provided identity-verification records and a sworn statement denying I’d authorized the guarantee.
My attorney helped me dispute the fraudulent signature and report the suspected identity misuse.
The application was ultimately withdrawn. No loan was issued against my credit.
Dad’s attorney contacted Rebecca and proposed a meeting.
I agreed, provided all communications went through counsel.
Dad arrived wearing the navy jacket Mom had given him for their last anniversary. He looked smaller than I remembered.
“You’ve turned everyone against me,” he said.
Rebecca placed the disputed application on the table.
“Mr. Whitaker, did Claire authorize you to submit this?”
Dad rubbed his forehead.
“I was going to explain.”
“Did she authorize it?”
“No.”
I watched him stare at his hands.
Then Rebecca showed him the letter.
For the first time, his composure broke.
“Where did you get that?”
“Vanessa found it,” I said.
Dad looked toward the window.
“I was desperate.”
“You could have told me.”
“You would’ve refused.”
I remembered the Thanksgiving table, Vanessa’s question about what I spent my money on, and Dad’s anger when I finally said no.
“Yes,” I replied. “I would have.”
For several moments, nobody spoke.
Then I asked the question I’d carried for three years.
“Dad, when you told me Mom would be proud of me, did you actually believe that? Or were you just making sure I’d keep paying?”
His eyes filled, but he didn’t answer.
And somehow, that was worse.
Over the next four months, Dad and Vanessa sold their house. The proceeds, after settling the mortgage and selling expenses, covered some of their debts, but there was nothing resembling the fortune Dad had claimed.
Vanessa moved into a small apartment and returned to full-time work. Their marriage survived on paper, although she told me they were attending counseling and keeping their finances separate.
Dad had to address the consequences of the false loan application through the lender and the authorities reviewing it. He also lost the easy access to my money that he’d mistaken for a permanent entitlement.
I didn’t pay another mortgage installment.
I didn’t refinance their debts.
And I didn’t answer the messages from relatives who insisted that daughters were supposed to forgive their fathers.
Six months later, I finally replaced my aging Honda.
On the afternoon I brought the new car home, I stopped at a bakery and bought a slice of lemon cake.
It had been Mom’s favorite.
I ate it at my kitchen counter, using the little blue plate she’d given me when I bought my townhouse.
My phone vibrated.
A message from Dad.
I know I can’t undo what happened. I hope someday you’ll let me apologize in person.
I read it, then placed the phone facedown.
Maybe someday.
But not because he needed another payment, another signature, or another person to rescue him.
For years, he’d told me I was a good daughter because I gave him everything he asked for.
The night he disowned me, I thought I’d lost the last piece of family I had left.
What I actually lost was the obligation to keep purchasing his approval.
I finished my cake, washed the blue plate, and left it drying beside the sink.
Then I opened my banking app.
For the first time in three years, every scheduled payment belonged to my own life.
And there was nothing left I needed to cancel.