After 20 years of service, my CEO fired me, laughed at my 50,000 shares, and demanded I sign a waiver. I slid it back unsigned. The CFO turned pale and whispered, “Without his signature, we’re in serious trouble.”
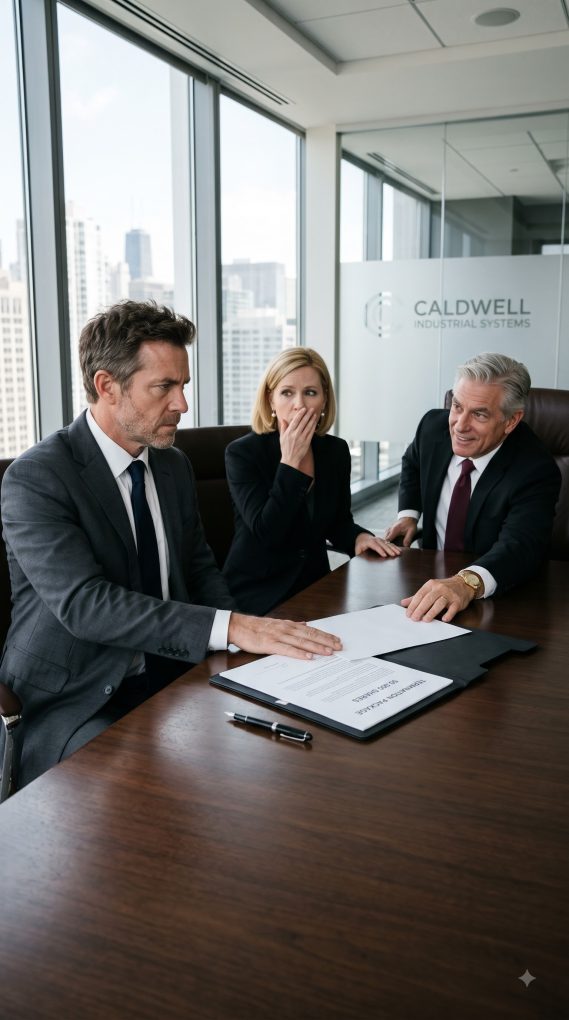
The CEO was still laughing when he slid the waiver across the conference table.
“Twenty years of loyalty, and this is what you get,” Richard Caldwell said, leaning back in his leather chair. “Fifty thousand shares that nobody wants. Good luck cashing them.”
Three executives chuckled nervously.
I didn’t.
My name is Daniel Mercer, and until ten minutes ago, I had been the senior vice president of operations at Caldwell Industrial Systems. I had spent two decades building the company from a struggling regional manufacturer into a business with factories in six states and contracts worth hundreds of millions of dollars.
Now, at fifty-two, I was being fired like a disposable employee.
Richard tapped the waiver with one manicured finger.
“Sign it, and you’ll receive twelve weeks of severance. Refuse, and our lawyers will make sure you leave with nothing. The agreement also confirms you have no remaining claims against the company, including any rights connected to your stock.”
I looked at the document.
Then I looked at the fifty thousand shares listed in the termination packet.
“You’re saying these are worthless?” I asked.
Richard burst out laughing.
“Absolutely. They’re restricted shares, Daniel. You can’t sell them without approval. And since you’re no longer employed here, you can forget about approval.”
My hands tightened beneath the table.
For twenty years, I had missed birthdays, canceled vacations, and answered midnight calls because Richard insisted that loyalty was the foundation of success. When a factory nearly burned down, I coordinated the emergency shutdown. When a supplier collapsed, I found a replacement before the production lines stopped.
And when the company faced bankruptcy eight years earlier, I had personally helped negotiate the restructuring that kept hundreds of employees working.
Richard remembered none of it.
Or perhaps he remembered everything and simply didn’t care.
“You have until five o’clock,” he said. “After that, the offer disappears.”
I picked up the waiver.
The CFO, Margaret Ellis, had been silent throughout the meeting. But when I turned to the final page, I noticed her eyes fixed on a paragraph near the bottom.
Her face suddenly lost its color.
“Richard,” she whispered, “are you absolutely certain you want him to sign this?”
Richard frowned. “What are you talking about?”
Margaret leaned closer and pointed at the document.
I followed her finger to a clause referencing the company’s original restructuring agreement.
Then I understood why she looked terrified.
Richard had spent the entire meeting mocking my fifty thousand shares.
But the waiver he wanted me to sign wasn’t simply giving up my stock.
It contained language that could release the company from an obligation it had carried for eight years.
I slowly placed the document back on the table.
Unsigned.
Richard’s smile vanished.
“Daniel, don’t play games with me.”
I stood, straightened my jacket, and pushed the waiver toward him.
“I’m not playing games, Richard. I’m just not signing something you clearly haven’t bothered to read.”
Margaret abruptly rose from her chair.
“Richard,” she said, her voice trembling, “without that signature…”
She stopped.
The CEO turned toward her.
“Without what signature?”
Margaret looked at me, then at the document, and finally at the man who had just fired me.
“Without Daniel’s signature, we may have a very serious problem.”
And for the first time in twenty years, Richard Caldwell looked afraid.
I had walked into that room expecting to lose my job. I walked out realizing that my former boss might have made the most expensive mistake of his career. But Margaret knew something neither of us had said aloud, and she was about to reveal why those supposedly worthless shares mattered far more than anyone at the table understood.
Richard slammed his palm against the table.
“Somebody explain what is happening. Now.”
Margaret closed the conference room door and lowered her voice.
“The restructuring agreement from eight years ago,” she said. “Daniel’s shares were issued under the employee retention provisions. If he signs this waiver, we may be able to argue that he surrendered certain rights. But if he doesn’t…”
“If he doesn’t, what?” Richard snapped.
Margaret swallowed.
“The company may still be bound by the original conversion agreement.”
Richard stared at her.
“That agreement expired years ago.”
“No,” she replied. “The employment incentives expired. The financial provisions did not.”
I watched Richard’s expression change from irritation to disbelief.
Eight years earlier, Caldwell Industrial Systems had nearly collapsed under $140 million in debt. Three major customers had canceled contracts, and our primary lender was preparing to seize several manufacturing facilities.
I had spent months working with the company’s lawyers, bankers, and restructuring consultants. We eventually secured an agreement that kept the factories open, protected hundreds of jobs, and gave participating employees a chance to share in the company’s recovery.
My fifty thousand shares were part of that arrangement.
But there was another provision.
One that Richard had never discussed publicly.
“Get legal counsel in here,” he ordered.
Margaret hesitated. “Richard, our outside counsel is already reviewing the restructuring documents. They requested the original employee agreements last week.”
“Why wasn’t I informed?”
“Because you instructed us to classify the matter as routine personnel administration.”
Richard’s jaw tightened.
He turned toward me.
“What exactly do you know?”
I pulled out my chair and sat down again.
“Enough to know those shares weren’t a gift. They were part of a negotiated agreement.”
“They were incentive compensation,” he barked.
“No. The incentive compensation was separate. You know that.”
His face reddened.
For the first time, I raised my voice.
“Don’t you dare stand there and tell me I don’t understand the company I helped save.”
The room fell silent.
Richard pointed at the door. “You’re terminated. Your access is revoked. Security will escort you out.”
“Fine,” I said. “But I’m taking a copy of my employment records and the stock documents I’m legally entitled to receive.”
“You’ll get nothing until our attorneys approve it.”
Margaret looked at him sharply.
“That is not how this works.”
Before Richard could answer, her phone vibrated. She read the message, and her fingers began to shake.
“What is it?” he demanded.
She turned the screen toward him.
It was an email from the company’s outside counsel.
The subject line read: URGENT: ORIGINAL EQUITY AGREEMENT AND PENDING TRANSACTION.
Richard read the first paragraph.
Then he read it again.
His face went completely white.
“What pending transaction?” I asked.
Neither of them answered.
I reached for my briefcase.
Margaret finally spoke.
“Daniel, you need to understand something. The board approved a transaction this morning. The company is scheduled to be acquired next week.”
I stared at her.
“By whom?”
“Bennett Capital.”
I knew the name. Bennett Capital was a private equity firm that had spent months negotiating to acquire Caldwell Industrial Systems.
Margaret continued.
“The purchase price assumes all outstanding employee equity obligations have been settled. If your shares carry the rights described in the original agreement, the transaction documents may be materially inaccurate.”
Richard shoved the email away.
“This is a technicality. We can amend the agreement.”
“Not without the required approvals,” Margaret said.
“And we can certainly amend it without Daniel.”
She looked at him with an expression I had never seen before.
“No, Richard. We can’t.”
My phone rang.
It was my attorney, James Porter, who had represented me during the original restructuring.
I answered on speaker.
“Daniel,” he said urgently, “I’ve just received notice of your termination. Do not sign anything. More importantly, do not agree to surrender or transfer your shares.”
Richard lunged toward the phone.
“Porter, this is a confidential corporate matter.”
James ignored him.
“Daniel, there’s something you need to know. The original agreement contains a change-of-control provision. If the company is sold under the conditions currently proposed, your shares may qualify for conversion into the acquisition consideration.”
I felt my stomach tighten.
“Meaning?”
“Meaning they may be worth substantially more than the company has been telling you.”
Richard suddenly shouted, “That’s not what the agreement says!”
James paused.
Then he delivered the sentence that changed everything.
“Richard, I suggest you read Section 8.4 again. Because if Daniel’s shares qualify under that provision, he isn’t the only employee with a claim.”
Margaret slowly sat down.
“How many?” she whispered.
James answered.
“Three hundred and twelve.”
Richard looked as though someone had struck him.
But James wasn’t finished.
“And there’s one more problem. The board’s acquisition committee has already received evidence that certain employee equity records were altered after the original restructuring.”
I stared at Richard.
He stared back at me.
For the first time, I wondered whether firing me had been the point all along.
Or whether Richard had been trying to silence the one person who could prove what he’d done.
For several seconds, nobody spoke.
Then Richard grabbed the phone.
“This call is over,” he shouted. “Daniel is a former employee, and he has no authority to interfere with this transaction.”
James’s voice remained calm.
“That’s precisely why you should stop talking and let your attorneys handle this.”
Richard ended the call.
He stood at the head of the table, breathing hard, while Margaret gathered the documents scattered across the polished wood.
“Everyone out,” he ordered.
Nobody moved.
Margaret finally looked up.
“Richard, the acquisition committee meets at four. If we don’t disclose this issue before then, we could expose the company to serious legal consequences.”
“I’m not blowing up a billion-dollar deal over an old employee stock agreement.”
“Then you should have thought about that before firing the person whose signature you needed.”
Richard turned toward her.
“I don’t need his signature.”
“Then why did you put a waiver in front of him?”
He had no answer.
I rose and collected my briefcase.
“I’m leaving. My attorney will communicate with yours.”
Richard stepped into my path.
“Daniel, let’s be reasonable.”
The sudden change in his voice was almost insulting.
Twenty minutes earlier, he had laughed at my twenty years of service. Now he was speaking as though we were old friends negotiating a minor disagreement.
“You’ve worked here a long time,” he continued. “I don’t want this to become unpleasant. Sign a revised agreement, and we’ll improve your severance.”
“How much?”
He glanced at Margaret.
“Six months’ salary. Perhaps a consulting arrangement.”
I looked him directly in the eyes.
“You just told me my shares were worthless.”
“That was an unfortunate choice of words.”
“You called me a liability.”
“I was frustrated.”
“You laughed at me.”
His expression hardened.
“Don’t make this personal.”
I almost laughed myself.
“You made it personal when you decided twenty years of work meant nothing.”
I walked around him and left the conference room.
Two security officers waited outside. They accompanied me to my office while I packed my personal belongings. Nobody spoke. Several employees watched from their desks, clearly aware that something unusual was happening.
My assistant, Lisa, met me by the elevator.
“Daniel, is it true?” she whispered.
“Is what true?”
“That the acquisition could be in trouble.”
I looked at her carefully.
“Where did you hear that?”
“People in finance are talking. They say the employee stock records don’t match the original agreements.”
I felt a chill run through me.
“Lisa, don’t repeat rumors. Keep copies of any employment or equity documents you’re legally entitled to access, and speak to an attorney if you have questions about your rights.”
She nodded.
Then she reached into her desk drawer and handed me a sealed envelope.
“I was told to destroy this yesterday,” she said. “I didn’t know what it was, but your name was on it.”
Inside was a printed spreadsheet.
It listed employee stock allocations from the original restructuring, including my fifty thousand shares and the allocations of 311 other employees.
Beside each name were two columns: original allocation and current recorded allocation.
For most employees, the numbers differed dramatically.
Some people had lost half their shares. Others had lost nearly everything.
At the bottom was a note referencing an internal accounting adjustment approved by Richard Caldwell three years earlier.
I photographed the document and called James.
“Don’t distribute that,” he told me immediately. “Preserve it exactly as received. Tell your attorney how it came into your possession, and let us determine the lawful way to authenticate it.”
“Does this prove Richard changed the records?”
“Not by itself. A discrepancy can have several explanations. We need the original agreements, the transaction ledger, and the authorization records.”
He paused.
“But if those adjustments were unauthorized, the implications could extend far beyond your termination.”
That evening, James and I reviewed my original paperwork.
The agreement was clear.
My shares had been issued as part of a restructuring arrangement. They were subject to certain restrictions, but they also carried specific rights upon a qualifying change of control. Those rights could not simply be erased by terminating my employment.
The agreement also included a dispute-resolution process and protections for participating employees.
I had never considered myself a wealthy man. I had assumed the shares might eventually provide a comfortable retirement.
Now they could represent a substantial amount of money.
But James warned me not to celebrate.
“We don’t know the final value yet,” he said. “We don’t even know whether every disputed allocation will be restored. First, we establish the facts.”
The following morning, an independent law firm retained by the board contacted us.
The acquisition committee had paused the transaction pending a review of the employee equity records.
Richard had told the board that the discrepancy was an administrative error.
The documents suggested otherwise.
And then came the first major twist.
The review uncovered an email from Richard to the company’s former controller, written three years earlier.
The message instructed the controller to move certain employee shares into a reserve account and reclassify the changes as adjustments to unvested compensation.
The controller had replied that the original agreements did not authorize the changes.
Richard’s response was brief.
Make the records consistent with the approved plan. We’ll handle any questions if they arise.
It was not a confession of fraud. There could still be a legitimate explanation for the accounting treatment. But it was enough to trigger a deeper investigation.
The former controller, who had since retired, agreed to provide records to the independent investigators.
According to the documents, Richard had approved the adjustments shortly before the company began preparing for its sale.
The review also found that the proposed acquisition model had treated the disputed shares as extinguished.
That assumption increased the value attributed to the remaining equity and reduced the amount the buyer expected to pay toward employee claims.
If the records were wrong, the purchase price calculations could be wrong, too.
The next surprise came three days later.
Margaret called me.
“Daniel, I need to tell you something before the board meeting.”
“I’m listening.”
“I approved the financial schedules used in the acquisition process. At the time, I relied on the equity ledger provided by the legal and finance teams. I should have demanded the original agreements before certifying the figures.”
“Did you know the shares had been reclassified?”
“I knew there were adjustments. I was told they had been authorized under the compensation plan. I didn’t know the underlying documents might contradict that explanation.”
Her voice broke slightly.
“I should have asked more questions.”
I believed she was genuinely troubled, but I also understood that regret didn’t erase responsibility.
“Tell the independent investigators everything you know,” I said. “And provide the records they request.”
“I intend to.”
She then revealed the final piece of the puzzle.
The board had not needed my signature simply to terminate my employment. Richard’s lawyers had drafted the waiver to obtain a broad release of claims, including claims associated with the original equity agreement.
The waiver was not proof of wrongdoing on its own. Companies routinely seek releases when employees leave.
But its timing mattered.
Richard had wanted the release signed before the acquisition committee reviewed the disputed records.
Had I signed, the company might have argued that I had voluntarily surrendered certain rights. Whether that argument would have succeeded was another question entirely.
My refusal had forced everyone to confront the underlying agreement before the transaction closed.
And now 311 other employees had reason to ask whether their rights had been properly respected.
At the emergency board meeting, Richard arrived with two attorneys and a stack of documents.
He insisted that the accounting changes were legitimate and accused the review team of misunderstanding the company’s compensation structure.
Then the independent counsel presented the original agreements alongside the revised ledgers.
The discrepancies were undeniable.
Richard’s attorneys requested a recess.
When the meeting resumed, the board announced that Richard would step aside as CEO while the investigation continued.
He wasn’t immediately convicted of anything, and the board made no public declaration that he had committed fraud. Instead, it referred the evidence to independent counsel and required a complete reconciliation of the disputed shares.
The acquisition was renegotiated.
Bennett Capital agreed to continue discussions, but only after the equity claims were independently reviewed and the purchase price adjusted to reflect the company’s actual obligations.
For the first time, the employees whose shares had been reclassified had a formal path toward recovering what they were owed.
My attorney negotiated a resolution based on the original agreement and the final verified share count.
The company restored my recognized allocation of fifty thousand shares, subject to the agreement’s terms. When the acquisition eventually closed under revised terms, my eligible shares converted into the consideration specified in the final transaction documents.
The payout was substantial enough to change my retirement plans, but I didn’t suddenly become a billionaire. The final amount depended on the agreed purchase price, the conversion terms, and the deductions specified in the transaction.
The other affected employees received individual reconciliations and compensation according to their verified rights.
Some recovered more than they expected. Others received less than they had hoped. The process was imperfect, expensive, and exhausting, but it was conducted with independent oversight rather than Richard’s assurances.
The investigation also concluded that Richard had authorized accounting changes without sufficient contractual support and had failed to disclose material uncertainties to the board. He resigned permanently as part of a settlement that included cooperation with the review and other negotiated terms. Any remaining legal issues were handled separately.
Margaret retained her position after cooperating with investigators and helping correct the records, although the board imposed stricter financial controls and required independent review of future equity transactions.
Six months later, I returned to the headquarters for a meeting with the transition committee.
The conference room looked exactly as it had on the day Richard fired me.
Same polished table. Same leather chairs. Same framed photographs celebrating the company’s growth.
But Richard’s name was no longer on the door.
Margaret met me in the hallway.
“The board wanted to offer you a consulting role,” she said. “They believe your experience would help stabilize operations during the transition.”
I considered it.
For years, I had believed that loyalty meant staying, even when staying cost me time with my family and peace of mind.
Now I understood that loyalty without accountability could become an excuse for exploitation.
“Thank you,” I told her. “But I think my time here is over.”
She nodded.
“I understand.”
Before leaving, I stopped by the factory floor. Employees were working, machines were running, and supervisors were coordinating the next production schedule.
The company had survived.
Not because one executive had been untouchable, but because hundreds of people had continued doing their jobs while the people at the top were forced to answer difficult questions.
I had spent twenty years believing that the company was my responsibility.
In the end, I learned that my responsibility was to do honest work, protect my family, and refuse to sign away my rights just because someone powerful told me they were worthless.
Richard had laughed when he slid that waiver across the table.
He thought I was leaving with nothing.
But the most important thing I took from that room wasn’t the money, the shares, or the vindication.
It was the realization that twenty years of loyalty did not require me to surrender my dignity for one more day.
And I never signed that waiver.