Mom slapped me so hard my birthday candle tipped into the frosting. Across the dining table, my older brother Derek laughed. “Look at her. Thirty-four years old, still a worthless loser.”
“Don’t talk to me like that,” I said, pushing back my chair.
Mom pointed toward the front door. “You will not disrespect your brother in my house.”
“He just called me worthless.”
“Because you’re jealous of what he’s accomplished.”
I stared at her. Derek hadn’t held a steady job in two years. I’d sent him $5,000 every month to cover Mom’s mortgage and bills. I’d done it since Dad died six years earlier. Derek had insisted that Mom would be humiliated if she knew her daughter was supporting her. I’d believed him.
“I’ve done more for this family than you realize,” I said.
Mom slapped me again. “You’re garbage. Get out!”
Derek leaned back, enjoying every second. “Don’t come crawling back when you can’t handle life on your own.”
I picked up my purse and walked out without touching the cake. Neither of them followed me. The next morning, I opened my banking app and canceled the automatic transfer marked Family Support: $5,000 on the first of every month. For once, I didn’t call Derek to explain.
On the second day, he sent three messages calling me dramatic. On the third, he demanded I “fix the payment.” I didn’t answer. Instead, I pulled six years of statements and every mortgage receipt he’d ever forwarded to prove the money was being used properly. Something in the dates bothered me. I searched the county property records, then printed a document that left my hands shaking.
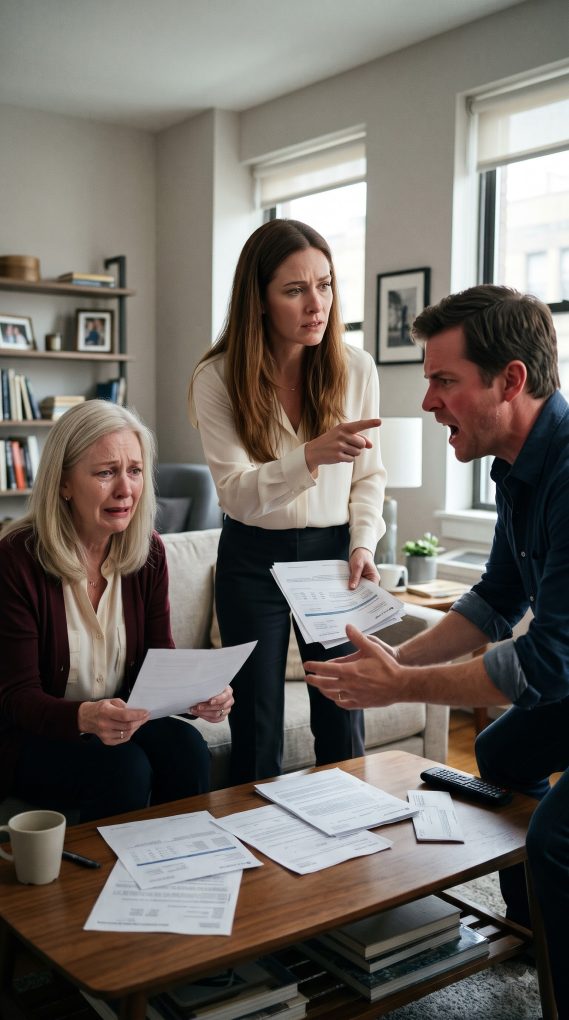
On the fifth day, someone pounded on my apartment door. Mom stood there, pale and trembling. Derek stood behind her, staring at my folder.
“We’re losing the house,” she sobbed. “Derek says you stopped helping him. Please, Claire.” Derek swallowed. “Just one transfer. Please.”
I stayed in the doorway. “Ask your golden boy.”
“I thought he was paying everything,” Mom whispered.
“He was using my money.” I showed her seventy-two transfers of $5,000, followed by the mortgage receipts. “That’s $360,000. I never asked you to thank me. But he let you believe I was nothing.”
Derek reached for the pages. “She’s twisting this.”
“Then explain this.” I turned to the final document: a $300,000 home-equity loan secured against Mom’s house. Her signature appeared beside the date.
Mom read it once, then again. “I never signed this.”
Derek lunged for the folder. And the moment I pulled it away, he said something that made us both go still.
“If you call the police, they’ll come after Claire first.”
“Why would the police come after me?” I asked.
Derek’s eyes darted toward the street. “Because she knows what she did.”
Mom gripped the doorframe. “Stop talking in riddles. Did you borrow money against my house?”
“It’s an investment,” he snapped. “I was going to pay it back.” I let Mom inside. Derek followed us.
“You forged my signature?”
He said nothing. That silence was all the answer she needed.
I moved the folder out of his reach. The county record showed a home-equity loan filed six months earlier. Mom’s house was collateral. Derek had been handling the mail, so notices from the lender never reached her. Now the original mortgage was nearly three payments behind, despite the money I’d continued sending him.
“Where’s the three hundred thousand?” I demanded.
“In a real estate deal. It hasn’t closed.”
“Name the property.”
He couldn’t. Instead, he turned to Mom. “Tell her to start the transfers again. We can still save the house.”
Mom looked at me with an expression I’d never seen before. Not anger. Shame. “You told me you were taking extra shifts,” she said to him. “You said Claire barely paid her own bills.”
“He wanted you to think I needed him,” I said. “And he wanted me to think you were too proud to accept help.”
Mom covered her mouth. For years, Derek had fed us different versions of the same lie. I hadn’t just funded the house. I’d funded the story that made him its hero.
I took out my phone. “I’m calling the lender’s fraud department. Then the police.”
Derek grabbed my wrist. “You do that, and she’ll be homeless.”
I pulled free. “Don’t touch me again.”
He stepped back when Mom raised her voice. “Leave her alone, Derek.”
We called from my kitchen. A bank representative confirmed that the home-equity account had been opened using a digitally submitted application and a notarized authorization bearing Mom’s name. She told us to file a written fraud dispute and a police report immediately. The lender could flag the account for investigation, but she couldn’t promise the lien would disappear overnight.
Derek heard enough. He backed toward the door. “You have no idea what you’ve started.” Then he ran down the stairs.
The next morning, Mom and I met attorney Rebecca Sloan, whom I’d contacted after finding the county record. She told us to preserve every message and requested the full closing and disbursement records with Mom’s authorization. Two days later, she called with a discovery: the loan proceeds had passed through an account listed as Claire Bennett Consulting.
“My name,” I said. “But I don’t own any consulting company.”
Rebecca didn’t smile. “Then someone may have stolen your identity too.”
That afternoon, a detective called about our reports. Investigators had located a business account opened online with my Social Security number and a copy of my driver’s license. The home-equity proceeds had passed through it before being transferred elsewhere. On paper, I looked like the person who had received the stolen money.
I could barely speak. Then my phone lit up with a message from Derek.
Tell them the account is yours, or I’ll make sure Mom loses everything.
I showed Derek’s message to Detective Olivia Grant before I answered a single word. She photographed the screen, then asked me to forward the message to the department’s evidence address.
“Do not negotiate with him,” she said. “If he calls, save the voicemail. We’re already tracing the transfers.”
Mom sat beside me in the interview room, twisting a tissue between her fingers. “I gave him access to my mail,” she said quietly. “I let him keep our important papers in his desk. I thought he was protecting me.”
I wanted to remind her how she’d slapped me twice for standing up for myself. But she already knew. And for once, she wasn’t asking me to fix things with my paycheck.
Rebecca helped us send formal identity-theft affidavits to the bank and the lender. The lender suspended new draws and investigated the disputed lien. Rebecca warned that a fraud investigation wasn’t the same as canceling a debt. The original mortgage was real, overdue, and still Mom’s responsibility.
That afternoon, Mom called Derek herself, with Rebecca listening beside her. “Come home and tell me the truth,” she said.
“I was trying to make us rich,” he replied. “Claire wouldn’t understand risk.”
“Did you sign my name?”
A long pause followed. “I did what I had to. After everything I sacrificed for this family, you owe me some trust.”
Mom ended the call without crying. Rebecca saved the recording they had made with Mom’s permission.
Over the next three weeks, the fraud investigation dismantled Derek’s story. The supposed real estate investment was a company he’d formed with a friend who promised quick profits flipping distressed properties. The company had bought no house. The money had gone into risky investments, personal purchases, and Derek’s debts. A remaining portion was sitting in an account that investigators froze before it disappeared.
The business account in my name had been opened using an old scan of my driver’s license, stored in a family emergency folder at Mom’s house. The contact number was Derek’s. Login records traced to his devices. He had placed my identity between himself and the borrowed money so that, if anyone questioned the transaction, I would appear to be responsible.
But the most damning evidence came from the notary. The authorization supposedly allowing Derek to act for Mom carried a false notarization. The woman whose name appeared on it had never met Mom or witnessed her signature. Derek had built a paper trail of lies.
When detectives arrested him, he called me six times from the county jail. I refused the calls. Through Rebecca, he offered to “make everything right” if I would sign a statement saying I had authorized the business account.
I refused that too.
The criminal case took months. Derek was charged with fraud, forgery, and identity-related offenses. He eventually pleaded guilty. As part of the proceedings, the authorities sought recovery of the funds they could trace, and restitution was ordered. It wouldn’t repay every dollar I had sent over the years, but it meant he could no longer call himself the family’s savior while hiding behind our names.
The lender’s own investigation, followed by legal action, established that Mom had not authorized the home-equity loan. The fraudulent lien was released. By then, however, Mom had faced another truth: even without Derek’s $300,000 debt, she couldn’t afford the original mortgage on her retirement income. My $5,000 payments had hidden that problem for years.
One evening, she came to my apartment carrying an envelope. My stomach tightened when I saw it. I assumed she was bringing another bill.
Instead, she put the house listing agreement on my table.
“I’ve decided to sell,” she said. “The real mortgage will be paid off, and I’ll buy somewhere smaller with what’s left. I spoke with a housing counselor. I’m not asking you for money.”
“Are you sure?”
“No,” she admitted. “I’m terrified. But being afraid doesn’t mean I get to make you responsible for my life.”
Then she placed a second sheet beside the first. It was a handwritten list of every cruel thing she’d said to me that birthday, including the words You’re garbage. At the bottom she’d written: None of it was true. I am sorry.
“I believed Derek because he told me what I wanted to hear,” she said. “That my son was successful. That I had raised a man who would take care of me. When you defended yourself, I punished you for threatening that story.”
I read the page twice. “I needed you to believe me without needing a bank statement first.”
“I know.”
I didn’t hug her. Not then. I told her that an apology mattered, but it didn’t erase six years of silence or two slaps. If she wanted a relationship with me, it would have to be a different one. No secrets. No insults. No asking me to pay for peace.
She nodded. “That’s fair.”
The original lender granted Mom a limited forbearance while she arranged a sale. She sold the house, paid off the real mortgage and arrears, then moved into a modest condo she could afford. She met me for coffee sometimes. We talked about ordinary things, and when we talked about Derek, she no longer asked me to excuse him. Trust returned slowly, through the small promises she actually kept.
A year after that birthday, my banking app reminded me that I’d once scheduled a monthly $5,000 transfer. I looked at the balance I’d finally begun saving toward a home of my own. For six years, I’d paid to keep a roof over my mother’s head while my brother taught her to despise me.
I closed the reminder without restoring the payment.
Helping family should never mean financing your own humiliation. And the best gift I gave myself that year wasn’t revenge. It was the right to say no—and mean it.