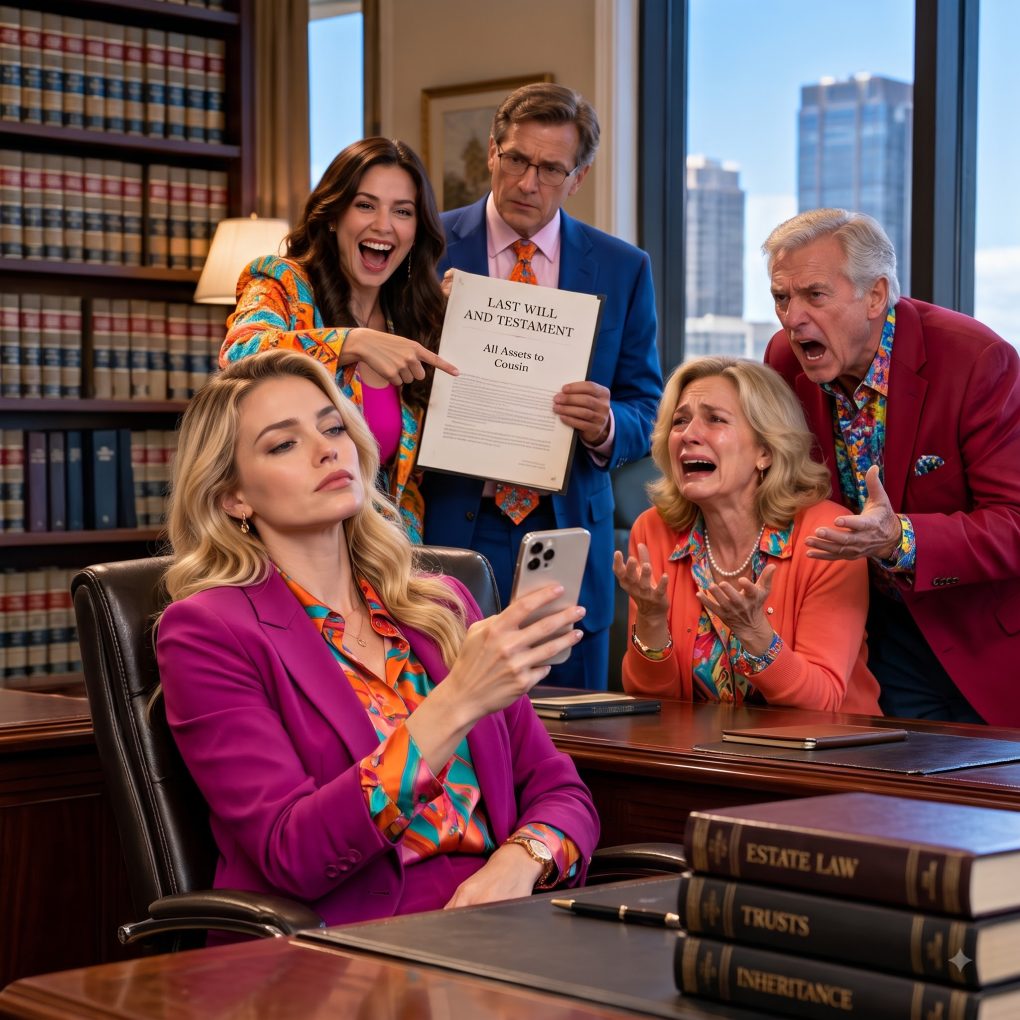
At the lawyer’s office, my parents announced that my cousin would inherit everything while I got nothing. After seven years of paying their mortgage, I quietly stopped every transfer. A month later, Mom texted, “The mortgage is due.” I replied, “Not my problem.” Then my cousin sent me a terrifying document.
“YOU’RE LEAVING EVERYTHING TO MY COUSIN?” My voice cracked inside the attorney’s office. Across the polished mahogany desk, my mother folded her arms while my father stared at the floor. Attorney Richard Collins cleared his throat. “According to the estate planning documents, your cousin Brittany will inherit the family home, the investment accounts, and the remaining assets.” I looked at my parents, waiting for someone to laugh. Nobody did. “And what do I get?” My mother, Diane, answered without hesitation. “Nothing, Emily. Brittany needs the security more than you do.” My cousin Brittany sat beside her, wearing a designer handbag I’d helped pay for indirectly through years of supporting my parents. She smiled. “Don’t take it personally. Some people are simply better at managing family responsibilities.”
I was thirty-four years old, a senior accountant in Charlotte, North Carolina, and the only reason my parents still had their beautiful four-bedroom house. For seven years, I’d quietly paid $2,400 toward their monthly mortgage, covered their property taxes, and transferred money whenever an unexpected expense appeared. My father had retired early after a workplace injury, and my mother insisted they couldn’t survive without my help. I’d sacrificed vacations, postponed buying my own house, and worked overtime to keep them comfortable. Brittany, meanwhile, spent her weekends traveling and posting luxury shopping trips online. Yet somehow, she deserved everything.
“Why didn’t you tell me before I came here?” I asked. Dad finally spoke. “Emily, you’re successful. You don’t need an inheritance.” I swallowed hard. “But you need my money?” Mom’s face hardened. “Don’t be selfish. We raised you.” Brittany laughed softly. “Exactly. Supporting family shouldn’t come with conditions.” I stood, picked up my purse, and looked directly at the attorney. “Just to clarify, these are my parents’ assets, and they can leave them to anyone they want?” He nodded. “Yes.” I forced a smile. “Then I can decide what happens to my own money, too.”
Nobody understood what I meant. Not yet. That afternoon, I canceled every automatic transfer from my bank account. Mortgage contributions. Property tax savings. Insurance reimbursements. Even the $600 monthly allowance I’d been sending Mom. I didn’t argue or announce my decision. I simply stopped paying.
Thirty-one days later, Mom texted me. “Emily, the mortgage is due. Your transfer hasn’t arrived.” I stared at the screen before typing four words. “Not my problem, Mom.” Seconds later, my phone rang. I ignored it. Then a second message appeared. “You can’t do this to us. The bank is threatening action.” I almost felt guilty.
Then Brittany sent me a photograph that made my stomach drop. It showed a mortgage document bearing my signature. Beneath it, she wrote, “Actually, Emily, you might want to reconsider. You’re responsible for more than you realize.”
I had spent seven years believing I was helping my parents keep their home. But the document Brittany sent suggested my family had been hiding something far more serious than an unfair inheritance. And when I examined the signature, I realized someone had made a decision in my name without ever asking me.
I enlarged Brittany’s photograph until the numbers became readable. My name appeared beneath a signature on a $310,000 refinancing agreement. The document was dated eighteen months earlier, when I had been attending a work conference in Chicago. I had never signed it. My hands shook as I called the mortgage company. After verifying my identity, the representative confirmed that my name appeared as a co-borrower. “That isn’t possible,” I whispered. “I never applied for this loan.” The representative immediately transferred me to the fraud department and explained how to file a formal dispute. Within an hour, I had requested copies of the loan documents and contacted an attorney named Sarah Mitchell.
When Sarah examined the photograph, her expression turned serious. “Emily, we need the complete loan file. If someone forged your signature, this could involve mortgage fraud and identity theft.” I called my mother. She answered immediately. “Finally! Are you sending the money?” “Mom, why is my name on your mortgage?” Silence. Then she said, “Your father handled the paperwork.” “Did you forge my signature?” Her voice sharpened. “Don’t use that word. We did what was necessary to protect this family.” I felt physically sick. “You took out a loan using my identity?” Mom began crying. “We were going to tell you eventually.” I ended the call.
Two days later, Sarah obtained preliminary records showing that the refinancing had released $86,000 in cash to my parents. The money wasn’t used to repair their house or cover medical expenses. Most of it had been transferred to an account associated with Brittany’s online fashion boutique. I stared at the bank statements. “They borrowed against the house using my name to finance her business?” Sarah nodded cautiously. “That’s what these records suggest.” Before I could respond, Dad appeared at my office. His face was pale, and his hands trembled. “Emily, please don’t destroy your mother.” I stood. “Then tell me the truth.” He lowered his head. “Brittany convinced us she could double the money in six months. She promised we’d pay everything back before you noticed.”
I almost laughed. “And when she lost it?” Dad wiped his eyes. “She said she needed more time.” Then he revealed something worse. Brittany hadn’t merely received the refinancing money. She had persuaded my parents to sign a contract promising her the house if they died or became permanently incapacitated. The estate plan I’d seen at the attorney’s office was part of that arrangement. “Why would you agree to that?” I demanded. Dad whispered, “Because she threatened to report us for signing your name.”
My stomach turned. Brittany had trapped them using their own dishonesty. But when Sarah investigated the boutique, she discovered another shocking detail. The business had closed eight months earlier. Brittany had continued telling everyone it was thriving while transferring money into accounts connected to a property investment company. Then Sarah received a call from the mortgage lender’s fraud investigator. She listened silently before asking, “Are you absolutely certain?” Her face drained of color. After hanging up, she turned toward me. “Emily, there’s another application using your identity. It was submitted yesterday.” I could barely breathe. “For what?” Sarah swallowed. “A second loan secured by your parents’ house. And the application includes a copy of your driver’s license.” My phone suddenly buzzed. Brittany had sent another message. “If you don’t pay the mortgage by Friday, I’ll make sure you lose everything too.” Beneath it was a photograph of my parents standing beside a moving truck. But the person directing the movers wasn’t Brittany. It was the attorney who had announced I would inherit nothing.
“Sarah, that’s Richard Collins!” I pointed at the photograph on my phone. The attorney who had calmly announced that Brittany would inherit everything was now standing in my parents’ driveway, directing movers toward their front door. Sarah immediately enlarged the image. “Why would an estate attorney be supervising a move?” she asked. I didn’t have an answer, but I knew one thing. My parents were about to lose more than their monthly mortgage payment.
Sarah called Richard’s office while I contacted my father. His phone went straight to voicemail. Mom finally answered after six attempts. “Emily, please don’t come here,” she whispered. “Richard says everything will be fine once we sign the final papers.” My stomach tightened. “What papers?” She hesitated. “The property transfer.” “Mom, don’t sign anything!” A man’s voice interrupted. “Mrs. Carter, we need to finish.” Then the call disconnected.
Sarah grabbed her briefcase. “We’re going over there, but we’re not entering the property without permission or confronting anyone physically. If documents are being signed under pressure, we need witnesses.” Twenty minutes later, we pulled into my parents’ street. A moving truck blocked half the driveway. Brittany stood on the porch wearing an expensive cream-colored suit. Richard was beside her, holding a leather folder. When Brittany saw me, she smiled. “Well, look who decided to care about her family again.”
I climbed out of the car. “What are you doing with my parents’ house?” Richard stepped forward. “Emily, this is a private family matter.” Sarah introduced herself and asked whether my parents were voluntarily signing a transfer. His expression changed. “My clients have appropriate representation.” “Then they can explain their decision without you answering for them,” Sarah replied.
Dad appeared in the doorway, looking exhausted. Mom stood behind him, crying. I approached slowly. “Dad, do you actually want to give Brittany the house?” He looked toward Richard. “We don’t have much choice.” Brittany interrupted. “You had choices. You chose to stop paying.” I shook my head. “I stopped giving away my money. That’s not the same as taking yours.”
Sarah requested a private conversation with my parents. After several tense minutes, Richard reluctantly stepped aside. Dad finally admitted that Brittany had convinced them to transfer ownership of the house to her investment company in exchange for covering their mortgage arrears. But the proposed agreement contained no guaranteed right for my parents to remain in the home. They could have been forced to leave after signing.
“Why didn’t you ask me for help?” I whispered. Mom looked at me with swollen eyes. “Because we knew you’d discovered the loan.” “And you were afraid I’d report you?” She nodded. I felt tears gathering, but I refused to look away. “You used my identity, gave my cousin the money, and then expected me to rescue you without asking questions.”
Sarah advised them not to sign anything until an independent attorney reviewed the agreement. My parents agreed, and the movers left without taking their furniture. Richard appeared furious. Brittany followed him to his car, shouting into her phone.
The following week, Sarah helped me submit the fraudulent mortgage documents to the lender’s investigation department. I also filed an identity theft report and placed security freezes on my credit reports. The lender suspended collection activity against me while reviewing the disputed application. Sarah warned that the process could take time, but she assured me we had taken the correct first steps.
Then the investigation uncovered the truth about Richard. He wasn’t simply an attorney who had made questionable decisions. Financial records showed that he’d received consulting payments from Brittany’s investment company. Investigators also found emails discussing the proposed transfer of my parents’ house before the estate-planning meeting. Richard had failed to disclose his financial relationship with Brittany when advising my parents. The documents appeared designed to help her gain control of the property while keeping my parents dependent on her promises.
But the biggest revelation came from a recorded phone call my father had saved. Dad had begun recording conversations after Brittany repeatedly threatened him. In one call, she said, “If Emily finds out about the loan, I’ll tell everyone you forged her signature. You’ll lose the house anyway. Sign it over to me, and I’ll make the problem disappear.”
I listened to that recording three times. My parents had betrayed me, but Brittany had deliberately turned their fear into leverage. Sarah forwarded the evidence to the appropriate investigators and advised my parents to obtain their own independent lawyer. They finally did.
Over the next several months, the lender’s fraud investigation confirmed that I had not authorized the refinancing. Conference records placed me in Chicago when the documents were supposedly signed, and a forensic review identified inconsistencies in the signatures. The second loan application was rejected before funds were released. The lender corrected its reporting concerning my responsibility for the fraudulent debt while the broader mortgage dispute proceeded. My parents remained responsible for resolving their own financial obligations.
Brittany’s situation unraveled quickly. Investigators discovered that her boutique had accumulated substantial debt and that she had diverted money to cover personal expenses and unsuccessful real estate investments. Richard’s involvement also became the subject of a professional disciplinary investigation. Eventually, Brittany faced criminal charges connected to the fraudulent transactions and attempted property scheme. Richard was separately investigated for his role in preparing documents and concealing his financial interest.
I expected to feel victorious. Instead, I felt exhausted. I had spent years believing that if I worked hard enough and gave enough money, my parents would finally appreciate me. But the truth was painful. They valued my support while treating my independence as an endless financial resource.
One evening, Dad called and asked whether we could meet. I agreed, provided Mom came too. We met at a quiet restaurant near my apartment. For the first time, neither of them asked for money. Dad placed a handwritten letter on the table.
“Emily,” he began, his voice breaking, “we owe you an apology. Not because Brittany deceived us, but because we let her. We signed papers we knew were wrong. We allowed you to sacrifice your future while we rewarded someone who promised us easy money.”
Mom started crying. “I kept telling myself you were doing well enough that you didn’t need anything from us. I never considered what those payments were costing you.”
I looked at them for a long moment. “I didn’t need your house. I didn’t need your investments. I needed you to treat me like your daughter instead of your emergency bank account.”
Mom covered her face. Dad nodded slowly. “You’re right.”
They told me they had met with a housing counselor, cut unnecessary expenses, and begun negotiating with their lender. Selling the house voluntarily might be necessary, but they had decided not to ask me to rescue it. They were also cooperating with investigators regarding the fraudulent signatures.
“Can you ever forgive us?” Mom whispered.
“I don’t know,” I answered. “But if we’re going to rebuild our relationship, the lying stops. And so do the financial demands.”
Both agreed.
Six months later, my parents sold their oversized house through a normal real estate transaction, paid off the valid remaining mortgage obligations, and moved into a smaller two-bedroom condominium they could afford. It wasn’t the luxurious retirement they’d imagined, but it was honest and sustainable. The disputed fraudulent loan had been addressed through the lender’s investigation and subsequent legal proceedings.
As for Brittany, she eventually pleaded guilty to charges arising from the fraudulent financial scheme. Richard faced professional sanctions and legal consequences for his involvement. Neither received the easy fortune they’d expected from manipulating my parents.
And me? I finally did something I’d postponed for seven years. I purchased my own townhouse. Three bedrooms, a small backyard, and a sunny kitchen overlooking a row of maple trees. It wasn’t extravagant, but every square foot belonged to me.
On moving day, my parents arrived carrying a housewarming gift. Mom handed me a small wooden box. Inside was my grandmother’s gold necklace, the one I’d admired since childhood.
“This was always supposed to be yours,” she said softly. “Your grandmother wanted you to have it.”
I looked at the necklace, then at my mother. “Thank you.”
Dad helped Michael carry boxes into the garage. Mom arranged flowers on the kitchen counter. For the first time in years, we spent an afternoon together without discussing bills, transfers, or debts.
Our relationship wasn’t magically repaired. Trust takes longer to rebuild than a bank account. But my parents began respecting boundaries, and I stopped confusing love with financial sacrifice.
That evening, after everyone left, I sat on my new porch with a cup of tea. My phone buzzed with a message from Mom.
“Thank you for letting us be part of your new beginning. We’re proud of you.”
I smiled and replied, “I love you, Mom.”
Then I opened my banking app. For the first time in seven years, every automatic payment listed belonged to my own life.
I thought about that afternoon at the attorney’s office, when my parents announced Brittany would inherit everything. I’d felt invisible, unwanted, and betrayed. But their decision had forced me to see something I’d ignored for years.
I had been giving away my future to people who believed my generosity was an obligation.
When Mom texted that the mortgage was due, I’d answered, “Not my problem.”
At the time, those words came from anger.
Now I understood their real meaning.
I could love my family without paying for their mistakes. I could forgive without surrendering my boundaries. And I could build a beautiful life without waiting for anyone to leave me an inheritance.
Because the greatest thing I received from that terrible meeting wasn’t money, property, or revenge.
It was the freedom to finally choose myself.