“I understand. I’ll pack my things.”
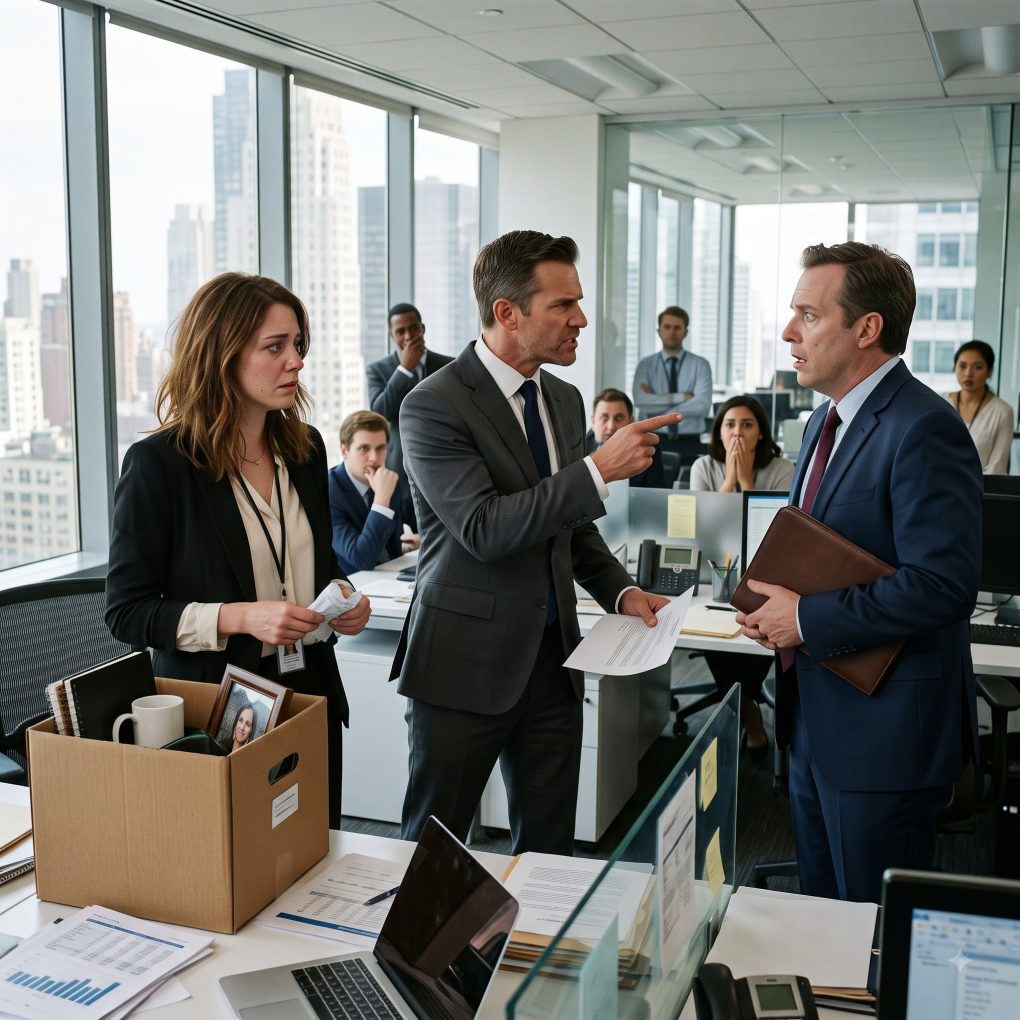
Madison Reed said it quietly, holding the termination letter her supervisor had just dropped onto her desk. Around her, keyboards stopped clicking. Conversations died halfway through sentences. Everyone in the finance department of Sterling Global Technologies knew Madison had worked three consecutive nights to prevent the company from losing its largest client. Now, without warning, she had been fired.Her supervisor, Richard Coleman, straightened his expensive navy tie.
“Your access has been revoked. Security will escort you out when you’re ready.”
Madison, thirty-two, looked at the letter again. It accused her of violating financial reporting procedures and accessing restricted company accounts without authorization.
“That’s not true,” she said. “I reported the irregularities to Compliance last week.”
Richard’s expression hardened. “And now you’re making excuses. Sign the acknowledgment and leave.”
Before Madison could answer, the executive elevator opened.
CEO Alexander Bennett stepped into the department, followed by his chief of staff. At forty-one, Alexander had a reputation for being controlled, demanding, and almost impossible to surprise. But the moment he saw Madison standing beside a box of personal belongings, something in his expression changed.
“Why is she packing?”
Richard hurried forward. “A personnel matter, sir. Madison’s employment has been terminated for serious policy violations. I was just handling it.”
Alexander held out his hand. “Let me see the letter.”
Richard hesitated for half a second before passing it over.
Alexander read the first page, then the second. His jaw tightened. He looked at Richard, then at the silent employees watching from their desks.
“Who gave you permission to fire the woman who saved this company?”
Nobody moved.Richard gave a strained laugh. “I’m afraid you’ve been misinformed. Madison made unauthorized changes to a financial report. Her actions exposed us to considerable risk.”
“Really?” Alexander asked. “Because the report she corrected prevented us from submitting a false revenue statement to our investors. If she hadn’t caught the discrepancy, we could have faced a federal investigation.”
Madison stared at him. She had expected him to question her work, not defend it.
Alexander folded the letter. “Richard, your authority to terminate employees is limited by company policy. Did you obtain approval from Human Resources or Legal?”
Richard’s face reddened. “I believed immediate action was necessary.”
“That wasn’t my question.”
Silence settled over the department.
Then Alexander turned to Madison. His voice softened, but his eyes remained serious.
“Before you leave, I need you to answer something. Did you discover any transactions in our confidential accounts that didn’t belong there?”
Madison’s fingers tightened around the letter.
She glanced at the security cameras, then at Richard, who had suddenly stopped looking angry.
“I found payments that were being concealed from the board,” she whispered. “I was preparing the evidence when my access disappeared.”
Alexander went still.
“How much?”
“Nearly eighteen million dollars.”
A sharp breath escaped someone behind them.
Alexander leaned closer and lowered his voice.
“Madison, the transactions I found this morning go back three years. And someone has been using your employee credentials to approve them.”
Madison felt the room tilt. She had never authorized those payments.
Then Alexander said the words that frightened her more than the termination letter ever could.
“Someone wants you blamed for every dollar.”For several seconds, Madison couldn’t speak.
She had spent six years at Sterling Global Technologies building a reputation for being meticulous. She checked every number twice, documented every exception, and refused to approve anything she couldn’t explain. The idea that her credentials had been used to authorize eighteen million dollars in suspicious payments made her feel as though someone had reached into her life and rewritten it.
“Who has access to my account?” she asked.
Alexander looked toward Richard. “That’s what we’re going to establish.”
Richard immediately stepped forward. “This is getting out of hand. Madison had access to sensitive financial systems. If her credentials were compromised, that’s a security issue. It doesn’t change the fact that her performance has been unacceptable.”
Madison turned toward him. “You never gave me a performance warning. Yesterday, you told me the audit corrections were excellent.”
“I said the corrections were adequate.”
“You said, and I quote, ‘You may have just saved us from a disastrous filing.’”
Richard’s face tightened. He glanced at the other employees, several of whom had heard the exchange the previous day.
Alexander noticed.
“Richard, leave your company laptop and access badge with Security. You are not being asked to leave permanently at this moment, but you will not access financial systems until our independent review is complete.”“You can’t suspend me because of an accusation from a disgruntled employee.”
“I’m suspending access because eighteen million dollars may have been diverted through accounts under our control, and you just attempted to remove a key witness before answering a single question.”
Richard’s mouth opened, but no response came.
Two security officers arrived. They escorted Richard to a conference room rather than out of the building. Alexander instructed Human Resources to preserve Madison’s employment records, reverse the immediate termination pending investigation, and refrain from contacting her about the disputed transactions without a representative from Legal present.
Madison remained beside her desk, still holding the termination letter.
“Am I supposed to come back to work as if none of this happened?” she asked.
“No,” Alexander replied. “You’re supposed to protect yourself and help us establish the truth. You won’t be asked to investigate your own case, and you won’t be expected to access restricted systems.”
He introduced her to Elena Brooks, Sterling’s outside counsel, who had arrived for an emergency meeting. Elena was in her late forties, sharp-eyed and direct. She explained that the company would preserve all electronic records and bring in an independent forensic accounting firm. Madison would be interviewed as a witness, not instructed to collect evidence herself.
Before entering the conference room, Madison asked Alexander for a private conversation.
“I need you to understand something,” she said. “I reported the first irregularity through the official Compliance channel last Thursday. I received an acknowledgment, but two hours later my account was flagged for unusual activity. By Friday morning, someone had changed my access permissions.”
“Did you tell Richard?”
“Yes. He said I was overreacting and told me to focus on the quarterly report.”
Alexander’s expression darkened. “Do you have a copy of your report?”
“On my personal drive, yes. It contains no customer information, just the timeline and reference numbers I was permitted to retain under our reporting policy.”
Elena cautioned her not to forward any additional company records from personal devices. Instead, she arranged for the report to be submitted through the company’s legal team, which would preserve it properly.
Inside the conference room, the independent investigators began with the payment trail. The eighteen million dollars had been transferred in a series of transactions to three consulting firms. Each firm had a legitimate-looking website, registered business address, and invoices describing routine technology services. Yet the invoices were vague, the listed project managers could not be verified, and the services appeared nowhere in Sterling’s project records.
The first transaction had occurred three years earlier.
The most recent had been processed only nine days ago.
Madison reviewed the transaction reference numbers from memory and recognized a pattern. The payments had been split into amounts that fell just below an internal threshold requiring additional executive review. Some were approved outside normal business hours, and several carried authorization codes associated with her account.“But I didn’t approve them,” she insisted. “I was on leave for two of those dates. For another, I was presenting the quarterly reconciliation in a room full of people.”
The investigators recorded the dates and requested the relevant attendance logs, access records, and system audit history.
By late afternoon, they had uncovered something troubling: the authorizations did not come from Madison’s usual workstation. They came from a remote administrative session created using an emergency access procedure.
Only a small group of senior employees could request that procedure.
Alexander asked Elena to produce the approval history without speculating about who was responsible. The records showed that the emergency sessions had been authorized under a department-level approval code. The identity behind that code had been masked by an automated system migration, but the original logs were believed to exist in a backup archive.
Then an investigator found a deleted calendar entry on Richard’s company account. It showed a private meeting with the chief financial officer, Paul Mercer, on the afternoon before Madison’s access had first been restricted.
Richard had described the meeting as a routine budget review. Paul’s assistant said she had never scheduled it.
Paul Mercer was fifty-four, a respected executive who had helped guide Sterling through two acquisitions. He had not been named in Madison’s original report, and no one had yet established that he had done anything wrong. Still, his name appeared in the approval chain for two of the suspicious payments.
When Alexander requested an interview, Paul responded through his assistant that he was traveling and would be available the following morning.
That evening, Madison returned to her apartment with a company representative and collected the personal belongings she had left behind earlier. She was no longer officially dismissed, but the damage to her reputation had already begun. An anonymous message had appeared on her phone from an unlisted number:
You should have taken the severance. Stop asking about accounts you don’t understand.
She showed it to Elena, who instructed her to preserve the message and avoid responding.
“Could it be Richard?” Madison asked.
“It could be someone who wants you to believe that,” Elena replied. “We don’t guess. We document.”
At 9:17 p.m., Alexander called Madison. He sounded exhausted.
“The backup archive has been located,” he said. “There’s a record of who requested the emergency access sessions. But there’s also an account in the ledger that wasn’t included in your original report.”
“What account?”
“A restricted holding account created under a code reserved for executive-level transactions. It received a portion of the diverted money before the payments went to those consulting firms.”
Madison sat upright.
“Whose name is attached to it?”
Alexander paused.
“The account is linked to an executive trust associated with Sterling’s original founders. And the beneficiary information was changed six weeks ago.”
“Changed to whom?”
“We don’t know yet. The bank requires additional verification before releasing the complete records.”
Madison stared at the dark window of her apartment. Someone had stolen millions, used her credentials to conceal the trail, and tried to fire her when she got too close. Now the money appeared to lead toward the very people who had built the company.
“Alexander,” she said, “what if the person behind this isn’t trying to protect the company?”
“Then we need to find out what they’re protecting.”
The next morning, Paul Mercer arrived at headquarters with his attorney. He denied authorizing any improper transfers and claimed the emergency access procedure had been abused by someone with administrative privileges. He agreed to cooperate, but before the interview ended, he asked Elena a strange question.
“Has anyone checked whether the founder’s family still has access to the trust?”
Elena looked up. “Why would that matter?”
Paul’s attorney interrupted, saying his client would answer no further questions without reviewing the archived records.
As Paul left the room, Madison noticed that he was carrying a thin envelope marked with the name of Sterling’s late founder, Thomas Bennett.
Alexander saw it too.
Neither of them knew what the envelope contained. But the independent investigators had just confirmed that the beneficiary change had been submitted from an account registered to the founder’s estate office.
And the person who had signed the request was someone who had been dead for almost two years.At 7:30 the next morning, Alexander convened an emergency meeting with Sterling’s board chair, outside counsel, and the independent forensic accounting team. Madison attended as a witness, seated beside Elena Brooks. She had barely slept. The anonymous message remained on her phone, and every time it lit up, she wondered whether the sender knew where she lived.
The investigators began with the founder’s trust.
Thomas Bennett had established the trust to hold a minority stake in Sterling Global Technologies and support several charitable programs. After his death, the trust’s administration had passed to an independent fiduciary. No single executive was supposed to control its funds, and any change in beneficiary required two independent approvals.
The disputed amendment had supposedly been signed by Thomas himself eighteen months after his death.
It was impossible.
The signature had been copied from an older document, and the electronic submission had been made using credentials assigned to the founder’s former estate administrator. That administrator had retired before the amendment was filed. Investigators contacted him and learned that he had reported a stolen laptop months earlier.
The document had not been signed by a dead man. Someone had used his identity to make it appear that the transfer had been properly authorized.
The altered beneficiary record pointed to a private investment company registered in Delaware. Its ownership had been concealed behind a corporate services firm, but the investigators traced the company’s payments and discovered that it had funded a luxury property partnership and several personal expenses.
The property partnership was connected to Richard Coleman.
Richard had not merely attempted to fire Madison. He had been benefiting from the money diverted through the consulting firms.
But the evidence revealed a second layer.
The emergency access requests that had enabled the transfers were approved using Paul Mercer’s executive authorization code. Paul admitted that he had approved several emergency sessions, believing they were necessary to resolve a reporting-system problem. He claimed Richard had told him the transactions were internal reallocations authorized by the board.
The investigators could not accept his explanation without corroboration. They examined his messages, approval history, and communications with Richard. Some messages supported the claim that Paul had been misled. Others showed that he had ignored warnings from the treasury team about missing documentation.
Paul was not cleared simply because he said he had been deceived.The board placed him on administrative leave while the investigation continued, and he agreed to provide records through his attorney. Whether his conduct amounted to negligence or knowing participation would be determined by the evidence and, if necessary, the authorities.
Then came the discovery that changed Madison’s understanding of her dismissal.
The forensic team recovered a series of internal messages exchanged between Richard and an executive assistant three days before she was fired. Richard had written that Madison’s audit report could expose the unauthorized transfers unless the reporting discrepancy was blamed on her. In a later message, he instructed the assistant to prepare a termination letter citing policy violations and to remove Madison’s access before she could submit her supporting documentation.
One sentence stood out:
Once Reed is out, the audit trail becomes a personnel dispute instead of a financial investigation.
Madison read the message twice. Her hands trembled, but she forced herself to keep reading.
Richard had known that her report was accurate. He had fired her not because she had mishandled the accounts, but because she had discovered that someone was stealing from the company. He intended to turn a financial crime into a dispute about an employee’s credibility.
Alexander sat quietly while Elena explained what the recovered messages established. The CEO looked angrier than Madison had ever seen him, but he did not interrupt or turn the meeting into a public confrontation.
Instead, he asked the investigators one question.
“Can we prove who controlled the Delaware company?”
The team presented the ownership records, property payments, and communications linking Richard to the company. They also identified an intermediary who had received payments from the consulting firms and transferred portions of the money to accounts connected to Richard’s property partnership.
The trail was substantial, but the investigators cautioned that the evidence needed to be delivered intact to law enforcement and reviewed by the relevant financial institutions. The company would not announce criminal conclusions before the investigation had established them.
By noon, Sterling’s board had authorized a formal referral to law enforcement and ordered a comprehensive review of its financial controls. Richard was removed from his position pending the investigation. His company devices and relevant records were preserved under legal supervision.
When Richard was informed of the decision, he insisted that Madison had manipulated the records to protect herself.
But the timeline contradicted him. The suspicious payments predated Madison’s discovery by years, and the recovered messages showed that Richard had planned her dismissal before she was even interviewed about the alleged violations.
His accusation no longer explained the evidence. It only raised more questions about his conduct.
For Madison, vindication did not arrive as a dramatic celebration. It came through a formal letter from Human Resources confirming that her termination had been rescinded, followed by an apology from the board chair acknowledging that the company had failed to protect an employee who reported serious concerns.
Alexander met her privately later that afternoon.
“I should have known something was wrong when I saw that letter,” he said. “I knew your work had protected us. I should have asked why someone was trying to remove you before accepting any explanation.”
“You did ask,” Madison replied. “You stopped it before they could escort me out.”
“After it had already happened. That isn’t good enough.”
She studied him for a moment. “What happens to my job now?”
“That’s your decision. You can return to your role with a different reporting line, or you can take time away while the investigation continues. No one will pressure you to stay.”
Madison looked through the glass wall at the finance department. The same employees who had watched her stand beside a cardboard box were now carefully avoiding her eyes. She understood why. They had been frightened, and most had known only what Richard had told them.
“I want to return,” she said. “But I want the reporting process changed. Employees shouldn’t have to choose between their jobs and reporting something that could hurt the company.”
Alexander agreed. Sterling appointed an independent compliance officer, introduced a protected reporting channel, and required dual approval for emergency financial access. The company also began reviewing other transactions that had previously been accepted without sufficient documentation.
Several weeks later, Madison received a call from the investigator handling the case. The authorities had obtained additional banking records connecting the Delaware company to payments made for Richard’s personal benefit. Richard had retained legal counsel and disputed the allegations, but the investigation was moving forward. The evidence Madison had preserved had helped investigators establish a timeline they might otherwise have missed.Paul’s role remained under review. He had provided records that supported parts of his account, but investigators continued examining whether he had knowingly approved transactions without adequate authorization. Sterling did not quietly restore him to his former position.
Madison was eventually offered a promotion to director of financial integrity, reporting directly to the board’s audit committee rather than through the executives whose transactions she reviewed. She accepted, not because she wanted revenge, but because she wanted the authority to prevent another employee from facing what she had endured.
On her first day in the new role, Alexander stopped by her office.
“I owe you more than an apology,” he said. “You saved this company twice. First by finding the false revenue report, and then by refusing to let the suspicious payments disappear into a personnel file.”
Madison gave a small, tired smile.
“I was just doing my job.”
“That’s precisely why this should never have happened to you.”
After he left, Madison placed the original termination letter in a folder with the independent investigation’s findings. She did not keep it as a trophy. She kept it as a reminder of how easily an organization could punish the person who told the truth when protecting its reputation seemed more convenient.
The company had nearly lost eighteen million dollars, but the deeper damage had been the culture that allowed warning signs to be ignored and authority to be abused.
Madison had walked into work expecting to pack her belongings and leave quietly. Instead, she had helped expose a scheme that reached into Sterling’s financial systems, its executive offices, and a trust created by its founder.
The most dangerous part had not been the money.
It had been how easily someone had tried to make the truth look like misconduct.
And this time, Madison had the records to prove otherwise.