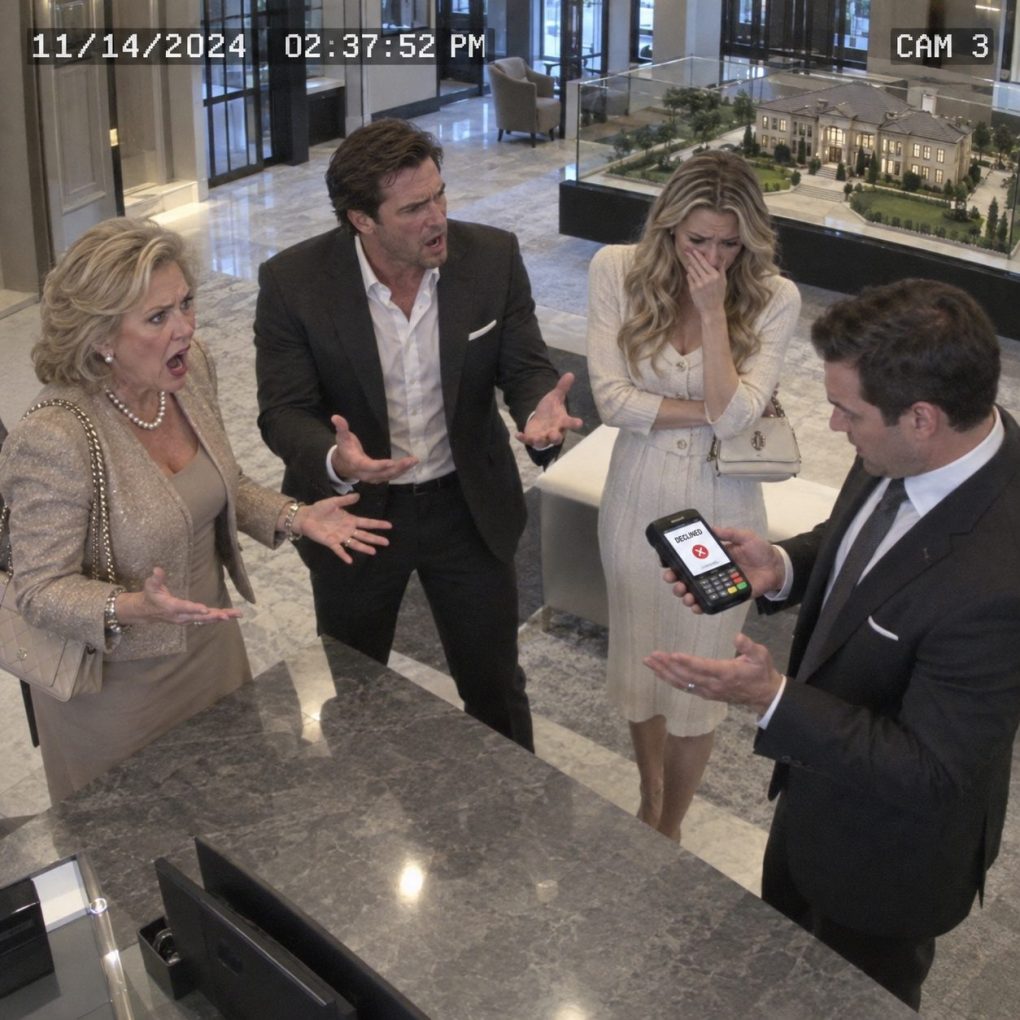
My mother-in-law announced that her son was buying a $3.8 million estate with his new wife, even though our divorce had been finalized only six weeks earlier. She invited me to the property viewing just to humiliate me. But when the real estate agent requested a $25,000 reservation deposit, my ex-husband’s card was declined. Then the agent looked directly at me, and the secret behind their luxurious lifestyle began unraveling.
My name is Claire Bennett, and I was thirty-seven when my former husband, Ryan, discovered that pretending to be wealthy was not the same as owning wealth. We had been married for eleven years in Charlotte, North Carolina. Throughout our marriage, his mother, Margaret, proudly described him as a self-made millionaire.
The truth was considerably different. I owned a profitable logistics consulting company established before our marriage. Ryan worked in business development, earned a respectable salary, and enjoyed presenting my professional success as evidence of his own financial brilliance.
When I discovered his affair with a woman named Vanessa, I filed for divorce. Our attorneys negotiated a property settlement addressing our marital assets, while my separately owned business interests were evaluated and treated according to the applicable agreements and financial records.
Ryan received his agreed share of the marital property. He also retained responsibility for several personal debts he had accumulated. Instead of adjusting his lifestyle, he leased an expensive sports car and began telling relatives that he was preparing to purchase a luxury estate.
Margaret invited me to the viewing with a message suggesting that I should witness what I had lost. I attended because my attorney had asked me to collect documents Ryan had mistakenly left with the agent concerning an earlier jointly owned property.
Inside the estate, Margaret loudly praised Vanessa as the woman who had finally inspired Ryan to live according to his financial status. She mocked my modest clothing and suggested that my former husband had been wasting his potential while married to me.
Then the agent requested a reservation deposit under the property’s written purchase process. Ryan confidently presented his premium credit card. The payment failed. He tried another card, but that transaction was declined as well.
Vanessa demanded an explanation. Ryan blamed a temporary banking problem, while Margaret accused the agent of embarrassing an important buyer. I remained silent until the agent asked whether I was the Claire Bennett listed on an outdated proof-of-funds document Ryan had submitted.
I confirmed my identity but explained that the document belonged to my business and had never authorized Ryan to use its assets for a personal purchase. The agent immediately suspended the transaction pending verification. Margaret turned toward her son, demanding answers. For the first time, Ryan had nothing convincing to say.
The agent escorted us into a private office and explained that the proof-of-funds document had been submitted several days earlier. It displayed the name of my consulting company and a bank balance exceeding $4 million. Ryan had apparently presented it as evidence of his personal purchasing power.
I examined the document and recognized an old account statement from my business. It had been included in confidential financial disclosures during our divorce. Although Ryan had legitimately received certain documents through the proceedings, he had no authority to present company funds as his own.
The agent apologized for the confusion and confirmed that the estate reservation would not proceed without legitimate financial verification. Margaret accused me of deliberately sabotaging Ryan’s purchase, but Vanessa looked increasingly alarmed.
Vanessa asked Ryan whether he actually possessed enough money to purchase the property. He insisted that several investments were temporarily inaccessible. When she pressed for details, he became angry and accused her of embarrassing him in front of strangers.
I left the office and immediately contacted my attorney, Rebecca Collins. She advised me to preserve the agent’s communications and notify the appropriate parties about the unauthorized use of my company’s financial information.
The following morning, Rebecca contacted Ryan’s attorney. She requested an explanation for the document and warned that any further misrepresentation involving my business would require formal action. Ryan responded through counsel, claiming the statement had been submitted accidentally.
Meanwhile, Vanessa contacted me privately. She explained that Ryan had encouraged her to resign from her job because he supposedly had enough investments to support them both. He had also promised to purchase the estate without requiring her financial contribution.
I told Vanessa that I could not advise her about her relationship, but she should independently verify any financial claims before making major decisions. She thanked me and admitted that Ryan had become increasingly evasive whenever she asked about money.
Several days later, Margaret appeared at my office demanding that I provide Ryan with a temporary loan. She claimed that he needed only $200,000 to complete another property transaction and protect his reputation. I refused and asked her to leave.
Then Rebecca received information from Ryan’s attorney confirming that he had substantial outstanding credit card balances and several personal loans. His extravagant lifestyle had been financed largely through borrowing, not investment income. The revelation became even more serious when Vanessa discovered that Ryan had listed her as a proposed guarantor on a loan application without obtaining her agreement.
Vanessa contacted the lender immediately after discovering the application. She confirmed that she had not authorized Ryan to submit her information as a guarantor. The lender suspended its review and began investigating the discrepancy.
Ryan insisted that he had intended to explain everything before the loan was finalized. Vanessa did not accept that explanation. She moved out of their shared apartment and retained an attorney to review the financial documents associated with their relationship.
Margaret continued defending her son. She claimed that wealthy people frequently used borrowed money and that everyone was overreacting to ordinary financial arrangements. But the evidence showed that Ryan had repeatedly exaggerated his assets while concealing significant personal debt.
Rebecca helped me obtain written confirmation that my company’s financial records would no longer be used in Ryan’s transactions. We also reviewed the safeguards protecting confidential business information and ensured that financial institutions had accurate authorization instructions.
Ryan eventually acknowledged through his attorney that he had misrepresented his access to my company’s funds. He agreed to stop using the documents and to reimburse certain expenses associated with correcting the misleading submissions. The real estate transaction was permanently abandoned.
The lender completed its review of Vanessa’s complaint and removed her from the proposed financing arrangement. She later told me that discovering the truth had prevented her from entering a marriage built on financial deception.
Several months later, Ryan sold his leased vehicle early, negotiated payment arrangements with creditors, and moved into a smaller apartment. The lifestyle he had displayed so proudly during our marriage proved impossible to maintain without access to substantial outside resources.
Margaret eventually requested a meeting with me. She arrived looking unusually subdued and admitted that she had believed Ryan’s claims because she wanted her son to appear successful. She apologized for humiliating me at the estate viewing, although she still struggled to acknowledge the full extent of his dishonesty.
I accepted her apology without offering financial assistance. I explained that Ryan was responsible for rebuilding his own finances and reputation. My success had never entitled him to misrepresent my company’s assets or pressure others into supporting his lifestyle.
One year after our divorce, I purchased a modest lakeside cottage as a personal retreat. It was nowhere near as extravagant as the estate Ryan had pretended to afford, but every payment came from money I had earned and properly managed. As I sat on the porch watching the water, I remembered Margaret proudly announcing that her son was upgrading to a mansion with his new wife. She had believed his expensive clothes, luxury cars, and confident promises proved that he was a millionaire. One declined card had exposed the first crack in that illusion, and the financial documents revealed everything underneath. Ryan had spent years confusing access to wealth with ownership of wealth. I had spent those same years building something real. In the end, I didn’t need to embarrass him or compete with Vanessa. The truth emerged because his promises were larger than his resources. My greatest satisfaction was knowing that my future no longer depended on someone who needed other people to believe he was richer than he really was.