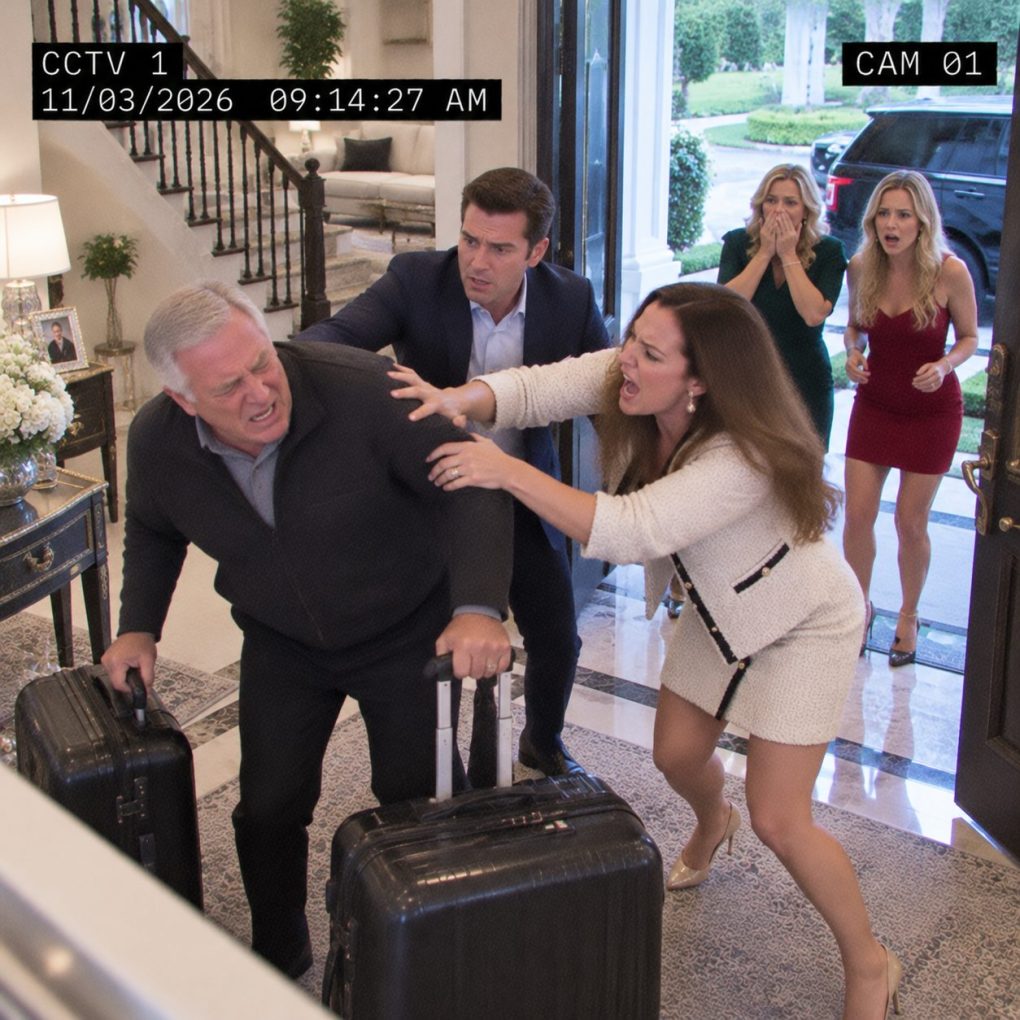
Logan did not look at me when his wife told me to leave.
That was the part I remembered most.
Not Vanessa standing in the kitchen with her arms crossed. Not the two suitcases she had already dragged down from the guest room. Not even the sentence she delivered as though she owned every inch of the house: “This arrangement is over, Richard. Pack whatever is left and find somewhere else to stay.” I looked past her toward my son. Logan sat at the breakfast table staring at his coffee. For twelve years after his mother died, I had been the person he called when something went wrong. I helped with the down payment on that house, covered part of the mortgage when his contracting company nearly failed, guaranteed a business credit line, and kept $75,000 in a separate emergency account for situations involving the grandchildren. I never reminded him of any of it. I only asked one question. “Logan, is this what you want?”
He still would not look at me.
“Dad, maybe some space is best.”
Three words would have changed everything.
She can’t throw you out.
He never said them.
The argument had started because Vanessa wanted $40,000 from the emergency reserve to help her sister open a med spa. I said no. The account existed for genuine family emergencies—medical bills, temporary unemployment, something threatening the children’s stability. A speculative business belonging to Vanessa’s sister was not an emergency. Vanessa called me controlling. I reminded her the money was mine. She told me if I insisted on “holding money over the family,” I could stop living under their roof.
The irony was that I had been there temporarily. A plumbing failure had damaged my townhouse, and Logan invited me to stay during repairs. I paid them $1,200 a month toward household expenses even though he protested at first. Four months later, Vanessa had apparently rewritten the arrangement in her head: I was the dependent relative they were supporting.
So I picked up the suitcases.
I did not argue.
I did not tell Logan how many times I had protected him from consequences he was old enough to handle himself.
I drove to a hotel, called my contractor, and learned my townhouse would be ready within a week.
Then I called my financial adviser and attorney.
I did not empty Logan’s accounts or cancel obligations already legally mine. I simply reviewed every form of financial support I was still voluntarily providing.
The $3,400 monthly mortgage contribution ended after the current payment.
The guarantee supporting the next renewal of Logan’s $420,000 business line would not be renewed.
The family emergency reserve remained exactly where it had always legally been—in an account solely in my name. I removed the debit card Logan carried for genuine emergencies and changed the authorization instructions.
I told nobody.
Twenty-one days later, Logan called me seventeen times before lunch.
I answered the eighteenth.
His voice was shaking.
“Dad, what did you do?”
“About what?”
“The bank says they’re reducing my business line. The mortgage transfer didn’t arrive. And Vanessa’s card for the emergency account stopped working.”
I sat in my repaired townhouse, drinking coffee.
“I stopped financing arrangements I was apparently too controlling to be part of.”
He was silent.
Then he said, “Dad, you can’t do this all at once.”
I almost replied.
But another call appeared.
My attorney.
I switched over.
“Richard,” Rebecca said, “I just received the lender file for Logan’s company.”
Something in her voice made me sit straighter.
“What’s wrong?”
“Your guarantee wasn’t the only thing he gave them.”
She paused.
“He listed your $75,000 emergency reserve as committed business liquidity.”
I closed my eyes.
“That account was never for his company.”
“I know.”
“There’s more?”
“Yes.”
Rebecca exhaled.
“Logan also represented that your mortgage support would continue for five years.”
I stared at the wall.
I had never promised five years.
And attached to the application was a letter carrying my signature.
Rebecca’s first instruction was to preserve everything and avoid accusing Logan of forgery before the lender produced its complete file. A false-looking signature could come from sloppy paperwork, an old authorization reused improperly, or deliberate misconduct. We needed facts, not anger.
The lender sent the documents that afternoon. Logan’s company had applied for renewal and expansion of a commercial credit line six months earlier. The package described my monthly mortgage payments as continuing family support and my emergency reserve as available liquidity if the business suffered a temporary shortfall.
Neither description matched reality. I had helped voluntarily because Logan’s company lost two major contracts during a difficult year. I had never pledged my savings account to his company, and no agreement required me to keep subsidizing his mortgage.
The most troubling document was a one-page “Support and Liquidity Confirmation.” It stated that I intended to continue $3,400 monthly household assistance for five years and maintain at least $75,000 accessible for Logan’s family and business emergencies. My electronic signature appeared beneath the statement.
I had never seen it.
Logan came to my townhouse that evening without Vanessa. He looked exhausted. When I placed the letter in front of him, he stared at it for several seconds before saying, “I thought you’d agreed to keep helping.” I asked a different question. “Did I sign this?” He did not answer.
Eventually, he admitted Vanessa had prepared the document from information they had given the lender. She used my signature image from an older mortgage-support letter I had legitimately signed during their refinancing two years earlier. Logan claimed he believed she would ask me before submitting it.
“But you signed the application,” I said. His face changed. He knew exactly why that mattered. His own certification stated the supporting information was accurate to the best of his knowledge. Whatever Vanessa had done, he had placed his name beneath the package too.
The lender did not call the entire loan immediately due or seize anything dramatically. Instead, once I formally denied the commitment, it reassessed the company based on Logan’s actual financial position. The proposed expansion disappeared, and the existing line was reduced at renewal because my backing would no longer be available.
That exposed how fragile Logan’s business had become. He had kept payroll current, equipment leases paid, and suppliers calm partly because lenders believed my assets stood behind him. Rather than shrinking operations when revenue declined, he had continued expanding because he expected my support to remain permanent.
Vanessa blamed me. She left a voicemail saying I was punishing grandchildren who had done nothing wrong. I agreed the children were innocent. That was precisely why I had preserved the emergency reserve instead of handing it to her sister’s med spa. Their genuine needs would still matter to me; adult lifestyle choices would not automatically qualify.
Then Rebecca found an email Vanessa had sent Logan while I was still living with them: Once his townhouse is fixed, don’t let him move all the money back under his control. We need him comfortable here until the credit renewal closes.
Logan replied:
He won’t leave. Dad needs us more than he admits.
I read that line several times.
The man who had watched me walk out with two suitcases had not remained silent because he believed I needed space.
He had remained silent because he thought I would come back before his financial arrangements noticed I was gone.
Logan’s company did not collapse in twenty-one days. The reduced credit line forced him to confront problems he had postponed, but there were still employees, contracts, equipment, and customers worth saving. He hired a restructuring adviser and finally opened the books to someone who was not family.
The adviser recommended cuts Logan had avoided for two years. He sold three underused vehicles, closed a small satellite office, stopped bidding on projects that required expensive upfront financing, and renegotiated supplier terms. The company became smaller, but its cash flow improved.
The mortgage was also manageable without me, though not comfortably. Logan and Vanessa refinanced several personal debts, canceled a planned kitchen renovation, and sold the luxury SUV Vanessa had leased after assuming the business would keep growing. No one became homeless.
The lender documented my dispute regarding the support letter and removed any suggestion that my emergency reserve was committed collateral or liquidity. I did not demand criminal charges. I wanted my financial identity corrected and my signature treated as mine.
Vanessa and Logan’s marriage nearly ended over the document. He blamed her for submitting it; she blamed him for allowing their finances to depend on his father. Eventually, they entered counseling and, to my surprise, stayed together. I had no interest in becoming the third person inside that marriage again.
My relationship with Logan remained frozen for almost six months. He texted on holidays. I answered politely. I saw my grandchildren through arrangements that did not require me to enter his house, and I never told them that their parents’ finances were the reason adults were angry.
The $75,000 emergency reserve stayed intact. When my granddaughter later needed surgery not fully covered by insurance, I paid the hospital directly. Vanessa thanked me. I answered, “That is what the account was created for.” Neither of us mentioned her sister’s med spa.
Logan apologized the following spring. He came to my townhouse carrying the two suitcases I had forgotten in their garage. We sat on the balcony without Vanessa, attorneys, lenders, or spreadsheets between us. He said, “I thought because you always helped, you always would.”
“That wasn’t the worst part.”
He looked at me.
“You thought helping meant I had nowhere else to go.”
His eyes filled. He nodded.
That was what hurt most. Not the mortgage payment. Not the guarantee. Not even the unauthorized letter. My son had watched his wife throw me out because he believed dependence ran in only one direction.
For years, I had protected Logan from feeling the full weight of his own decisions. Every time the business struggled, I guaranteed something. Every time household expenses rose, I covered a gap. Every emergency became easier because Dad would fix it.
I thought I was being a good father.
Sometimes I was.
Sometimes I was preventing my son from learning where my responsibility ended and his began.
Twenty-one days after I left, three things disappeared from Logan’s life almost simultaneously: mortgage support, business backing, and automatic access to emergency money.
He called it abandonment at first.
Later, he called it the first month he truly understood his finances.
I never moved back.
I never restored the old arrangement.
I still love my son. I still help my grandchildren. I still answer when Logan calls because he wants advice rather than rescue.
But now, when I give something, everybody knows exactly what it is.
A gift.
Not an entitlement.
Not a permanent line item.
And certainly not proof that the person giving it needs permission to remain in the family.
The night Vanessa threw me out, Logan chose silence because he thought I would return.
He was right about one thing.
I did return to being his father.
I just never returned to being his financial safety net.