When my credit app flashed $218K in mystery debt on my home, I rushed to the bank to stop it. Instead, I walked right into a calculated trap set by my own wife’s family to frame me for a federal crime.
At 7:15 AM, my credit app flashed a notification that stopped my heart: $218,000 in new mortgage debt tied to my home. Not a pending charge. Fully executed. I didn’t wait to check my coffee or put on a proper jacket. I grabbed my folder of property deeds, jumped into my truck, and drove straight to the regional mortgage office downtown, gripping the steering wheel until my knuckles turned white.
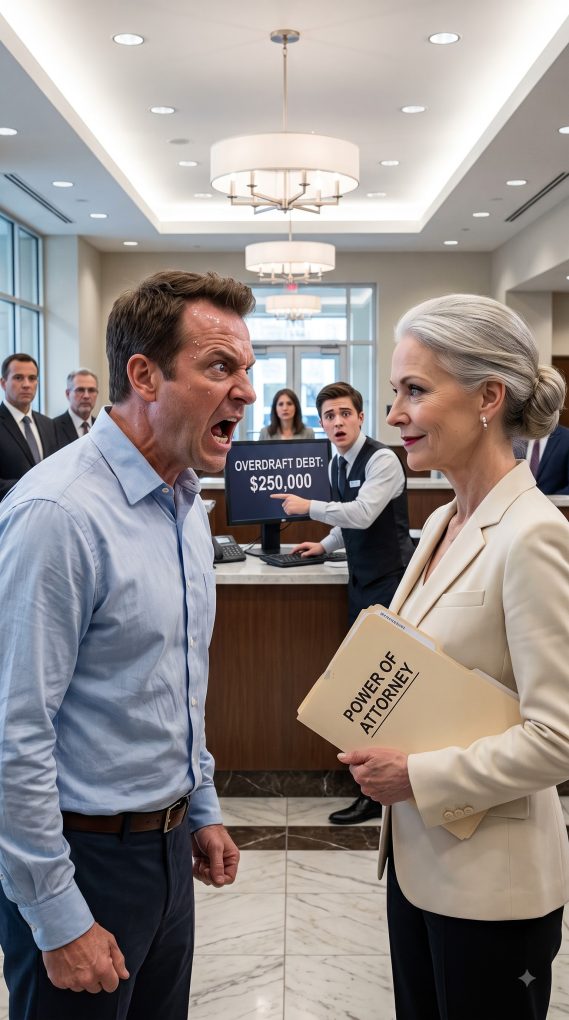
When I burst through the glass doors, out of breath and shaking, I expected to fight the front desk for an emergency appointment. Instead, I saw my mother-in-law, Eleanor, sitting primly in a leather armchair by the manager’s desk. She wasn’t pacing. She wasn’t panicking. She was holding a laminated folder containing a durable power of attorney document with my husband Mark’s signature stamped across it.
The branch manager looked up, offering a tight, sympathetic smile. “Ah, Mr. Davis. Good thing you’re here. Your mother-in-law was already looking out for your interests. Since Mark was tied up at the office, he asked her to step in and finalize the equity line authorization for the investment property.”
I stared at Eleanor. She didn’t flinch. She simply met my eyes with that cold, unyielding gaze she had perfected over thirty years of upper-middle-class condescension.
“He was busy,” Eleanor said smoothly, her voice dripping with practiced calm, “so he asked me to handle this while you were still asleep.”
I felt a cold sweat break out across my neck, but I forced a rigid smile, playing along to keep the room from exploding. “Of course, Mom. Always proactive.”
The fraud investigator, who had been quietly reviewing our digital file at the corner workstation, suddenly stood up and walked over. He didn’t look at me; his eyes were glued to the glowing monitor. He opened the original loan application, scrolled down once to verify the primary signatures… and abruptly stopped. His face drained of all color. He tapped the screen twice, frowned deeply, and looked straight at me.
“Wait…” the investigator whispered, his voice trembling in the sudden, suffocating silence of the office. “This house is…”
What you are about to discover next will shatter everything you thought you knew about a twenty-year marriage, a hidden double life, and a signature that wasn’t even meant for a bank. The truth is darker than a simple financial betrayal, and the person standing beside you might just be the architect of your entire ruin. I finished the story in the comments👇
part 2:
The investigator’s finger hovered over the screen, shaking slightly as he pointed at a small, grayed-out metadata tag in the corner of the PDF. “Mr. Davis, look closely. This isn’t just a standard equity line. This is a complete title transfer and refinancing package executed under an emergency hardship clause. And the designated recipient account… it doesn’t match your joint mortgage or any personal asset you own.”
My heart hammered against my ribs like a trapped bird. “What do you mean it doesn’t match? Whose account is the funds routing to?”
Before the investigator could answer, Eleanor stood up, her composure cracking just enough to reveal a flash of raw panic. “There is no need to involve the authorities or create a scene over a simple administrative routing error,” she snapped, stepping directly between me and the computer monitor. Her voice had lost its honeyed warmth, replaced by sharp, commanding steel. “My son authorized this transaction to protect our family assets from liabilities you don’t even know exist. Sit down and let the professionals handle it.”
“Mom, move,” I said, my voice dropping an octave as a cold, terrifying realization washed over me. This wasn’t about an investment property. Mark hadn’t just taken out a loan; he was liquidating our entire estate behind my back.
The investigator ignored Eleanor and clicked open the destination routing profile. The account name flashed in bold letters across the screen: The Arthur & Eleanor Vance Family Trust.
I staggered backward, hitting the edge of a mahogany desk. My mother-in-law’s private family trust. The very trust Mark had supposedly dissolved five years ago when we bought our family home together.
“You didn’t just help him take out a loan,” I whispered, staring at Eleanor as the pieces violently clicked together. “You’re buying him out. Or worse… you’re hiding him.”
Eleanor’s eyes narrowed into slits. She didn’t deny it. Instead, she checked her diamond wristwatch, let out a cold sigh, and whispered something that froze the blood in my veins. “Mark isn’t at the office today, dear. He hasn’t been there all week. And if you think this $218K is the worst thing he left behind in your name, you are catastrophically naive. The police are already at your house.”
Do you have any predictions for what might happen next? Feel free to share your thoughts 👇
part 3:
The moment Eleanor uttered those words, my phone buzzed violently in my pocket. It was a push notification from my home security system: Front door motion detected. Emergency services on site.
I didn’t care about the bank anymore. I didn’t care about the mortgage paperwork scattered across the desk or Eleanor standing there like a statue of judgment. I bolted out of the branch, jumped back into my truck, and drove home with the hazard lights flashing, breaking three red lights along the way.
When I pulled into my driveway, two unmarked police cruisers and a county sheriff vehicle were parked sideways across my lawn. My front door stood wide open.
Officer Miller, a local cop I coached youth baseball with, stepped out onto the porch holding a pair of heavy-duty evidence bags. When he saw me sprint up the driveway, his expression was a mix of profound pity and stern duty.
“Arthur,” Miller said, putting a heavy hand on my shoulder as I tried to push past him. “You need to step back. You can’t go inside right now.”
“What is going on?” I screamed, my voice cracking with pure panic. “My credit app showed a debt, my mother-in-law is laundering money through a phantom trust, and now my house is a crime scene? Where is Mark?”
Miller let out a long, heavy sigh and gestured for me to sit on the brick steps. “Mark isn’t missing, Arthur. And he didn’t take out a loan to buy an investment property. Around 4:00 AM this morning, local dispatch received an anonymous tip reporting a major commercial fraud and tax evasion operation run out of a shell company. The primary registered agent on that corporate account—the one pulling hundreds of thousands of dollars in fraudulent federal pandemic relief loans over the last three years—was registered using your social security number and your home address as the corporate headquarters.”
I felt the ground drop out from beneath me. The air rushed out of my lungs. “My… my social security number? But I’ve worked a legitimate W-2 job for twelve years. I’ve never incorporated a business!”
“No, you haven’t,” Miller said gently, handing me a printed copy of a corporate filing retrieved from the state database. “But someone with power of attorney, full access to your home office files, and your personal seal has been filing paperwork under your identity since 2023. Look at the signature witness line.”
I looked down at the paper. Stamped neatly at the bottom, certifying the authenticity of the corporate filings, was the official notary seal and signature of Eleanor Vance.
It all came crashing together in a horrifying, blinding flash of light. Mark hadn’t just betrayed our marriage; he had run up massive federal liabilities, embezzled funds through a fake shell company, and meticulously framed me to take the fall when the house of cards finally collapsed. When the federal investigation started closing in last week, Mark panicked, emptied our liquid savings, and tried to strip the equity from our home using an emergency power of attorney engineered by his own mother to leave me penniless, homeless, and facing federal fraud charges while he fled the country.
And Eleanor wasn’t at the bank to help him invest—she was there to execute the final asset seizure before the federal freeze hit our accounts, ensuring her golden-boy son could escape cleanly across the Canadian border while leaving her innocent son-in-law holding a federal indictment.
Just as the full weight of the nightmare settled over my shoulders, my phone rang again. An unknown number with an international country code.
With trembling fingers, I pressed accept and put it to my ear.
“Hello, Arthur,” Mark’s voice came through the speaker, chillingly calm, devoid of any guilt or remorse. “I’m sorry it had to end this way. But look at the bright side—at least the house is finally off your hands.”
Before he could hang up, I heard the heavy clunk of handcuffs snapping around my wrists as Officer Miller regretfully read me my rights. But as the cold steel locked into place, a strange, absolute clarity washed over me. Mark thought he had won. He thought his mother’s legal maneuvers and his meticulous framing had buried me forever. He didn’t know that before I left the house this morning, my dashcam had automatically uploaded every single text, email, and audio recording from Eleanor’s threats in the bank lobby directly to my cloud storage—and shared it with the federal prosecutor handling the regional fraud task force.
The trap was set. But it wasn’t mine anymore.
As the patrol car door slammed shut, I looked out the window and watched Eleanor standing at the edge of my lawn, her phone pressed to her ear, smiling as she waited for the confirmation of her son’s escape. I smiled back, knowing her phone call was being recorded by federal agents sitting just two cars down. The nightmare was real, but the reckoning had only just begun.