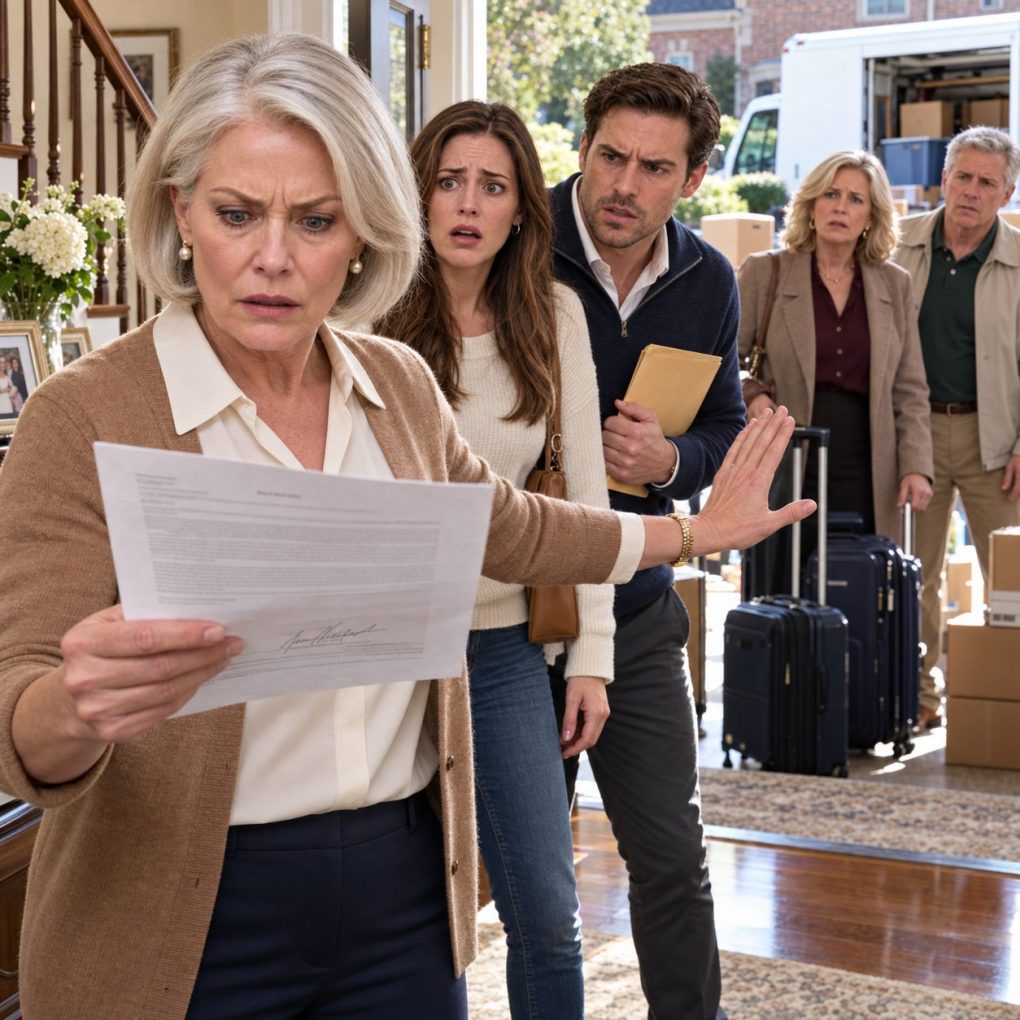
The first thing my daughter said when I opened the door was, “Mom, move your car. We need the whole driveway.”
Behind Emily stood her husband, Ryan, his parents, two suitcases, six plastic storage bins, and a rented cargo van packed to the ceiling.
I stared at them. “What is this?”
Emily stepped past me as if she still lived there. “This is my new life, Mom. Ryan’s parents are staying with us now. We’ll take the upstairs bedrooms.”
For a second, I genuinely thought I had misunderstood her.
I’m Linda Parker, fifty-nine, widowed, and that brick house outside Raleigh is the one thing my husband, Mark, and I spent thirty years paying off. Emily had a key because she was my daughter, not because my home was a family hotel.
Ryan’s mother, Denise, rolled a suitcase over my threshold.
I put my hand on the handle. “No. Nothing comes inside.”
Emily’s face hardened. “You’re embarrassing me.”
“You arrived without asking.”
“We’re family.”
“That doesn’t turn my house into yours.”
Ryan finally spoke. “Linda, everyone’s had a rough few months. My parents sold their place, and our lease is ending. Emily said you had plenty of room.”
Sold their place?
That was the first thing that didn’t make sense. Three weeks earlier, Denise had posted photos online from what she called her “forever home.”
I looked at Emily. “How long were you planning to stay?”
She glanced at Ryan before answering. “We don’t know yet.”
That meant indefinitely.
I felt something inside me go very still.
For the past four years, I had helped Emily far more than she knew I could afford. I paid $1,400 of her monthly rent when Ryan’s commission checks were “slow.” I covered her car insurance, phone plan, and several credit-card emergencies. When they married, I paid nearly $18,000 toward the wedding because Emily cried that she didn’t want to start married life in debt.
Apparently, I had not been helping them get on their feet.
I had been teaching them that my wallet had no bottom.
I pointed toward the driveway.
“No. You are all leaving my house, and today I stop covering your expenses.”
Emily’s mouth fell open.
Then she screamed.
“You can’t do that!”
The sound was so sharp that Denise froze beside the suitcase.
“I absolutely can.”
“No, you can’t!” Emily shouted again, but this time there was panic underneath the anger. “You don’t understand what you’ll ruin.”
Ryan moved toward her. “Emily, stop.”
She jerked away from him.
That was when I noticed the thick manila envelope tucked under Ryan’s arm.
My name was written across the front.
Not Emily’s.
Mine.
I held out my hand. “What is that?”
Nobody answered.
“Ryan. Give me the envelope.”
He stepped backward.
Emily suddenly looked terrified.
Then Denise whispered, “She was going to find out eventually.”
I felt my stomach drop.
Ryan tightened his grip on the envelope, but a single sheet slipped out and landed faceup on my entryway floor.
At the bottom of the page was a signature.
My signature.
Except I had never signed it.
I thought the worst betrayal was my daughter trying to move four adults into my home without permission. Then I picked up that paper and realized this had started long before the van reached my driveway. And whatever they had done, they needed my house for a reason.
I bent down and picked up the page before Ryan could stop me.
It was a photocopy of a quitclaim deed.
According to the document, I had transferred a fifty-percent ownership interest in my house to Emily for ten dollars and “love and affection.”
The signature looked close enough to mine to fool someone who had only seen it on checks.
It would not fool me.
I looked at Emily. “Where did this come from?”
She was crying now, but not the way she cried when she wanted sympathy. She looked cornered.
Ryan said, “It’s not what you think.”
“Then explain why there is a deed with my forged signature on it.”
Denise sat down on my foyer bench.
Emily blurted, “I thought you signed it.”
That answer made me angrier than a confession.
“You thought I gave you half my house and forgot to mention it?”
She covered her face.
Ryan said the document was part of “estate planning,” that a notary had handled everything, and that I was overreacting because the house would eventually pass to Emily anyway.
That sentence changed the room.
Eventually.
As if my death were already part of their financial plan.
I took out my phone.
Ryan’s expression changed. “Who are you calling?”
“My attorney.”
He reached toward me, then stopped when I told him not to touch me.
Emily began pleading. She said there was a closing scheduled for Monday.
I asked what closing.
Nobody answered.
Then I understood.
The forged deed was not the end of the scheme. It was the beginning.
I called my attorney, Susan Bell, and put her on speaker. I read the parcel number from the document. Susan told me to check the county register of deeds website.
The deed had been recorded three days earlier.
My knees almost gave out.
Then Susan found something worse.
A lender had recorded a notice connected to a pending home-equity transaction. The amount listed was $185,000.
I stared at Ryan.
His father, Paul, had barely spoken. Now his face went gray.
Susan told me not to sign anything, not to surrender possession of the house, and to photograph every document. She said she would contact the lender’s fraud department and challenge the transfer.
Then Emily whispered, “Ryan said the money was for his dad’s business.”
Paul looked at his son.
“What money?”
Ryan turned pale.
Denise stood so fast the bench scraped the wall.
Paul repeated the question.
Ryan said nothing.
Then Denise looked at me and said, “Linda, we didn’t sell our house.”
I stared at her.
“We lost it.”
Paul pulled another statement from the envelope and discovered his name was on a debt he had never seen.
Ryan had not brought his family to my house because they needed somewhere to stay.
He had brought them because the entire plan was collapsing.
For several seconds, nobody moved.
Then Paul looked at Ryan and asked, very quietly, “How much?”
Ryan tried to say they should discuss it privately.
Paul grabbed the papers from the envelope instead.
There was a $42,000 business line of credit carrying Paul’s information. There were late-payment notices. There was a lender worksheet showing the proposed $185,000 loan against my house. And there was an appraisal appointment scheduled for Monday morning.
That explained the sudden invasion.
Ryan needed access to my house and a way to make the lender believe Emily had authority over the property. He had told his parents I had agreed to let everyone move in. He had told Emily that transferring half the house was something I had arranged to “protect her inheritance.”
He had told me nothing.
Susan stayed on speaker while I photographed every page. She told me to send everything to her, secure my financial records, and make a police report documenting the suspected forgery and attempted loan.
Ryan actually laughed.
“You’re really going to have your son-in-law arrested over paperwork?”
I stared at him. “You forged my name to take $185,000 against my home.”
Emily whispered, “Mom, please.”
“No. You don’t get to ‘Mom, please’ me out of this.”
I told all four of them to leave. Paul and Denise did immediately. Ryan resisted until Paul grabbed his arm and told him to go.
Emily remained in my foyer.
I asked her one question.
“Did you give Ryan any of my personal documents?”
Her answer took too long.
Months earlier, Emily had been in my office helping me scan insurance papers. Ryan had asked her to photograph my driver’s license and a document containing my signature. He claimed their financial adviser needed them for an inheritance worksheet.
Emily knew it was strange.
She did it anyway.
“I didn’t know he would forge anything,” she said.
“I believe you didn’t know everything. But you knew enough to ask me.”
That was the part that hurt most. Ryan had committed the fraud, but my daughter had opened the door because asking my permission might have produced an answer she didn’t want.
I took back her house key before she left.
That afternoon, I changed every password, stopped the monthly rent transfer, removed my payment method from her phone and car insurance accounts, froze the emergency credit card, and placed fraud alerts with the credit bureaus.
By Monday morning, the lender had frozen the transaction.
The appraisal never happened.
Susan notified the lender, title company, and county offices that I disputed the deed. Clearing the title would take time, but no loan proceeds were released.
Then the police investigation uncovered the rest.
Ryan had used a notary he knew socially. The notary certified that I appeared in person even though I had never met him. Investigators also found emails in which Ryan pushed for the loan to close before I could “change my mind.”
That was difficult to explain when I had never agreed.
Paul and Denise cooperated.
Their home had not been sold by choice. Eighteen months earlier, Ryan had convinced them to borrow heavily against it to invest in a contracting company he claimed was about to land major jobs. The jobs never came. He promised to make the payments, then stopped. They eventually lost the house.
The $42,000 credit line in Paul’s name was something Paul said he had never authorized.
Ryan had been trying to use my house to plug every hole at once: overdue debts, his parents’ losses, and the collapsing image of a successful husband.
He almost succeeded because all of us had been covering for him in different ways.
Paul covered for his son.
Denise covered out of shame.
Emily covered because she wanted her marriage to look stable.
And I had covered Emily’s expenses because I confused rescuing her with loving her.
That ended at my front door.
Six weeks later, Emily asked to come over alone.
We sat on the back porch.
She had moved into a small apartment, started paying her own bills, taken extra hours at the medical office where she worked, and filed for separation from Ryan.
“I kept thinking you would always fix things,” she said. “Then I married someone who thought the same thing.”
I told her forgiveness would not mean returning to the old arrangement.
No monthly subsidy.
No emergency card.
No key.
No access to my financial information.
And no pretending her choices were harmless simply because Ryan’s were worse.
She nodded. “I understand.”
“I’m going to watch what you do, not what you promise.”
Over the next several months, she did the work.
She paid her own rent. She sold the luxury SUV she could no longer afford and bought a used Honda. She gave investigators every message Ryan had sent about my documents. Most importantly, she stopped asking me to rescue her.
The legal mess took longer.
Eventually, the fraudulent deed was removed from my title through the proper legal process. The lender closed the loan application. Ryan was charged in connection with the forged deed and fraudulent credit applications and later entered a plea that carried criminal penalties and restitution obligations. The notary also faced consequences for falsely certifying my appearance.
Paul and Denise moved into a modest rental. I did not invite them to live with me, but I no longer blamed them for arriving that first day. They had been lied to too.
Nearly a year after the van appeared in my driveway, Emily came over for dinner.
She rang the bell.
That tiny detail nearly broke my heart.
My daughter, who once walked in and announced that my house belonged to her new life, now waited for me to open the door.
After dinner, she handed me an envelope.
My chest tightened.
Inside was a check for $500 and a note.
First payment. For everything I should have learned to carry myself.
“You don’t owe me every dollar I spent on you,” I said.
“I know. This isn’t for the past. It’s so I remember who I want to be next.”
I did not cash the check.
I framed the note.
My house is still mine. The title is clean. The upstairs bedrooms are quiet.
My relationship with Emily is not what it used to be. It is more careful, but it is also more honest.
I used to believe being a good mother meant keeping my daughter from falling.
Now I know sometimes love means refusing to become the floor.
The day Emily screamed because I stopped paying for her life felt like the day I lost my daughter.
It turned out to be the day both of us finally learned that family does not mean surrendering your home, your money, or your boundaries.