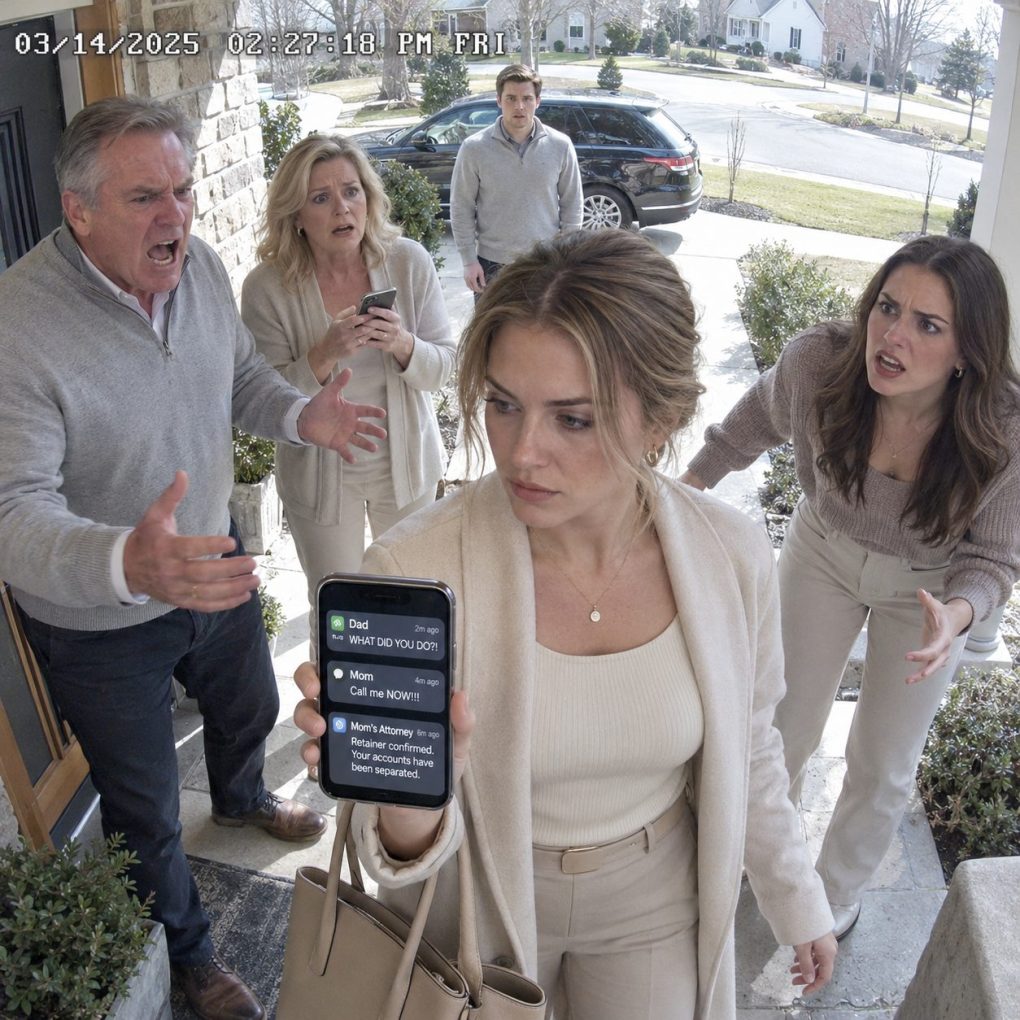
Dad texted, You’re no longer family. Never show your face again. I replied, Understood. That night, I withdrew my pending investment and notified the trust officer. By sunrise, my sister was screaming over a stalled $2.8 million loan closing. Mom had already blocked my number.
I’m Allison Reed, thirty-six, a commercial appraiser in Minneapolis. Our family owned rental buildings through Reed Properties, an LLC. I held thirty percent; my parents and younger sister, Brooke, owned the rest. Grandma’s separate trust owned the lakeside lodge.
Dad had been arranging financing to convert the lodge into an expensive wedding venue for Brooke. He wanted my appraisal work, a $400,000 investment, and my personal guarantee. He wanted the lodge pledged as collateral, though the bank serving as trustee had approved no such pledge.
I agreed only to consider the deal after reviewing financial statements. The $400,000 remained in a refundable escrow account, and I had signed neither a guarantee nor a final investment agreement. Dad called my conditions insulting. I still believed we could make the project work without betting my future.
At a family meeting, I found vendor invoices that included $180,000 for renovations supposedly completed before permits were issued. Brooke accused me of sabotaging her project. Mom said a loyal daughter wouldn’t interrogate her own father. Three days later came Dad’s text.
I canceled my escrow commitment under its written deadline, declined the unsigned guarantee in writing, and gave notice that I would seek a buyout of my LLC interest under our operating agreement. That didn’t erase my ownership or anyone else’s rights.
I also forwarded the questionable invoices to the independent trust officer, Evelyn Marsh, and asked her to verify any documents authorizing the lodge as security. Grandma had established the trust to protect beneficiaries, not to provide Dad with an unrestricted line of credit.
Friday morning, Brooke sent fourteen furious messages. The lender had paused its closing because it could no longer count on my contribution or guarantee. She had promised investors that every signature was secured. Dad’s accountant then called, claiming I was destroying the business and demanding reinstatement.
Mom’s lawyer emailed at 6:21 requesting an urgent conversation. Attached was a beneficiary-consent form allegedly signed by me, approving the pledge of Grandma’s lodge. It bore a date when I was working in another state.
I called my own attorney instead. I had never signed that page. Before I finished, Evelyn called from the bank: Allison, she said, we have found two different versions of this document. And one appears to have been submitted by your father. I had been disowned for asking questions, but the answers were finally arriving.
My attorney, David Kim, asked me to preserve Dad’s text, the escrow instructions, and every loan document I could lawfully access. He contacted Evelyn. She confirmed that the bank had not approved a mortgage on the lodge and that the consent was under review.
The versions were nearly identical. One contained a blank signature line; the other showed my name inserted beneath a scanned signature from another property document. Records identified an email from Dad’s office as the source of the altered version.
Dad called and claimed he had only been speeding up paperwork. When I asked whether he had inserted my signature, he said Brooke’s future mattered more than technicalities. I reminded him that forged consent wasn’t a technicality and that the lodge wasn’t his to gamble.
Grandma had established the trust after watching relatives lose properties to reckless borrowing. Its independent trustee controlled financing decisions, and beneficiaries couldn’t order it to mortgage the lodge. My missing signature wasn’t the only defect; Dad had never obtained the trustee’s formal approval.
Brooke arrived at my office furious. She had already invited investors to a groundbreaking ceremony and ordered custom furnishings. She said withdrawing my contribution made her look like a fraud. I asked why she had signed contracts before she knew funding was approved.
Then David showed us a payment ledger. Reed Properties had transferred $96,000 to Brooke’s venue company for planning costs, without the LLC members’ authorization. Those reserves were supposed to pay for building repairs, not her wedding business. The vendor name matched the invoice I had questioned Sunday.
Brooke insisted Dad had promised the advance was approved. She quieted when she learned the transfer came from reserves earmarked for replacing aging apartment boilers. Several tenants had reported unreliable heat, and the work had already been postponed twice.
I asked the property manager to document the repair needs and notified the other members that the funds required an accounting. I didn’t drain the LLC account or seize its buildings. Our lawyers arranged for independent oversight of essential expenses while the ownership dispute was resolved.
Mom finally admitted she had seen Dad assembling the signature pages. She thought I would sign later and told herself the bank wouldn’t notice. Her lawyer wanted us to settle privately because the financing application exposed the family to questions beyond a missed closing.
I told her I was willing to discuss legitimate business obligations, not conceal altered documents. That evening, Dad left another voicemail, no longer ordering me home. He said losing the lodge would ruin Grandma’s memory. I stared at the trust agreement and wondered when he had forgotten why she created it.
The bank rejected the proposed pledge and referred the suspicious consent form for further investigation. No mortgage had been recorded against the lodge, and the $2.8 million loan never funded. My escrow deposit was returned according to its agreement, minus a modest processing fee.
An independent accountant examined Reed Properties’ records. The review confirmed unauthorized transfers to Brooke’s venue company and several postponed maintenance bills. With counsel involved, the LLC recovered part of the money and adopted controls requiring documented approval for transactions involving family-owned businesses.
The apartment boilers were replaced before the coldest weeks of winter. Tenants received updates from the property manager rather than excuses from Dad. Their heat mattered more than winning an argument. Real families lived behind the balance-sheet entries Dad had treated as movable numbers.
Dad stepped down as managing member during negotiations. Questions about the altered form went through legal channels; nobody escaped scrutiny because of a family connection. I cooperated with requests for records but refused to predict whether anyone would face charges.
Brooke abandoned the lodge conversion. She returned unused furnishings and worked out payment plans for contracts she’d signed too early. Losing the project hurt, but she couldn’t blame me for refusing to guarantee an unapproved loan.
Under our operating agreement, an independent valuation determined the price for my ownership interest. The remaining members arranged an installment buyout, and I transferred my shares only as payments and signed documents required. I didn’t walk away with instant millions or leave the properties without operating funds.
Mom asked to meet for coffee. She admitted she’d considered my steady income a family resource and my questions a betrayal. I told her Grandma had raised us to protect what others depended on. Supporting family didn’t mean signing away my home or ignoring missing repair money.
Dad eventually sent a handwritten apology. He acknowledged the false document and the text that expelled me from the family. I appreciated the words but didn’t return to the business. I needed accountability without another financial emergency. His apology was the first time he had acknowledged my feelings without asking for anything.
That spring, I drove past the lakeside lodge. Its porch was freshly painted, and a couple sat watching the water. The bank trustee had approved modest maintenance, not a grand redevelopment. It looked like the place Grandma had loved, and I finally felt peaceful there.
Dad had said I was no longer family, certain the threat would make me sign. Thirty-six hours later, everyone suddenly wanted me back. I had not destroyed their assets or taken what wasn’t mine. I simply stopped offering my signature as proof of love, and let the documents speak for themselves.