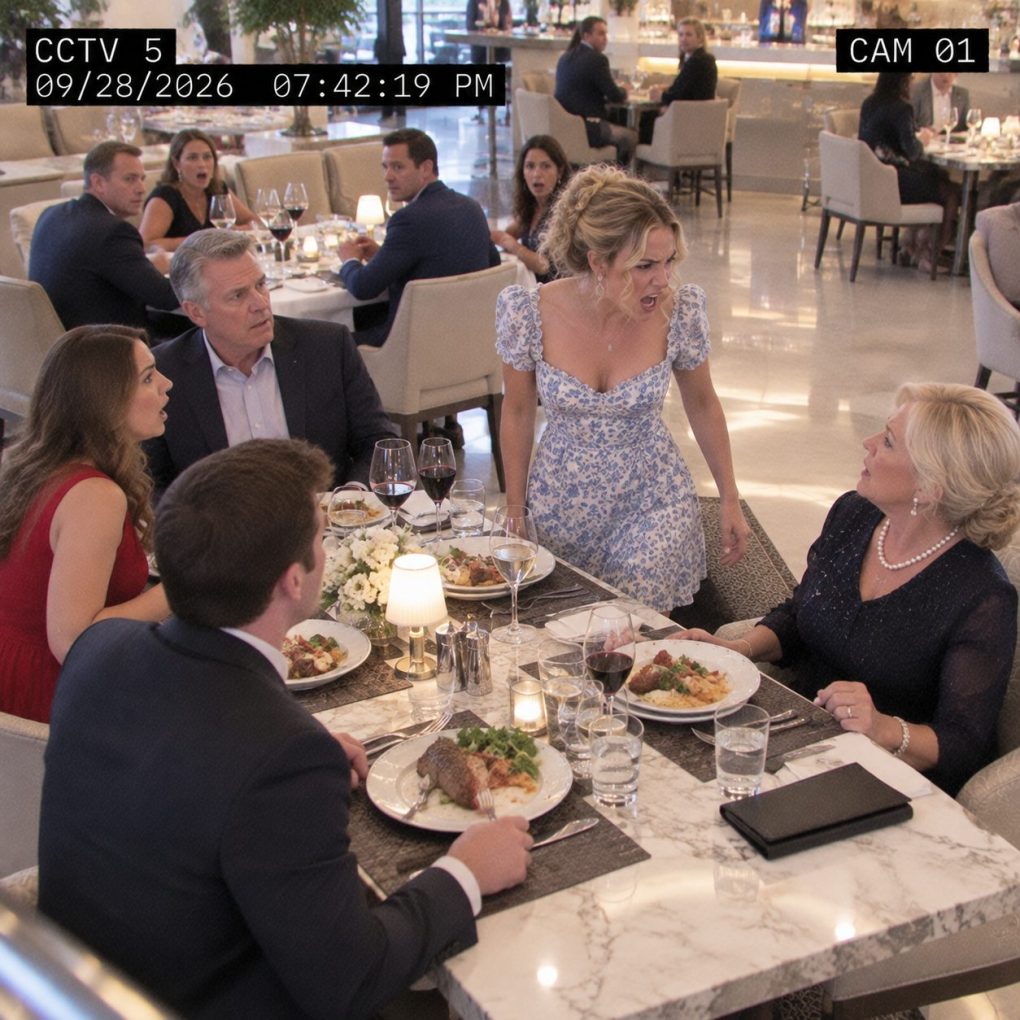
My daughter-in-law’s mother had been making jokes about me since the appetizers arrived.
Pamela held up the wine list and laughed, “Careful, Margaret. Some of these bottles cost more than a month of Social Security.” My son, Nathan, stared at his menu. His wife, Brooke, smiled awkwardly but said nothing. Twenty minutes later Pamela asked whether I still shopped at “those little discount stores,” then announced to the table that retirement must be wonderful when “someone else is always picking up the tab.” The irony was almost impressive. I had paid for Nathan’s college education, helped him through two failed businesses, and spent the previous six months reviewing financial projections for the restaurant company he and Brooke planned to launch. Pamela knew none of that. Brooke did.
I finally said, “Pamela, I came here to celebrate Nathan and Brooke. Could we have one dinner without making me the entertainment?”
Pamela rolled her eyes. “It was a joke.”
“It stopped being funny three jokes ago.”
Brooke put down her fork.
Then she looked directly at me.
“If you don’t like my mother’s jokes, pay for everyone and leave.”
Nathan whispered, “Brooke…”
But that was all.
He did not defend me.
I looked around the table. Twelve people. Pamela’s husband. Brooke’s brother. Two potential business partners. Nathan’s accountant. People who apparently believed I was the difficult mother ruining an elegant celebration.
So I smiled.
“Certainly.”
When the waiter returned, I asked for the entire bill.
It was $2,864.37.
I paid it, added a generous tip, stood, kissed Nathan on the cheek, and said, “Congratulations on the new company.”
Brooke looked almost disappointed that I had not caused a scene.
Pamela raised her glass.
“See? Everyone’s happy.”
I walked out.
In the parking garage, I sat behind the wheel for five minutes before opening my laptop.
The dinner had been celebrating the planned acquisition of three struggling neighborhood restaurants that Nathan intended to combine under a new hospitality company called Northline Dining Group. I had agreed to consider investing $750,000 as cornerstone capital, but only after final financial due diligence. Nothing had funded. My attorney had deliberately made the commitment nonbinding until I reviewed the complete numbers.
Nathan knew that.
Or I thought he did.
I logged into Northline’s investor portal.
The presentation had been updated that afternoon.
On page six was a capital table.
Beside my name:
Margaret Hale — $750,000 — COMMITTED / CONFIRMED.
I stared at it.
I had confirmed nothing.
Then I noticed something else.
The presentation claimed my participation had already helped secure another $1.4 million from outside investors.
My phone buzzed.
Nathan.
I declined the call.
Then I emailed my attorney, Helen Ward.
Do not release any funds. I want the full investor file tonight.
She called four minutes later.
“Margaret, there’s a problem.”
“What kind?”
“The restaurant deal closes in nine days.”
“I know.”
“No,” she said carefully. “I mean they’re already treating your money as available at closing.”
“That’s their mistake.”
Helen was silent for a moment.
“Possibly.”
“What does that mean?”
“It means someone submitted a signed investor confirmation in your name yesterday.”
I stopped breathing.
“I didn’t sign anything yesterday.”
“I know.”
Then she said the sentence that turned one humiliating dinner into something much larger.
“The document was uploaded from Brooke’s email account.”
Helen told me not to confront anyone until we understood exactly what had been submitted. By midnight, she had obtained the investor confirmation, the current closing checklist, and several versions of Northline’s capital schedule. My supposed commitment appeared in all of them.
The signature looked genuine because it was genuine—just not on that document. Someone had lifted my electronic signature from an earlier confidentiality agreement and placed it beneath language stating that $750,000 would be available unconditionally at closing.
I had never agreed to that. My actual letter of intent clearly stated that any investment depended on satisfactory financial review, final legal documents, and my written approval after diligence. Helen immediately notified Northline’s transaction counsel that I disputed the confirmation and that no one had authority to treat my funds as committed.
Nathan called before sunrise. His first words were not an apology. “Mom, please don’t do anything until I explain.” I asked whether he knew my investment had been marked confirmed. After a long pause, he said Brooke handled investor communications because he was focused on restaurant operations.
“That wasn’t my question.” Another pause. Then: “I knew they were counting on you.”
Counting on me and having permission were not the same thing.
Brooke finally joined the call. She insisted the signature issue was “administrative” and said everyone understood I intended to invest anyway. Helen asked her a simple question: “Can you produce one message where Margaret waived the conditions in her letter?” Brooke could not.
The outside investors were informed because my supposed commitment had been presented to them as part of the capital already secured. Two paused their investments until the numbers were corrected. Nobody accused Nathan or Brooke of a crime on the spot. Their lawyers began reviewing exactly who prepared the document, who approved it, and what representations had been made.
Then my financial diligence uncovered a second problem. Northline’s projections assumed the acquired restaurants could increase profit margins dramatically within eighteen months, partly by reducing management costs. Yet one new expense appeared in every forecast: a $12,000 monthly “brand advisory fee.”
The recipient was Pamela’s consulting company.
Pamela had never run a restaurant. Her career had been in residential real estate. According to the agreement Brooke prepared, her mother would receive $144,000 a year for “brand positioning, community relations, and executive counsel,” guaranteed for three years.
Nathan claimed he had never seen the final contract. Brooke said her mother’s networking connections justified the fee. Maybe they did. But potential investors had not been clearly told that a large recurring expense would go to the founder’s mother under a related-party agreement.
That disclosure problem mattered more to me than Pamela’s jokes. I could survive being mocked over dinner. I was not willing to invest three-quarters of a million dollars into a company where personal relationships were being hidden inside operating expenses.
By noon, I formally withdrew from the investment under the conditions in my unsigned final documents. The deal did not instantly disappear. Nathan still had nine days, other investors, three target restaurants, and advisers trying to restructure the financing.
Then one of the outside investors requested the original financial model. When Nathan’s accountant compared it with the version used at dinner, he discovered Pamela’s advisory fee had been placed under a generic line labeled regional services.
Nathan called me again.
This time his voice sounded different.
“Mom,” he said, “I think I’ve been signing things I didn’t understand.”
I closed my eyes.
For years, I had rescued my son every time confidence outran preparation.
This time I answered differently.
“Then start understanding them.”
Northline did not close nine days later. The buyers and sellers agreed to extend the deadline while Nathan reorganized the investment group and corrected the disclosures. It was embarrassing, expensive, and entirely preferable to closing a multimillion-dollar transaction built on misunderstandings.
Brooke initially blamed me. She told Nathan I had destroyed the deal because her mother embarrassed me at dinner. Nathan repeated that accusation once. I sent him the disputed investor confirmation, my conditional letter, and Pamela’s three-year advisory agreement. “Which of these was caused by a joke?” I asked. He never said it again.
The lawyers determined that Brooke had prepared the investor confirmation using my old electronic signature and uploaded it believing my investment was effectively certain. Whether she thought that was harmless did not change the fact that she had no authority to do it. The document was withdrawn and corrected across the transaction files.
Pamela’s advisory agreement was terminated before it began. She was furious. She called me vindictive and said wealthy people always used technicalities when they wanted control. I reminded her that the technicality in question was consent to invest $750,000.
Nathan surprised me after that. Instead of abandoning the acquisition, he hired an experienced restaurant CFO, rebuilt the forecasts, reduced the purchase from three locations to two, and approached investors with a far less glamorous but much more believable plan.
The revised deal closed four months later without my money.
Nathan owned less of the company than he originally expected because outside investors negotiated stronger terms. He also had less debt, lower fixed costs, and professional financial controls. For the first time, the business existed without me standing underneath it.
Brooke and Nathan entered counseling. Their marriage had larger problems than one forged-looking document: Brooke made decisions to protect appearances, while Nathan avoided difficult conversations until someone else handled them. I stayed out of whether they could repair that.
Brooke apologized to me almost eight months after the dinner. She did not begin with Pamela. She said, “I treated your investment like family money that was already ours.” That was the first apology I believed.
I asked her about the dinner.
She looked embarrassed. “I knew Mom was being cruel. I told you to pay because I thought you’d never actually leave.”
That sentence hurt more than Pamela’s jokes.
They had mistaken my patience for dependence.
A year later, Northline’s two restaurants were still operating. Not spectacularly. Not as the empire Nathan once described. But profitably. He sent me quarterly updates even though I was not an investor because he said rebuilding the numbers had taught him more than my money ever could.
Then he invited me to dinner.
Same restaurant.
Different table.
Pamela was not there.
When the check arrived, Nathan reached for it before I could.
“No,” I said, smiling. “I can afford my own dinner.”
“I know.”
He held the bill anyway.
“This one isn’t about whether you can.”
That was the difference.
I had spent years believing helping my son meant smoothing the road ahead of him. Tuition. Business advice. Emergency loans. Introductions. Capital whenever his next idea seemed promising.
Sometimes support is useful.
Sometimes it becomes camouflage for decisions adults should learn to own themselves.
The night Brooke told me to pay and leave, she thought she was humiliating an older woman who needed a seat at their table.
So I paid.
And I left.
What shocked everyone afterward was not that I had enough money to matter.
It was that the money still belonged to me until I chose to give it.
The $750,000 never entered Northline.
Yet losing it may have saved Nathan’s company.
And walking away from that dinner may have saved something more important for me.
I stopped paying for the privilege of being tolerated.