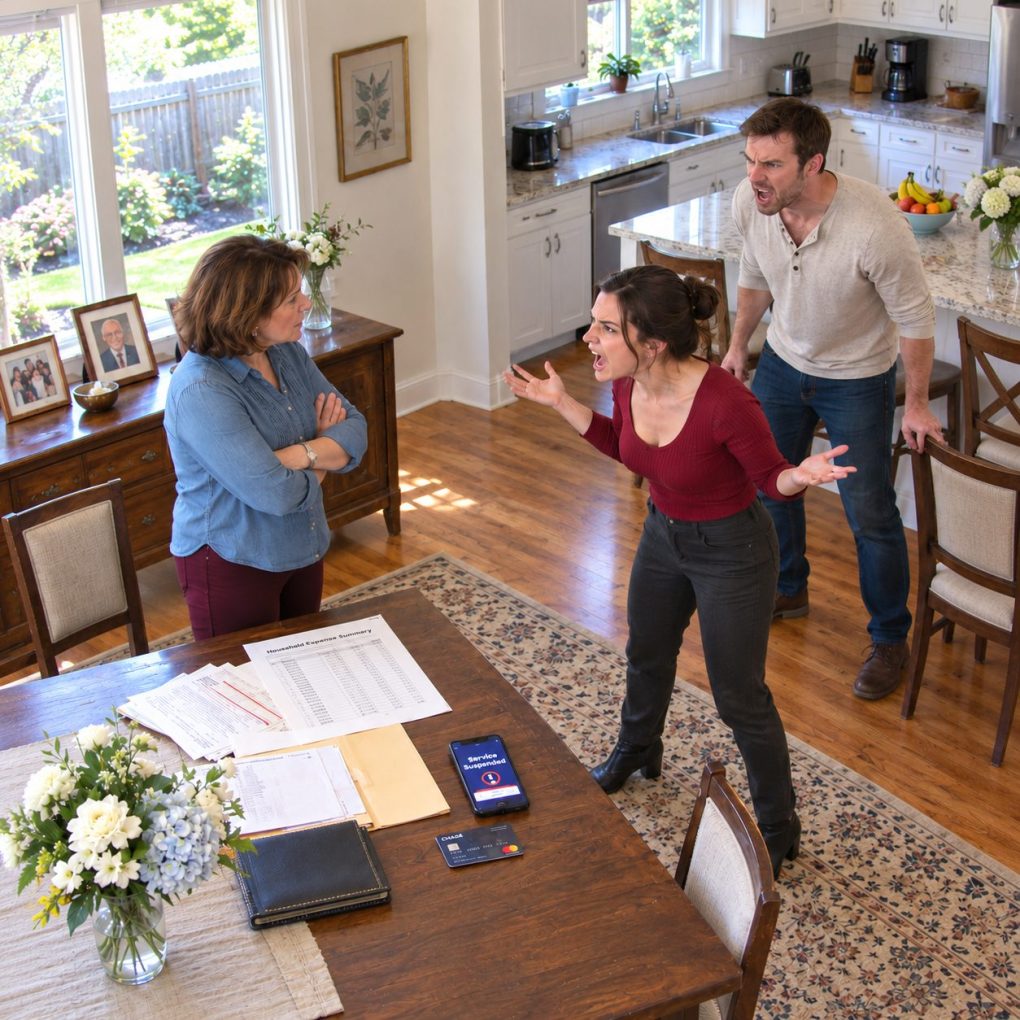
“You’re financially irresponsible, Evelyn. Sell this house before you ruin everyone,” my daughter-in-law announced across my kitchen table. My son Michael nodded as if she’d made a reasonable suggestion. I said nothing, but that night I canceled thirty-one automatic payments I’d been making for them.
By seven the next morning, their internet service was suspended, and two credit cards stopped working. My phone rang while I was watering the roses. Vanessa, my daughter-in-law, was screaming, “What have you done to us?” I finally had an answer ready.
I’m sixty-four and live in Raleigh, North Carolina, in the house my late husband and I paid off together. Michael is thirty-seven; Vanessa is thirty-five. They earn decent salaries, but for four years I’d quietly covered expenses they always promised to take over.
It began when Michael was laid off. I paid their car insurance and grocery bills until he found work. Then came their phone plan, utility deposits, student-loan installments, streaming services, and minimum payments on debts they insisted were temporary.
Yesterday Vanessa arrived carrying listings for retirement apartments. She wanted me to sell my three-bedroom home and give them the proceeds as a down payment on a larger house. When I refused, she called me selfish, incompetent, and incapable of managing money.
“Your father would be ashamed,” Michael added. He knew exactly how much that sentence would hurt. I’d spent twenty-six years helping my husband restore this place, and Michael was asking me to surrender it so he could purchase a home with a swimming pool.
After they left, I opened the budgeting spreadsheet they’d never bothered to see. Thirty-one recurring transfers and card charges were attached to their household, totaling nearly four thousand dollars monthly. I canceled future automatic payments and removed them as authorized users from my credit accounts.
Their broadband account was also in my name. I requested a service suspension effective early morning, then sent them a written list of bills they’d need to arrange themselves. Their own bank accounts remained untouched; I had simply stopped financing their lifestyle.
When Vanessa called, I put the phone on speaker. “Our cards were declined at breakfast,” she shouted. “And there’s no internet!” I explained that the cards belonged to accounts I owned and the broadband service was registered to me. She demanded I fix everything immediately.
Then Michael grabbed the phone. “Mom, you’re destroying our lives over one conversation!” he yelled. I looked at my husband’s photograph on the mantel and replied, “No, Michael. I’m letting you pay for the life you chose.” Then someone knocked at my front door.
A real estate agent stood on my porch, carrying a tablet and measuring equipment. Vanessa had arranged a property valuation, claiming I’d agreed to sell. I explained that I hadn’t authorized anything, and the embarrassed agent immediately left. My daughter-in-law had been planning my future without even asking me.
An hour later, Michael arrived with Vanessa and a stack of unpaid bills. They demanded that I reinstate every payment before their accounts became overdue. I invited them inside but left the front door open, determined not to repeat another conversation behind closed doors.
Vanessa waved a car-loan statement at me. She claimed I had promised to pay until the vehicle was fully owned. I produced our messages from two years earlier, where she’d agreed to assume the installments after receiving her promotion. She had received that promotion eighteen months ago.
I explained that stopping an automatic payment did not erase their debts or instantly disconnect every service. Their electricity, insurance, and loans still existed, with due dates they needed to meet. Only the internet subscription under my name was suspended, and their authorized-user credit cards had been disabled.
Michael looked at the spreadsheet I’d printed. There were thirty-one lines: insurance premiums, phone charges, car installments, credit-card minimums, subscriptions, and small recurring household expenses. He was stunned by the total. Vanessa accused me of exaggerating until I showed her the bank statements.
Over forty-six months, I’d spent more than one hundred and forty thousand dollars helping them. Some months had been cheaper, but the pattern was undeniable. Meanwhile, they had taken two vacations abroad and leased a luxury SUV without asking whether my retirement savings could withstand their choices.
“Why didn’t you tell us you were struggling?” Michael asked. I reminded him of the three conversations where I’d requested a repayment plan. Each time, Vanessa had accused me of trying to control them, and he had promised to discuss it later. Later had never arrived.
Vanessa announced that she’d contact a lawyer because I had damaged their credit. I told her my attorney could review any allegation. Then I slid across the notice I’d drafted: future support was ending, and they had thirty days to transfer any essential services in my name to accounts they controlled.
Michael studied the paper, then admitted he had believed my pension was much larger. I told him my pension was modest and that I’d been drawing down savings to keep them comfortable. Vanessa stared at the floor for the first time. Neither offered an apology.
After they left, Michael sent a message asking for copies of every bill and account deadline. I sent the spreadsheet and service-provider contacts, but no money. That evening he called again, speaking more quietly. “Mom,” he said, “I had no idea how close you were to running out.”
I wanted to believe Michael’s concern was genuine, but apologies required more than frightened words. I told him I would discuss practical steps, not another request for money. He agreed to meet me alone at the public library, where neither of us could easily turn the conversation into shouting.
Michael arrived with a notebook and a list of their actual household expenses. For the first time, he’d calculated what maintaining their lifestyle cost. Their combined income was enough for necessities, but luxury payments, credit-card balances, and impulse purchases consumed almost everything left over each month.
I suggested he speak with a nonprofit credit counselor and contact creditors before any missed payments occurred. He scheduled appointments and began transferring the phone and internet services into his name. I gave him account information he legitimately needed, but I didn’t co-sign a single new obligation.
Vanessa refused to attend the first counseling session. She told relatives I had cut off her family because I disliked her. When my sister asked for an explanation, I showed her the budget and the apartment listings Vanessa had brought. My sister said, “They’re treating your house like an inheritance you’re supposed to hand over early.”
A week later, Michael told me he and Vanessa had canceled the SUV lease after negotiating an early termination and reviewing the cost. They sold unused electronics, paused their vacations, and arranged realistic payment schedules. Some decisions were expensive, but their accounts were finally their responsibility.
Vanessa appeared at my door again the following Sunday. This time she came without property listings or threats. She apologized for calling me irresponsible and admitted she’d assumed I had unlimited money because I never complained. I accepted the apology without offering to resume a single payment.
I also changed the locks after retrieving the spare key I’d previously given them. That decision upset Michael, but I explained that my home was not an extension of theirs. They could visit when invited, and I would gladly share meals. They could no longer make decisions about my property.
Over the next three months, I rebuilt my emergency savings and stopped checking my phone in fear of another financial request. I planted roses along the back fence and repaired the porch swing my husband had loved. For the first time since his death, the house felt entirely peaceful.
Michael eventually thanked me for drawing a line. He said their budget meetings were uncomfortable but necessary, and he was embarrassed he’d allowed the burden to become invisible. Vanessa was still learning to accept limits, but she had stopped asking me to finance their purchases. That was progress enough.
One evening, Michael visited and found me reading on the porch. He asked whether I might someday leave him the house. I smiled and said, “Someday you’ll learn what my will says. Today, this is my home.” I had spent years paying thirty-one bills to keep the peace. Canceling them finally brought it back.“You’re financially irresponsible, Evelyn. Sell this house before you ruin everyone,” my daughter-in-law announced across my kitchen table. My son Michael nodded as if she’d made a reasonable suggestion. I said nothing, but that night I canceled thirty-one automatic payments I’d been making for them.
By seven the next morning, their internet service was suspended, and two credit cards stopped working. My phone rang while I was watering the roses. Vanessa, my daughter-in-law, was screaming, “What have you done to us?” I finally had an answer ready.
I’m sixty-four and live in Raleigh, North Carolina, in the house my late husband and I paid off together. Michael is thirty-seven; Vanessa is thirty-five. They earn decent salaries, but for four years I’d quietly covered expenses they always promised to take over.
It began when Michael was laid off. I paid their car insurance and grocery bills until he found work. Then came their phone plan, utility deposits, student-loan installments, streaming services, and minimum payments on debts they insisted were temporary.
Yesterday Vanessa arrived carrying listings for retirement apartments. She wanted me to sell my three-bedroom home and give them the proceeds as a down payment on a larger house. When I refused, she called me selfish, incompetent, and incapable of managing money.
“Your father would be ashamed,” Michael added. He knew exactly how much that sentence would hurt. I’d spent twenty-six years helping my husband restore this place, and Michael was asking me to surrender it so he could purchase a home with a swimming pool.
After they left, I opened the budgeting spreadsheet they’d never bothered to see. Thirty-one recurring transfers and card charges were attached to their household, totaling nearly four thousand dollars monthly. I canceled future automatic payments and removed them as authorized users from my credit accounts.
Their broadband account was also in my name. I requested a service suspension effective early morning, then sent them a written list of bills they’d need to arrange themselves. Their own bank accounts remained untouched; I had simply stopped financing their lifestyle.
When Vanessa called, I put the phone on speaker. “Our cards were declined at breakfast,” she shouted. “And there’s no internet!” I explained that the cards belonged to accounts I owned and the broadband service was registered to me. She demanded I fix everything immediately.
Then Michael grabbed the phone. “Mom, you’re destroying our lives over one conversation!” he yelled. I looked at my husband’s photograph on the mantel and replied, “No, Michael. I’m letting you pay for the life you chose.” Then someone knocked at my front door.
Part 2
A real estate agent stood on my porch, carrying a tablet and measuring equipment. Vanessa had arranged a property valuation, claiming I’d agreed to sell. I explained that I hadn’t authorized anything, and the embarrassed agent immediately left. My daughter-in-law had been planning my future without even asking me.
An hour later, Michael arrived with Vanessa and a stack of unpaid bills. They demanded that I reinstate every payment before their accounts became overdue. I invited them inside but left the front door open, determined not to repeat another conversation behind closed doors.
Vanessa waved a car-loan statement at me. She claimed I had promised to pay until the vehicle was fully owned. I produced our messages from two years earlier, where she’d agreed to assume the installments after receiving her promotion. She had received that promotion eighteen months ago.
I explained that stopping an automatic payment did not erase their debts or instantly disconnect every service. Their electricity, insurance, and loans still existed, with due dates they needed to meet. Only the internet subscription under my name was suspended, and their authorized-user credit cards had been disabled.
Michael looked at the spreadsheet I’d printed. There were thirty-one lines: insurance premiums, phone charges, car installments, credit-card minimums, subscriptions, and small recurring household expenses. He was stunned by the total. Vanessa accused me of exaggerating until I showed her the bank statements.
Over forty-six months, I’d spent more than one hundred and forty thousand dollars helping them. Some months had been cheaper, but the pattern was undeniable. Meanwhile, they had taken two vacations abroad and leased a luxury SUV without asking whether my retirement savings could withstand their choices.
“Why didn’t you tell us you were struggling?” Michael asked. I reminded him of the three conversations where I’d requested a repayment plan. Each time, Vanessa had accused me of trying to control them, and he had promised to discuss it later. Later had never arrived.
Vanessa announced that she’d contact a lawyer because I had damaged their credit. I told her my attorney could review any allegation. Then I slid across the notice I’d drafted: future support was ending, and they had thirty days to transfer any essential services in my name to accounts they controlled.
Michael studied the paper, then admitted he had believed my pension was much larger. I told him my pension was modest and that I’d been drawing down savings to keep them comfortable. Vanessa stared at the floor for the first time. Neither offered an apology.
After they left, Michael sent a message asking for copies of every bill and account deadline. I sent the spreadsheet and service-provider contacts, but no money. That evening he called again, speaking more quietly. “Mom,” he said, “I had no idea how close you were to running out.”
Part 3
I wanted to believe Michael’s concern was genuine, but apologies required more than frightened words. I told him I would discuss practical steps, not another request for money. He agreed to meet me alone at the public library, where neither of us could easily turn the conversation into shouting.
Michael arrived with a notebook and a list of their actual household expenses. For the first time, he’d calculated what maintaining their lifestyle cost. Their combined income was enough for necessities, but luxury payments, credit-card balances, and impulse purchases consumed almost everything left over each month.
I suggested he speak with a nonprofit credit counselor and contact creditors before any missed payments occurred. He scheduled appointments and began transferring the phone and internet services into his name. I gave him account information he legitimately needed, but I didn’t co-sign a single new obligation.
Vanessa refused to attend the first counseling session. She told relatives I had cut off her family because I disliked her. When my sister asked for an explanation, I showed her the budget and the apartment listings Vanessa had brought. My sister said, “They’re treating your house like an inheritance you’re supposed to hand over early.”
A week later, Michael told me he and Vanessa had canceled the SUV lease after negotiating an early termination and reviewing the cost. They sold unused electronics, paused their vacations, and arranged realistic payment schedules. Some decisions were expensive, but their accounts were finally their responsibility.
Vanessa appeared at my door again the following Sunday. This time she came without property listings or threats. She apologized for calling me irresponsible and admitted she’d assumed I had unlimited money because I never complained. I accepted the apology without offering to resume a single payment.
I also changed the locks after retrieving the spare key I’d previously given them. That decision upset Michael, but I explained that my home was not an extension of theirs. They could visit when invited, and I would gladly share meals. They could no longer make decisions about my property.
Over the next three months, I rebuilt my emergency savings and stopped checking my phone in fear of another financial request. I planted roses along the back fence and repaired the porch swing my husband had loved. For the first time since his death, the house felt entirely peaceful.
Michael eventually thanked me for drawing a line. He said their budget meetings were uncomfortable but necessary, and he was embarrassed he’d allowed the burden to become invisible. Vanessa was still learning to accept limits, but she had stopped asking me to finance their purchases. That was progress enough.
One evening, Michael visited and found me reading on the porch. He asked whether I might someday leave him the house. I smiled and said, “Someday you’ll learn what my will says. Today, this is my home.” I had spent years paying thirty-one bills to keep the peace. Canceling them finally brought it back.